Follow the money · United Kingdom · spending 2025–26 · HMRC tax-gap estimate 2024–25
£1.37 trillion spent. What can Britain change?
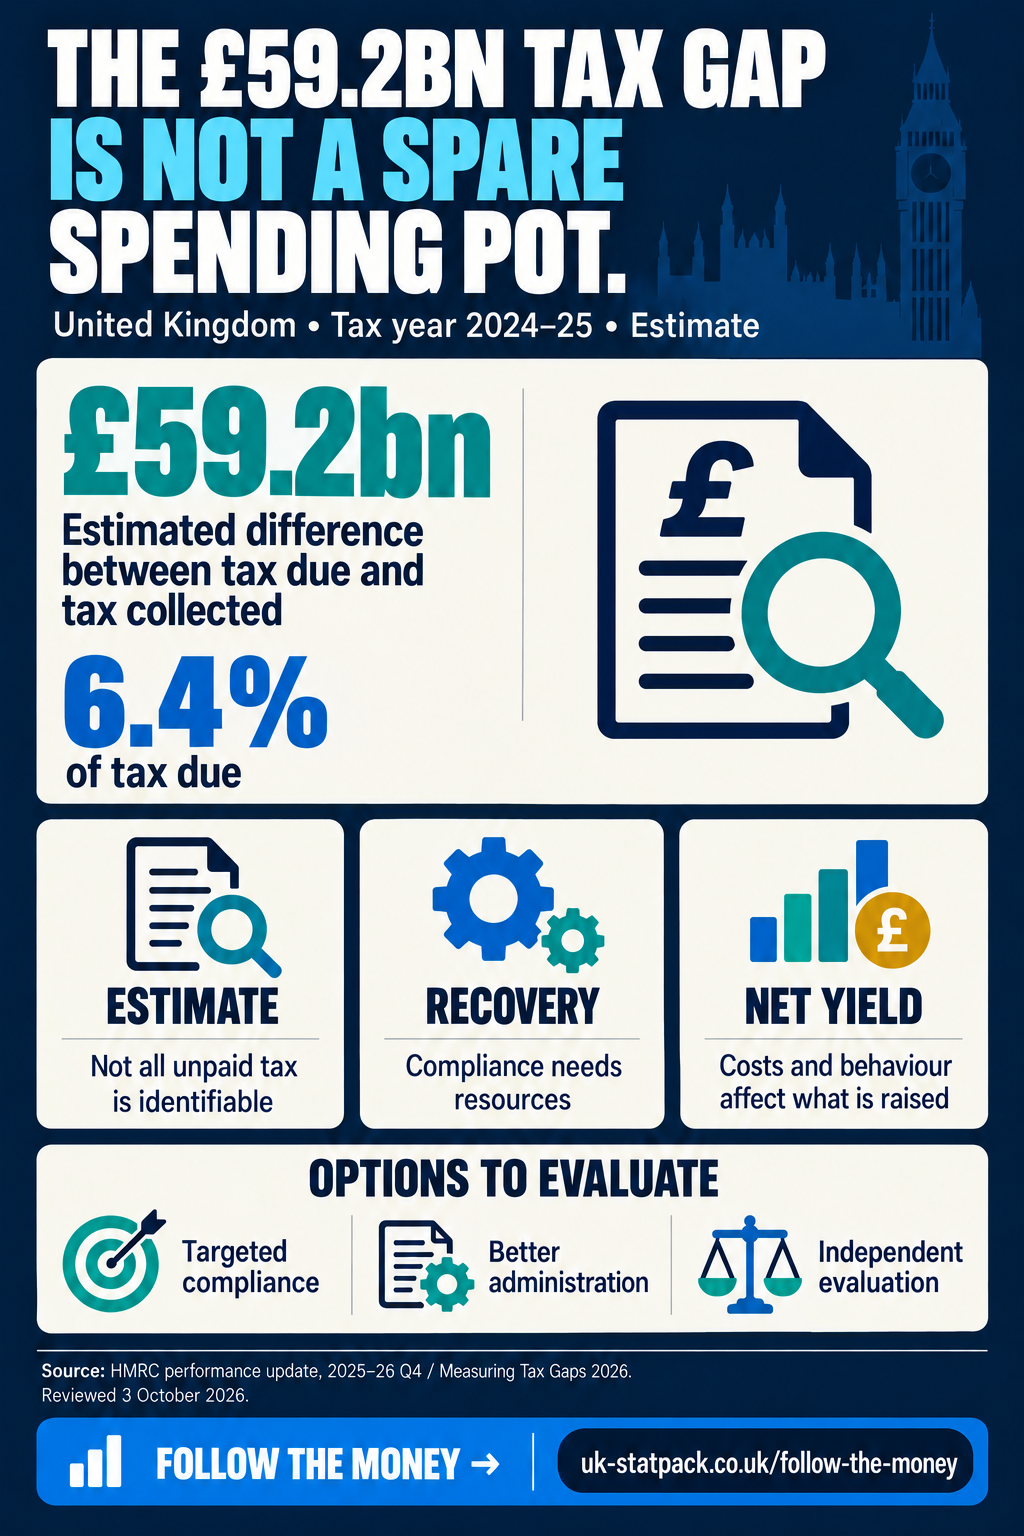
Total managed expenditure — everything the UK public sector spent, including benefits, public services and debt interest — was £1,366bn in 2025–26 (provisional). This page follows that money from allocation to delivery and results. HMRC’s estimated £59.2bn tax gap for 2024–25 is not a spare pot: it includes error, non-payment such as insolvency, and legal disputes.
Priority: Trace allocations through delivery to outcomes and find actionable leakage or underperformance. What would change it →
Evidence last reviewed 4 October 2026
Overview
The short version
Three key measures
How much does the state spend in a year, and on what?
£1,366bn
Total managed expenditure, against £1,231bn raised; the gap was borrowed. Social protection and health took 49% of spending in 2025–26 (Treasury PESA basis). All of it is already allocated by Parliament: moving money to a new priority means taking it from another line, raising tax or borrowing.
Public spending, on one annual basis →United Kingdom · 2025–26, provisional
Source: How much does the state spend in a year, and on what?
How much tax goes unpaid?
£59.2bn
HMRC’s estimate of tax due under current law but not paid: 6.4% of the £924.4bn due. It includes error, failure to take reasonable care, insolvency and legal disputes as well as evasion and criminal attacks, so it is not all fraud or a spendable pot. Separately, the government’s compliance package (begun at Autumn Budget 2024 and extended since) is expected to raise £10bn a year by 2029–30.
Uncollected tax and recoverable yield →United Kingdom · 2024–25 (projected)
Source: How much tax goes unpaid?
Official estimate · HMRC, Measuring tax gaps 2026 edition, 1. Tax gaps: summary (estimates for the 2024 to 2025 tax year)
How much lost money comes back?
£1.8bn
Recovered of an estimated £10.9bn lost to fraud and error in Covid support schemes. The Counter Fraud Commissioner found much of the rest is now beyond recovery.
Contracts, losses and recoveries →United Kingdom · To December 2025
Source: How much lost money comes back?
Official estimate · HM Treasury, Pursuing Recoveries and Preventing Reoccurrence: Final Report of the Covid Counter Fraud Commissioner (CP 1462)
Who feels this most?
When tax goes unpaid, everyone else carries the cost through higher rates, more borrowing or less spending. Where the unpaid tax arises matters for what would work to collect it.
Follow it in three steps
- 1. Allocation — what Parliament has already allocated, line by line.
- 2. Delivery — what is bought, from whom, and whether contracts deliver.
- 3. Outcome — what comes back, and what could really be moved.
For borrowing, debt and interest see Public finances; for costed ways to raise more see Revenue options.
The evidence
From a headline sum to money that can fund services
Four kinds of money
Public debate moves between very large numbers that measure different things. Before comparing any two, ask: is it public or private money? Was it spent, or is it an estimate? Is it a year’s flow or a total over decades? Below, each kind of money has its own panel and its own scale, with a plain answer to whether government could spend it.
Which of these large numbers could government actually spend?
Four kinds of money, four different meanings
Each panel compares only items with the same period, scope and accounting basis. Bars start at zero; scales differ between panels, so bars must not be compared across them.
1. Public spending
Can government spend this? Already spent. It can be moved between priorities only by cutting something else, taxing more or borrowing more.
Largest functions of public spending, 2025–26 (PESA, £bn cash). Total £1360.1bn.
- Social protectionPensions, benefits, social care£407.3bn
- Health£257.5bn
- Public sector debt interestPESA gross measure£130.3bn
- Education£125.7bn
- Economic affairsIncluding transport£94.0bn
- DefenceUN COFOG definition, not NATO£65.4bn
Source: HM Treasury, Public Expenditure Statistical Analyses 2026 (16 July 2026)
2. Tax due but not paid
Can government spend this? No. It is an estimate of tax owed under current law that was not paid. Only what compliance work actually collects becomes revenue — and much of the gap is error, insolvency or disputed law.
HMRC tax gap by type of tax, 2024–25, £bn. These are the parts of one £59.2bn total, not additions to it: the corporation tax gap is a subset of the total.
- Corporation tax£21.0bn
- Income tax, National Insurance and capital gains tax£20.9bn
- VAT£12.1bn
- Excise duties£2.9bn
- Other taxes£2.3bn
Source: HMRC, Measuring tax gaps 2026 edition: online tables (23 June 2026)
3. Private profits and dividends
Can government spend this? No. It belongs to companies and their shareholders. Government can tax it (already, through corporation tax and levies) or regulate it; it cannot spend it.
Statutory group profit before tax, worldwide, financial years to March (£bn)
- National Grid plcYear to March 2026£4.18bn
- SSE plcYear to March 2026£1.84bn
Statutory group profit before tax, worldwide, calendar years (£bn)
- Drax Group plcCalendar year 2025£0.19bn
- Centrica plcCalendar year 2025£0.11bn
£0.645bn
Dividends declared by water companies in England and Wales in 2024–25 (£1.0bn in 2023–24), with sector net debt of £76.3bn at March 2025 (Ofwat). Dividends are paid from profit after tax and interest, so they are not comparable with the profit bars.
4. Money lost — and money recovered
Can government spend this? Only the recovered cash, once received. An estimated loss, a claim or an announced recovery is not money in the bank.
Covid support schemes: fraud and error, estimated loss and recoveries to December 2025 (£bn)
- Estimated lost to fraud and error£10.9bn
- Recovered so far£1.8bn
Source: HM Treasury, Pursuing Recoveries and Preventing Reoccurrence: Final Report of the Covid Counter Fraud Commissioner (CP 1462) (December 2025)
Public spending is real money already committed. The tax gap is a modelled estimate of tax not paid, much of it error, insolvency or disputed interpretation. Company profits are private and already taxed. Recoveries are the only money in these panels that can be added to the public purse — and of the Covid losses only about a sixth has come back. The comparison that matters is within each panel, not between them.
United Kingdom (company profits are worldwide group figures) · Public spending 2025–26; tax gap 2024–25; profits latest company year; Covid losses cumulative to December 2025 · Mixed: official statistics, official estimates and audited accounts — labelled in each panel
Sources, definitions and data — Four kinds of money, four different meanings
- Geography:
- United Kingdom (company profits are worldwide group figures)
- Measure:
- £ billion, cash
- Period:
- Public spending 2025–26; tax gap 2024–25; profits latest company year; Covid losses cumulative to December 2025
- Status:
- Mixed: official statistics, official estimates and audited accounts — labelled in each panel
- Calculation:
- As published, except company profits converted from £m to £bn and “other general public services” excluding debt interest (see /public-finances).
- Not included / breaks:
- No total across panels, and no ranking of one kind against another: the four are not alternatives to each other. Company profits are statutory, before tax and worldwide, not UK-only or “windfall” measures.
Source: HM Treasury, Public Expenditure Statistical Analyses 2026, Table 4.2 (released 16 July 2026). Chart MONEY-01.
View the data as a table
| Panel | Item | Value | Period / basis |
|---|---|---|---|
| Public spending | Social protection | £407.3bn | 2025–26, PESA |
| Public spending | Health | £257.5bn | 2025–26, PESA |
| Public spending | Public sector debt interest | £130.3bn | 2025–26, PESA |
| Public spending | Education | £125.7bn | 2025–26, PESA |
| Public spending | Economic affairs | £94.0bn | 2025–26, PESA |
| Public spending | Defence | £65.4bn | 2025–26, PESA |
| Tax gap (component of total) | Corporation tax | £21.0bn | 2024–25, HMRC table 1.2 |
| Tax gap (component of total) | Income tax, National Insurance and capital gains tax | £20.9bn | 2024–25, HMRC table 1.2 |
| Tax gap (component of total) | VAT | £12.1bn | 2024–25, HMRC table 1.2 |
| Tax gap (component of total) | Excise duties | £2.9bn | 2024–25, HMRC table 1.2 |
| Tax gap (component of total) | Other taxes | £2.3bn | 2024–25, HMRC table 1.2 |
| Tax gap | Total (the components above sum to it) | £59.2bn | 2024–25, HMRC table 1.2 |
| Private profits | National Grid plc | £4.18bn | Year to March 2026, statutory PBT |
| Private profits | SSE plc | £1.84bn | Year to March 2026, statutory PBT |
| Private profits | Drax Group plc | £0.19bn | Calendar year 2025, statutory PBT |
| Private profits | Centrica plc | £0.11bn | Calendar year 2025, statutory PBT |
| Private payments | Water company dividends, England and Wales | £0.645bn | 2024–25, Ofwat |
| Losses and recoveries | Estimated lost to fraud and error | £10.9bn | Covid schemes, to Dec 2025 |
| Losses and recoveries | Recovered so far | £1.8bn | Covid schemes, to Dec 2025 |
Scroll the table sideways to see every column.
Public ownership changes who receives the profits in panel 3, at the cost of buying the companies and taking on their debt. Two models set out the arithmetic: water and the electricity grid.
Who feels this most?
Whose tax goes unpaid?
Small businesses account for 62% of the tax gap; large businesses for 12%
HMRC tax gap by customer group, 2024–25, £bn. Total £59.2bn.
- Small businesses£36.7bn
- Large businesses£7.1bn
- Criminals£5.0bn
- Mid-sized businesses£4.1bn
- Wealthy individuals£3.6bn
- Other individuals£2.7bn
Unpaid tax is concentrated among small businesses, not large companies or wealthy individuals. Across all taxpayers, HMRC’s illustrative split puts most of the gap down to error and failure to take reasonable care rather than evasion or avoidance (it does not publish that split by customer group). That pattern suggests help with record-keeping and simpler rules matter as much as investigations, though HMRC has not evaluated which works best.
United Kingdom · 2024–25 (projected from earlier data) · Official statistics; the latest two years are projections, and the small-business corporation tax gap carries a high uncertainty rating
Sources, definitions and data — Small businesses account for 62% of the tax gap; large businesses for 12%
- Geography:
- United Kingdom — Taxpayers grouped by HMRC customer segment
- Measure:
- £ billion
- Period:
- 2024–25 (projected from earlier data)
- Status:
- Official statistics; the latest two years are projections, and the small-business corporation tax gap carries a high uncertainty rating
- Calculation:
- As published (Table 1.3). “Wealthy” is HMRC’s wealthy-individuals segment.
- Compare with:
- Total tax gap £59.2bn
- Not included / breaks:
- Group shares describe where unpaid tax arises, not who is dishonest: most of the gap is error and failure to take reasonable care rather than evasion.
Source: HMRC, Measuring tax gaps 2026 edition: online tables, Table 1.2 (by type of tax, with total liabilities), Table 1.3 (by customer group), Table 7.1 (illustrative, by behaviour), column 2024-25 (released 23 June 2026). Chart MONEY-03.
View the data as a table
| Customer group | 2024–25, £bn |
|---|---|
| Small businesses | £36.7bn |
| Large businesses | £7.1bn |
| Criminals | £5.0bn |
| Mid-sized businesses | £4.1bn |
| Wealthy individuals | £3.6bn |
| Other individuals | £2.7bn |
What can actually be reallocated?
How does a headline amount become money a government can use?
From a headline amount to cash available — most steps are not established
A worked example using the tax gap. Equal-width steps show sequence only; they are not proportional to money.
Mechanism: the steps between a headline number and a public service
- 1
Headline amount
HMRC’s tax gap: £59.2bn in 2024–25. An estimate of tax due but not paid. Source: HMRC.
- 2
What could be collected
Remove insolvency, honest error that cannot be traced, disputed law and behaviour that moves elsewhere. Size of the collectable share: not established.
- 3
Deliverable net yield
A costed package: £10bn a year by 2029–30 from 5,500 new compliance caseworkers and about 2,400 debt-management posts (1,200 retained, 1,200 new). Source: HMRC performance update, 2026–27 quarter 1.
- 4
Budget decision
The yield is already in the fiscal forecasts and is not earmarked for any service. A decision to spend it is separate.
- 5
Service capacity
What the money would buy depends on staff, buildings and time. For this yield: not established.
- 6
Measured outcome
An improvement in a service measure attributable to the money: not established.
A large headline number has to pass through several filters before it can pay for anything: what is realistically collectable, what a costed programme delivers, a separate decision to spend it, and the capacity to turn money into services. For the tax gap, only one step after the headline — the £10bn costed package — has a published figure. That is why this site no longer lists what closing the gap “could fund”.
United Kingdom · 2024–25 gap; yield to 2029–30 · Mechanism diagram, not a causal estimate
Sources, definitions and data — From a headline amount to cash available — most steps are not established
- Geography:
- United Kingdom
- Measure:
- Not quantitative (sequence)
- Period:
- 2024–25 gap; yield to 2029–30
- Status:
- Mechanism diagram, not a causal estimate
- Calculation:
- None. Each step cites its source or says “not established”.
Source: HM Treasury, Autumn Budget 2024 (HC 295), section “Closing the tax gap”: £6.5 billion a year by 2029-30 (released 30 October 2024). Chart MONEY-02.
View the data as a table
| Step | Evidence |
|---|---|
| Headline amount | HMRC’s tax gap: £59.2bn in 2024–25. An estimate of tax due but not paid. Source: HMRC. |
| What could be collected | Remove insolvency, honest error that cannot be traced, disputed law and behaviour that moves elsewhere. Size of the collectable share: not established. |
| Deliverable net yield | A costed package: £10bn a year by 2029–30 from 5,500 new compliance caseworkers and about 2,400 debt-management posts (1,200 retained, 1,200 new). Source: HMRC performance update, 2026–27 quarter 1. |
| Budget decision | The yield is already in the fiscal forecasts and is not earmarked for any service. A decision to spend it is separate. |
| Service capacity | What the money would buy depends on staff, buildings and time. For this yield: not established. |
| Measured outcome | An improvement in a service measure attributable to the money: not established. |
The same test applies to every large number. An estimated loss is not a recovery; an award or a court claim is not cash received; a private company’s profit is not a public budget line. Where a costed, mutually exclusive option exists it is on the revenue options page, with what is already counted in the forecasts.
Shareable visual summary
Visual summary
Image currentEvery figure printed in the image matches today’s record, and its primary sources have been checked.
£1.37 trillion spent. What can Britain change?
Total managed expenditure — everything the UK public sector spent, including benefits, public services and debt interest — was £1,366bn in 2025–26 (provisional). This page follows that money from allocation to delivery and results. HMRC’s estimated £59.2bn tax gap for 2024–25 is not a spare pot: it includes error, non-payment such as insolvency, and legal disputes.
UK public sector, 2025-26
- £1,231bnraised (current receipts)
- £1,366bnspent (total managed expenditure)
Provisional outturn; the difference was borrowed.
Separately: tax due but not paid
- £59.2bnHMRC tax-gap estimate, 2024–25
- 6.4%of tax due
Includes error, insolvency and legal disputes as well as evasion: not a spendable pot.
Text and data version
£1.37 trillion spent. What can Britain change? Total managed expenditure — everything the UK public sector spent, including benefits, public services and debt interest — was £1,366bn in 2025–26 (provisional). This page follows that money from allocation to delivery and results. HMRC’s estimated £59.2bn tax gap for 2024–25 is not a spare pot: it includes error, non-payment such as insolvency, and legal disputes.
| Measure | Value | Period | Geography | Type | Source |
|---|---|---|---|---|---|
| Public sector current receipts | £1,231bn | 2025-26 | United Kingdom | survey estimate (provisional) | Office for Budget Responsibility, Public Finances Databank |
| Total managed expenditure | £1,366bn | 2025-26 | United Kingdom | survey estimate (provisional) | Office for Budget Responsibility, Public Finances Databank |
| UK tax gap | £59.2bn | 2024–25 | United Kingdom | model assumption | HMRC, Measuring tax gaps 2026 edition: tax gap estimates for 2024 to 2025, Table 1.1 |
| Tax gap as a share of theoretical liabilities | 6.4% | 2024–25 | United Kingdom | model assumption | HMRC, Measuring tax gaps 2026 edition: tax gap estimates for 2024 to 2025, Table 1.1 |
Image description: Follow the money infographic: HMRC estimates a £59.2bn UK tax gap in 2024–25, 6.4% of tax due — not a directly spendable pot.
All visual summaries, their source records and their publication state are listed on Shareable visuals.
Go deeper
Public spending, on one annual basis£1,366bn in 2025–26, led by pensions, benefits and health.The biggest lines, from the Treasury’s own analysis.Read the chapter → Public spending, on one annual basis How much unpaid tax could actually be collected?A £59.2bn gap; the largest costed package expects £10bn a year.The gap by behaviour, and what compliance work yields.Read the chapter → How much unpaid tax could actually be collected? Private profits and dividends: whose money is it?Companies’ and shareholders’ — government can tax or regulate it, not spend it.Energy and water companies on a stated basis.Read the chapter → Private profits and dividends: whose money is it? What does migration add to or take from the public finances?It depends on age, earnings and period — studies of different cohorts cannot be merged.An OBR-based scenario, with what cannot be calculated.Read the chapter → What does migration add to or take from the public finances? Did specific contracts deliver, and what was recovered?Announcements, awards, delivery and recoveries are tracked as separate stages.The procurement ledger.Read the chapter → Did specific contracts deliver, and what was recovered? What can actually be reallocated?Only money that survives each step from estimate to budget decision.A worked example of the bridge.Read the chapter → What can actually be reallocated?
Evidence → choices → outcomes
What could improve it?
More legitimate tax collected and public contracts that deliver what they were bought for, counted as cash actually received.
These options link to their national assessment, including funding, delivery constraints and remaining uncertainties.
Assessed option · provisional
Deliver what is already funded
8/10 criteria scored
Coverage of the appraisal, not an impact score.
Delivery: Amber
Whole-life costs incomplete
Evidence and delivery constraints
Audits diagnose failures; no general cash saving is established for this proposal.
Name contracts, renewal dates and weaknesses; recruit commercial expertise; publish baselines, performance and remedies.
Assessed option · provisional
Collect the tax already due
8/10 criteria scored
Coverage of the appraisal, not an impact score.
Delivery: Amber
Whole-life costs incomplete
Evidence and delivery constraints
Compliance activity can yield revenue; the return from the proposed extra high-wealth focus is not established here.
Reconcile existing forecast baseline; define cases, staff, legal powers and collection horizon; audit net additional receipts.
Assessed option · provisional
Protect water supplies and low-income households
Target a defined unmetered cohort in designated stressed areas.
9/10 criteria scored
Coverage of the appraisal, not an impact score.
Delivery: Amber
Whole-life costs incomplete
Evidence and delivery constraints
English household-panel evidence supports lower consumption after metering; the proposed tariff package is not separately evaluated.
Compare the extra cohort with the committed rollout; cost meters and tariff protection before proceeding. Require a funded protection design and additional rollout baseline; do not automatically generalise one company estimate.
How we assessed these options
What would it take to improve this?
What would move the needle?
The outcome we want: More legitimate tax collected and public contracts that deliver what they were bought for, counted as cash actually received.
The main constraint: HMRC cannot say what extra cash more enforcement would bring, over half the gap comes from error and lack of care rather than evasion and most of it arises among small businesses, and contracting authorities lack contract-management staff — so the binding constraints are evidence and capacity, not a pot of money waiting to be found.
Constraint type: evidence, workforce.
The options on the table
What is funded now, and the changes assessed against it — the current baseline and the alternatives, before the position today and the actions.
Provisional single-reviewer assessments from the 6 October 2026 review; not approved business cases, and not government policy.
Deliver what is already fundedDelivery RAG: Amber
- Funded now
- Not yet stated in the record.
- The change assessed
- Not yet defined.
Range if completed: 14.0–20.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))
Collect the tax already dueDelivery RAG: Amber
- Funded now
- A large package is already funded and running: Autumn Budget 2024 expected £6.5bn a year by 2029–30 from 5,000 extra compliance staff and 1,800 debt-management staff. Later measures raised this: HMRC’s August 2026 update gives £10bn of additional tax revenue a year by 2029–30 and plans for 5,500 new compliance caseworkers (more than 2,400 compliance staff recruited since Autumn Budget 2024). That yield is already in the fiscal forecasts. Any further package beyond it is a UK Facts proposal.
- The change assessed
- Not yet defined.
Range if completed: 13.0–19.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))
Meter water-stressed households with an effective social tariffDelivery RAG: Amber
- Funded now
- Builds on announced policy: the January 2026 white paper commits companies to smart meters for 50% of homes and businesses by 2030 and to changes in tariff structures, and companies in seriously water-stressed areas may already meter compulsorily (Southern Water did so in 2010–15). Metering every home in those areas with a protected social tariff is a UK Facts proposal, not government policy.
- The change assessed
- Target a defined unmetered cohort in designated stressed areas; protect affordability and distinguish use from leakage.
Range if completed: 18.0–21.0 out of 30 (equal weights; not yet assessed: incremental affordability (Co))
Alternatives already on record: 25 options listed under the points in the position today (17 without an action record), and 3 earlier options under other options compared. They have not been scored in the review.
The position today
Which quadrant a point sits in is our analytical judgement, not a statistical category. Each point says whether it is a measured fact, our synthesis or a risk.
What we can build on Strengths
HMRC publishes an annual tax-gap estimate broken down by tax, customer group and behaviour, with an uncertainty rating for each part.
Measured factConfidence: High· tax year 2024–25 (2026 edition)· United Kingdom
Source: HM Revenue and Customs, Measuring tax gaps 2026 edition: tax gap estimates for 2024 to 2025 (Tables 1.2, 1.3 and 7.1)
Options assessed against this point: Collect the tax already due (Amber delivery RAG)
What government has committed to
Policy: HMRC publishes Measuring Tax Gaps every year and plans stand-alone customs-duty and offshore gaps (“aim to publish in 2027”) and better estimates for wealthy taxpayers and small businesses.
- Who and when:
- Starmer government (to July 2026), 23 June 2026.
- Since 20 July 2026:
- Kept by the Burnham government. HMRC folded its interim VAT-gap releases into the annual publication; the share of the gap rated high uncertainty rose to 35%. Source: HM Revenue and Customs, 2026 HMRC statistics announcements (Entry of 7 September 2026 (VAT gap within Measuring Tax Gaps 2027)).
- Source:
- HM Revenue and Customs, Measuring tax gaps 2026 edition: summary, “Future priorities” and “Uncertainty” (“Future priorities for the tax gap”)
Checked 4 October 2026. A commitment is not delivery.
Options (3)
ShortlistedCollect more tax through specific, auditable compliance work
Reports cash collected against each named part of the estimate, tying the statistic to recovery.
Who: HMRC; HM Treasury · Evidence: Expert or audit recommendation · Status: Funded programme
Source: National Audit Office, Taxing large businesses (27 February 2026) (Paragraph 1.12)
Publish the stand-alone offshore and customs-duty gaps
Fills the two least-measured parts of the estimate.
Who: HMRC · Evidence: Expert or audit recommendation · Status: Announced proposal
Source: HM Revenue and Customs, Measuring tax gaps 2026 edition: summary, “Future priorities” and “Uncertainty” (“Future priorities”)
Keep the uncertainty ratings and revisions visible
Stops a precise-looking total being read as exact.
Who: UK Facts · Evidence: Observational analysis · Status: Site-editorial action
Source: HM Revenue and Customs, Measuring tax gaps 2026 edition: summary, “Future priorities” and “Uncertainty” (“Uncertainty”)
The National Audit Office audits how HMRC measures its compliance results, and states plainly that “compliance yield” is revenue collected or protected, not cash.
Measured factConfidence: High· 2024–25 (published February 2026)· United Kingdom
Source: National Audit Office, Taxing large businesses (HC 1647, Session 2024–26) (Paragraph 1.12)
What government has committed to
Target: HMRC aims to raise compliance yield again in 2026-27, with at least a quarter from work that prevents non-compliance before it happens (it reported more than £50bn against a £50.4bn target in 2025-26); there is no commitment to report cash separately from revenue protected.
- Who and when:
- Burnham government (from 20 July 2026), 13 August 2026.
- Since 20 July 2026:
- Made by the current government. The NAO’s audit role is unchanged.
- Source:
- HM Revenue and Customs, HMRC performance update: 2026 to 2027 quarter 1 (13 August 2026) (“Close the Tax Gap”, paragraph 2)
Checked 4 October 2026. A commitment is not delivery.
Options (3)
Collect more tax through specific, auditable compliance work
Splits yield into cash collected, protected and upstream, removing the ambiguity this item describes.
Who: HMRC · Evidence: Expert or audit recommendation · Status: Funded programme
Source: National Audit Office, Taxing large businesses (27 February 2026) (Paragraph 1.12 (“collected or protected”))
Record which risk each intervention tackled and how it was resolved
Makes yield auditable case by case.
Who: HMRC · Evidence: Expert or audit recommendation · Status: External proposal
Source: National Audit Office, Taxing large businesses (27 February 2026) (Summary, recommendation 22b)
Publish expected marginal returns by customer group
Shows where more staff would add most.
Who: HMRC · Evidence: Expert or audit recommendation · Status: External proposal
Source: National Audit Office, Taxing large businesses (27 February 2026) (Paragraph 3.6)
What is holding us back Weaknesses
The estimated tax gap was £59.2bn (6.4% of tax due). £20.8bn came from failure to take reasonable care and £9.3bn from error; £36.7bn arose among small businesses.
Measured factConfidence: Moderate· tax year 2024–25· United Kingdom
Source: HM Revenue and Customs, Measuring tax gaps 2026 edition: tax gap estimates for 2024 to 2025 (Tables 1.2, 1.3 and 7.1 (latest year is a projection))
Options assessed against this point: Collect the tax already due (Amber delivery RAG)
What government has committed to
Funding: A small-business evasion team of 350 criminal investigators; Making Tax Digital for Income Tax for incomes above £50k (April 2026), £30k (April 2027) and £20k (April 2028); in-service nudges to prevent errors. No target for the size of the gap.
- Who and when:
- Starmer government (to July 2026), 26 November 2025.
- Since 20 July 2026:
- Kept by the Burnham government. HMRC reported the investigators in post under the Burnham government; no new small-business measure was found. Source: HM Revenue and Customs, HMRC performance update: 2026 to 2027 quarter 1 (13 August 2026) (“we have recruited a new team of 350 criminal investigators”).
- Source:
- HM Treasury, Budget 2025 (HTML) (Chapter 5.9 “Tackling non-compliance on the high street”)
Checked 4 October 2026. A commitment is not delivery.
Options (4)
ShortlistedCollect more tax through specific, auditable compliance work
Pilots one intervention on a named small-business segment and counts net cash beyond the forecast.
Who: HMRC; HM Treasury · Evidence: Expert or audit recommendation · Status: Funded programme
Source: HM Revenue and Customs, Measuring tax gaps 2026 edition: tax gap estimates for 2024 to 2025 (Tables 1.3 and 7.1)
Making Tax Digital with error-prevention prompts
Digital records and prompts target the error and reasonable-care parts of the gap.
Who: HMRC · Evidence: Untested proposal · Status: Established
Source: HM Revenue and Customs, HMRC Transformation Roadmap update 2026 (2 July 2026) (Sections 3.1 and 4.2)
Targeted high-street enforcement
Criminal investigation of deliberate small-business evasion.
Who: HMRC · Evidence: Untested proposal · Status: Funded programme
Source: HM Treasury, Budget 2025 (HTML) (Chapter 5.9)
Third-party data on account and card sales
Reported sales data make under-declaration easier to spot.
Who: HMRC; Parliament · Evidence: Untested proposal · Status: Announced proposal
Source: HM Revenue and Customs, HMRC Transformation Roadmap update 2026 (2 July 2026) (Section 3.1)
Estimated gaps, assessed yields and cash are easily confused: compliance yield includes revenue “protected”, and the £10bn-a-year compliance package expected by 2029–30 is already in the forecasts.
Our synthesisConfidence: High
Source: National Audit Office, Taxing large businesses (HC 1647, Session 2024–26) (Paragraph 1.12); HM Revenue and Customs, HMRC performance update: 2026 to 2027 quarter 1 (13 August 2026) (“£10 billion of additional tax revenue per year by 2029 to 2030”); HM Treasury, Autumn Budget 2024 (HC 295): “Closing the tax gap” (“Closing the tax gap” (the first £6.5bn))
What government has committed to
Funding: The tax-gap package is now expected to raise £10bn a year by 2029-30 — £6.5bn from Autumn Budget 2024, about £1bn more at Spring Statement 2025 and £2.4bn at Budget 2025 — with 5,500 compliance and 2,400 debt staff; all of it is already in the forecasts.
- Who and when:
- Starmer government (to July 2026), 26 November 2025.
- Since 20 July 2026:
- Kept by the Burnham government. Reaffirmed by HMRC under the Burnham government; the page’s “£6.5bn-a-year package” is the Autumn Budget 2024 part only. Source: HM Revenue and Customs, HMRC performance update: 2026 to 2027 quarter 1 (13 August 2026) (“£10 billion of additional tax revenue per year by 2029 to 2030”).
- Source:
- HM Treasury, Budget 2025 (HTML) (Section 3.3 “Further reforms to close the tax gap”)
Checked 4 October 2026. A commitment is not delivery.
Options (3)
Collect more tax through specific, auditable compliance work
Publishes yearly cash outturn of the package against its costing.
Who: HMRC; OBR · Evidence: Expert or audit recommendation · Status: Funded programme
Source: HM Treasury, Budget 2025 (HTML) (Section 3.3); National Audit Office, Taxing large businesses (27 February 2026) (Paragraph 1.12)
Show the tax gap, compliance yield and receipts as three labelled series
Keeps estimates, assessed yield and cash apart.
Who: UK Facts · Evidence: Observational analysis · Status: Site-editorial action
Source: National Audit Office, Taxing large businesses (27 February 2026) (Paragraph 1.12 (yield is revenue “collected or protected”))
Track the tax-debt ratio
A cash measure of what is owed and not yet paid.
Who: HMRC · Evidence: Observational analysis · Status: Funded programme
Source: HM Revenue and Customs, HMRC performance update: 2026 to 2027 quarter 1 (13 August 2026) (Tax debt passage)
What could improve things Opportunities
Targeting named parts of the gap — including help with record-keeping where error dominates — and publishing outcomes for renewing contracts would turn big theoretical numbers into auditable cash and services.
Depends on: Each measure counts only cash beyond what forecasts already include, with overheads and taxpayer safeguards.
Our synthesisConfidence: Moderate
Source: National Audit Office, Taxing large businesses (HC 1647, Session 2024–26) (Paragraph 3.6); Institute for Government, The role of procurement in delivering mission-led government (Report PDF pp.4–5)
Options assessed against this point: Deliver what is already funded (Amber delivery RAG)
What government has committed to
Legislation: The Procurement Act 2023 requires at least three published KPIs on contracts over £5m and a published assessment at least once every twelve months.
- Who and when:
- Earlier UK government (before July 2024), 26 October 2023.
- Since 20 July 2026:
- Kept by the Burnham government. The Burnham government added an Insourcing Unit alongside the Public Interest Test for service contracts above £1m. Source: Cabinet Office, Measures to rewire the state (27 September 2026) (Insourcing Unit passage).
- Source:
- legislation.gov.uk, Procurement Act 2023, section 52 (key performance indicators) (Sections 52 and 71)
Checked 4 October 2026. A commitment is not delivery.
Options (3)
ShortlistedBuy measurable results and manage contracts through delivery
Outcome and milestone baselines for renewing contracts turn reporting duties into auditable results.
Who: Cabinet Office; departments · Evidence: Expert or audit recommendation · Status: Site-editorial action
Source: Institute for Government, The role of procurement in delivering mission-led government (Report PDF pp.4–5)
Collect more tax through specific, auditable compliance work
Names one part of the gap and counts net cash.
Who: HMRC · Evidence: Expert or audit recommendation · Status: Funded programme
Source: National Audit Office, Taxing large businesses (27 February 2026) (Paragraph 1.12)
Apply the Public Interest Test before re-procuring service contracts
Compares in-house and outsourced delivery before renewal.
Who: Cabinet Office; departments · Evidence: Untested proposal · Status: Enacted but not operational
Source: Cabinet Office, PPN 024: the Public Interest Test and insourcing strategy (Paragraph 7)
Water bill-payers are funding a £104bn upgrade of the water sector in 2025–30, including nine new reservoirs and £700m to cut leakage; steering that money, and how water is charged, at the projected supply gap could close more of it for each pound billed.
Depends on: The new regulator ties allowances to delivered supply and lower use, reservoir schemes keep to their timetables, and low-income households are protected from charging changes.
Our synthesisConfidence: Moderate
Source: Department for Environment, Food & Rural Affairs, A new vision for water (white paper) (Key figures, PDF p.11; Water Security chapter, PDF p.42); Environment Agency, National Framework for Water Resources 2025: water for growth, nature and a resilient future (Executive summary)
Options assessed against this point: Meter water-stressed households with an effective social tariff (Amber delivery RAG)
What government has committed to
Policy: The water white paper commits to nine new reservoirs, halving leakage by 2050 (30% by 2032), smart meters for half of homes and businesses by 2030, statutory resilience standards and a single regulator replacing Ofwat.
- Who and when:
- Starmer government (to July 2026), 20 January 2026.
- Since 20 July 2026:
- Not confirmed either way since the change of Prime Minister on 20 July 2026. No Burnham-government statement on the white paper was found. Drought management continues through weekly National Drought Group meetings (Environment Agency, September 2026).
- Source:
- Department for Environment, Food & Rural Affairs, A new vision for water (white paper) (Key figures, PDF p.11; Water Security chapter, PDF p.42)
Checked 4 October 2026. A commitment is not delivery.
Options (2)
ShortlistedMeter homes in water-stressed areas, with a social tariff
Charging by use cuts consumption; the tariff protects low-income households.
Who: Defra and the water regulator, with water companies · Evidence: Experimental or quasi-experimental evaluation · Status: External proposal
Source: University of Southampton, Department of Economics (Discussion Paper 1801), The effects of the Universal Metering Programme on water consumption, welfare and equity (Abstract; Section 6)
Tie the new regulator’s allowances to water delivered and use reduced, not money spent
Pays companies for closing the supply gap rather than for capital spending alone.
Who: Defra and the new regulator · Evidence: Untested proposal · Status: External proposal
What could make it worse Threats
Plans that bank recoveries can fund services with money that never arrives: of an estimated £10.9bn lost to fraud and error in Covid schemes, £1.8bn has been recovered.
Risk, not a certaintyConfidence: High
Source: HM Treasury, Pursuing Recoveries and Preventing Reoccurrence: Final Report of the Covid Counter Fraud Commissioner (CP 1462) (Final report of the Covid Counter Fraud Commissioner)
What government has committed to
Legislation: The Public Authorities (Fraud, Error and Recovery) Act 2025 gives a 12-year limitation period for civil claims over Covid fraud; the June 2026 response to the Covid Counter-Fraud Commissioner promised enforcement from autumn 2026 and a scrutiny panel.
- Who and when:
- Starmer government (to July 2026), 2 December 2025.
- Since 20 July 2026:
- Changed by the Burnham government. The Burnham government keeps the powers but is moving the Public Sector Fraud Authority’s functions to DWP. Source: House of Lords, Public Sector Fraud Authority, House of Lords, 14 September 2026 (Hansard) (Baroness Twycross on the PSFA’s “repositioning into the Department for Work and Pensions”).
- Source:
- legislation.gov.uk, Public Authorities (Fraud, Error and Recovery) Act 2025, section 105 (Section 105(3)–(4))
Checked 4 October 2026. A commitment is not delivery.
Options (4)
Prevent and recover public-sector fraud and error
Pursues recoveries under the new powers and prevents loss in future schemes.
Who: Public Sector Fraud Authority (moving to DWP); departments · Evidence: Expert or audit recommendation · Status: Established
Source: Cabinet Office / Public Sector Fraud Authority, Government response to the final report of the Covid Counter-Fraud Commissioner (23 June 2026) (Introduction; legislation section)
Count only cash received, never announced recoveries
Stops plans banking money that may not arrive.
Who: HM Treasury; UK Facts · Evidence: Observational analysis · Status: Site-editorial action
Source: Cabinet Office / Public Sector Fraud Authority, Government response to the final report of the Covid Counter-Fraud Commissioner (23 June 2026) (Introduction (£1.8bn of £10.9bn))
Build fraud risk and a clean-up cost into crisis schemes from the start
Reduces loss in the next emergency programme.
Who: HM Treasury · Evidence: Expert or audit recommendation · Status: Established
Source: Cabinet Office / Public Sector Fraud Authority, Government response to the final report of the Covid Counter-Fraud Commissioner (23 June 2026) (Recommendation 3b)
Let departments keep a share of what they recover
Gives departments an incentive to pursue recoveries.
Who: HM Treasury · Evidence: Expert or audit recommendation · Status: Announced proposal
Source: Cabinet Office / Public Sector Fraud Authority, Government response to the final report of the Covid Counter-Fraud Commissioner (23 June 2026) (Recommendation 4a)
Average returns overstate what more staff would bring: HMRC could not tell the NAO the marginal return to further investment, and in its large-business directorate — the only unit the audit covers — returns fall from about £95 to about £58 per £1 once overheads are counted.
Risk, not a certaintyConfidence: Moderate
Source: National Audit Office, Taxing large businesses (HC 1647, Session 2024–26) (Paragraph 3.6 and footnote 10)
Options assessed against this point: Collect the tax already due (Amber delivery RAG)
What government has committed to
No commitment found. No commitment to estimate or publish the marginal return to more compliance staff was found. The NAO’s £95 (about £58 with overheads) per £1 applies to the large business directorate only; HMRC compliance overall returns about £25.
Searched: gov.uk “compliance yield”, “tax gap” since 20 July 2026; HMRC transformation roadmap; HMRC Q1 update; Hansard 20 July–4 October 2026; 4 Oct 2026
Checked 4 October 2026. A commitment is not delivery.
Options (3)
ShortlistedCollect more tax through specific, auditable compliance work
An OBR-scrutinised net-cash costing that includes overheads and appeals.
Who: HMRC; OBR · Evidence: Expert or audit recommendation · Status: Funded programme
Source: National Audit Office, Taxing large businesses (HC 1647, Session 2024–26) (Paragraphs 1.12 and 3.6)
Estimate marginal returns before adding staff
Tests whether more staff bring the average return.
Who: HMRC · Evidence: Expert or audit recommendation · Status: External proposal
Source: National Audit Office, Taxing large businesses (27 February 2026) (Paragraph 3.6)
Deploy new staff in phases to measure their yield
A phased or randomised roll-out shows the marginal return directly.
Who: HMRC; Evaluation Task Force · Evidence: Untested proposal · Status: External proposal
Source: HM Treasury, Magenta Book: central government guidance on evaluation (HTML, May 2026) (Test and Learn annex)
The actions worth examining
Our shortlist for this page. Research quality, policy status, cost and funding are judged separately; none of these is government policy unless its status says so.Our shortlist. None is government policy unless its status says so.
Action 1A19Policy status: funded programme
Collect more tax through specific, auditable compliance work
Target a named part of the gap with a specific intervention (support, digital checks or enforcement), and count only the extra cash collected beyond what forecasts already include.
The thread: issue, evidence, action
Assessment (draft, 6 October review)
This action: Collect the tax already due
Delivery RAG: AmberGate: pending
Range if completed: 13.0–19.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))
National plan: Equality and opportunity list
- Who decides:
- HMRC and HM Treasury; Parliament for new powers; the OBR certifies costings (UK)
- Evidence:
- Expert or audit recommendation. An NAO audit supports the logic of compliance work but shows that average past returns do not reveal the return to extra staff.
- Expected effect:
- Direction plausible; size not established.
- Cost and funding
Not yet costed
Funding: Not yet costed / funding not identified
Why it is shortlisted here: Replaces the idea of a giant recoverable pot with specific, auditable cash beyond what forecasts already include.
What it takes
The problem
Headline tax-gap figures are treated as money waiting to be collected, but just over half the gap comes from error and failure to take reasonable care, about three-fifths of it arises among small businesses, and the extra yield from more enforcement is not known.
Who is affected, and where
UK taxpayers in the targeted segment (for example small businesses), and everyone who relies on public services. Territory: UK. HMRC administers UK taxes; Scottish and Welsh income tax and devolved taxes (Revenue Scotland, Welsh Revenue Authority) need their own arrangements, not assessed here.
Policy status
A funded programme already exists. A large package is already funded and running: Autumn Budget 2024 expected £6.5bn a year by 2029–30 from 5,000 extra compliance staff and 1,800 debt-management staff. Later measures raised this: HMRC’s August 2026 update gives £10bn of additional tax revenue a year by 2029–30 and plans for 5,500 new compliance caseworkers (more than 2,400 compliance staff recruited since Autumn Budget 2024). That yield is already in the fiscal forecasts. Any further package beyond it is a UK Facts proposal.
The evidence
- What the research found:
- The NAO found compliance yield of £15.8bn in 2024–25 is revenue “collected or protected”, not cash; it equals about £95 per £1 of staff pay but about £58 per £1 with overheads, and HMRC could not say what marginal return further investment would bring.
- Evaluated on:
- HMRC’s large business directorate (about 2,000 groups); United Kingdom, 2017–18 to 2024–25
- Transfer to this case:
- Large-business returns do not transfer to small businesses, where most of the gap arises.
- Our recommendation (separate from the research):
- Publish, for any new package, the targeted gap, the expected cash beyond forecast, its cost including overheads and appeals, and taxpayer-service effects — and report cash collected each year.
- Strongest counter-evidence:
- Returns diminish as easier cases are worked; yield includes revenue “protected” that never arrives as cash; wrongly challenged taxpayers bear real costs.
Effects on record
- Net tax receipts beyond forecast: Direction plausible; size not established. plausible spillover, limited confidence; United Kingdom. HMRC could not tell the NAO the marginal return to further investment; average yield ratios overstate it, and yield is not all cash.
- Costs to compliant taxpayers wrongly challenged: A cost or harm; size not established. plausible spillover, limited confidence; United Kingdom. A risk to monitor through upheld disputes and service measures; not quantified.
Cost and funding
Cost completeness: Not yet costed. Funding: Not yet costed / funding not identified.
- HMRC staff, training, systems, appeals and overheads for a further compliance package (administration; paid by central government): Not yet costed. Staff-only return ratios omit overheads (the NAO puts large-business returns at about £95 per £1 of staff pay but about £58 with overheads), and average returns are not marginal returns. Collections must be profiled over several years.
- Who pays:
- HMRC (taxpayers) for staff, systems and appeals; compliant taxpayers and their advisers for time spent on checks.
- Financing proposed:
- None. The £6.5bn a year from the 2024 package is already counted in the forecasts and cannot pay for anything new; a further package needs its own HMRC funding and an independently scrutinised costing of net cash.
- Gap remaining:
- Unknown: no further package has been specified or costed.
What delivery needs
- Skills:
- Trained compliance and debt staff, who take time to become productive.
- Operational capacity:
- HMRC case-management and IT systems; tribunal capacity for disputes.
- Infrastructure:
- Data matching and digital records.
- Permissions:
- None beyond existing powers for most work.
- Law:
- New powers only for specific measures.
- Public consent:
- Public acceptance of checks; safeguards for taxpayers.
First step and stages
First step: Name one part of the gap, the intervention, and what the current forecast already assumes for it. (owner: HMRC with HM Treasury)
- Pilot the intervention on a defined segment — HMRC (proposed stage, not an official timetable)
- Cost and certify the net cash beyond forecast — HMRC, HM Treasury, OBR (proposed stage, not an official timetable)
- Scale only if cash collected holds up over several years — HMRC (proposed stage, not an official timetable)
Depends on: Recruitment and training under the 2024 package; OBR certification of any new costing
Trade-offs
- Who gains and who loses:
- Falls on non-compliant taxpayers, mostly small businesses; compliant firms gain from a level playing field; mistaken challenges burden honest taxpayers.
- What else the money or effort could do:
- HMRC staff on compliance are not answering customer queries or processing repayments.
- Strongest counterargument:
- Much of the gap is error, which simpler rules or better service may reduce more cheaply than enforcement.
- Risks:
- Spending the same forecast revenue twice; overstating yield; harming taxpayer service.
How we would judge it
- Baseline:
- Tax gap 6.4% of liabilities (£59.2bn) in 2024–25 (HMRC).
- Leading indicator:
- Cash collected from the targeted segment, reported separately from assessed yield.
- Outcome:
- Net cash beyond forecast, errors, disputes upheld and taxpayer service levels.
- Continue, adapt or stop:
- Stop or redesign if cash collected falls well below the costing, or upheld disputes and service complaints rise.
Earlier option on this page
This card replaces the option “Invest in HMRC compliance and debt collection” (funded: Announced at the Autumn Budget 2024 and in the forecasts.). Its evidence: The government expects its compliance package (Autumn Budget 2024, extended at later fiscal events) to raise £10bn a year by 2029–30. The Autumn Budget 2024 part (£6.5bn) was certified by the OBR. Most of the gap arises among small businesses, and HMRC attributes most of it to error and lack of care rather than evasion, so enforcement aimed at large companies reaches only a small share. HM Revenue and Customs, HMRC performance update: 2026 to 2027 quarter 1 · HM Treasury, Autumn Budget 2024 (HC 295) · HMRC, Measuring tax gaps 2026 edition, 1. Tax gaps: summary (estimates for the 2024 to 2025 tax year)
Sources
- National Audit Office, Taxing large businesses (HC 1647, Session 2024–26), Paragraphs 1.12 and 3.6 (2026-02-27; relevant passages checked)
- HM Treasury, Autumn Budget 2024 (HC 295): “Closing the tax gap”, “Closing the tax gap” (2024-10-30; relevant passages checked)
- HM Revenue and Customs, Measuring tax gaps 2026 edition: tax gap estimates for 2024 to 2025, Tables 1.3 and 7.1 (2026-06-23; relevant passages checked)
- National Audit Office, Taxing large businesses (HC 1647, Session 2024–26), Paragraph 3.6 (2026-02-27; relevant passages checked)
Source published February 2026 (NAO); October 2024 (Budget); June 2026 (HMRC tax gap); evidence reviewed 2026-10-04. Reconsider if: HMRC publishes outturn for the 2024 package; A new tax gap edition; A fiscal event announces further compliance funding.
Also on: Revenue options — one shared record, so its cost is counted once.
Action 2A23Policy status: site-editorial action
Buy measurable results and manage contracts through delivery
Specify the outcome before tender, publish whole-life cost and milestones, and staff skilled contract management for the life of the contract.
The thread: issue, evidence, action
- Issue Weakness (Public procurement): 34 of 172 rated government major projects were Red (successful delivery appears unachievable, with major issues that do not appear manageable at that stage), 16 ratings were withheld and 1 project was not yet rated. Also: opportunityHow acting here reaches it: Buying measurable results and managing contracts through delivery is meant to bring more major projects out of Red, the ratings the procurement page records for public money spent through contracts.
- Evidence Government major projects rated Red
- Action A23, this action
Assessment (draft, 6 October review)
A broad priority including this action (GRP-01): Deliver what is already funded
Delivery RAG: AmberGate: pending
Range if completed: 14.0–20.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))
National plan: Growth and prosperity list
- Who decides:
- Contracting authorities, the Cabinet Office (Government Commercial Function) and departments; the MOD for defence (UK)
- Evidence:
- Expert or audit recommendation. Consistent recommendations from research and audit; no evaluation estimates the savings or service effects.
- Expected effect:
- Direction plausible; size not established.
- Cost and funding
Not yet costed
Funding: Not yet costed / funding not identified
Why it is shortlisted here: Public contracts are the largest flow of public money on this page; delivery, not the size of the total, is what matters.
What it takes
The problem
Weak specification and thin contract-management capacity stop public purchases turning into the services and capabilities intended.
Who is affected, and where
Users of publicly contracted services and capabilities; suppliers, including small firms. Territory: UK. The Procurement Act 2023 applies to UK-wide and English bodies and Wales and Northern Ireland; Scotland largely keeps its own regime, not assessed here.
Policy status
UK Facts proposal. Builds on rules already in force: the Procurement Act 2023 (from 24 February 2025) requires KPIs and performance publication for larger contracts. Applying an outcome-and-milestone baseline to a named set of renewing contracts is a UK Facts proposal.
The evidence
- What the research found:
- The Institute for Government finds government buys more than £400bn a year and that late commercial involvement, over-specified procurements, poor data and weak contract-management capacity block delivery. RUSI argues defence requirements should be set with budget and technical authority together. The NAO found the MOD’s 2023–2033 equipment plan £16.9bn over budget.
- Evaluated on:
- UK central government procurement (interviews); MOD equipment programmes (audit and commentary); United Kingdom, 2023–2026
- Our recommendation (separate from the research):
- Publish outcome, whole-life cost and milestones for a defined set of renewing contracts and report them through delivery; fund commercial staff from named budgets where justified.
- Strongest counter-evidence:
- More reporting can deter small suppliers and add cost; outcome contracts are hard to specify for complex services; social-value requirements complicate price comparison.
Effects on record
- Contracts delivering the specified service on time and near cost: Direction plausible; size not established. plausible spillover, limited confidence; United Kingdom. Recommended by research and audit; no evaluation estimates the effect.
- Defence equipment programmes delivered closer to budget and schedule: Direction plausible; size not established. plausible spillover, limited confidence; United Kingdom. Audit and expert recommendations, not an evaluation: no source estimates how much better contract management would reduce overruns, and policy changes cause some of them.
Cost and funding
Cost completeness: Not yet costed. Funding: Not yet costed / funding not identified.
- Commercial staff, contract oversight, transition, maintenance and supplier compliance (administration; paid by central government, councils): Not yet costed. Total procurement spending is not a fund or a savings base; no source estimates savings from better contract management.
- Who pays:
- Contracting authorities’ running budgets (commercial staff and oversight); suppliers bear compliance and reporting costs, partly passed back in prices.
- Financing proposed:
- From named procurement or programme budgets where a business case justifies it. Total procurement spending is a measure of buying, not a spare fund or a proven savings base.
- Gap remaining:
- Unknown: commercial capability has not been costed for any defined set of contracts.
What delivery needs
- Skills:
- Commercial and contract-management professionals; technical specifiers.
- Operational capacity:
- Time for pre-market engagement and in-life management.
- Infrastructure:
- The central digital platform and contract data.
- Permissions:
- None.
- Law:
- Procurement Act 2023 duties already apply.
- Public consent:
- Suppliers willing to bid on outcome terms.
First step and stages
First step: Apply the approach to a defined set of renewing contracts and publish their baseline cost, outcome and milestones. (owner: Cabinet Office with lead departments (MOD for defence))
- Select renewing contracts and publish baselines — Cabinet Office, departments (proposed stage, not an official timetable)
- Design outcomes before tender — Contracting authorities (proposed stage, not an official timetable)
- Report milestones and outcomes through the contract — Contracting authorities; NAO (proposed stage, not an official timetable)
Depends on: Procurement Act reporting data; A42 for innovation trials within the same rules
Trade-offs
- Who gains and who loses:
- Service users gain if delivery improves; incumbent suppliers may lose; small firms gain or lose depending on reporting burden.
- What else the money or effort could do:
- Commercial staff are scarce; deploying them on these contracts leaves others less managed.
- Strongest counterargument:
- Procurement failures often stem from policy changes and unrealistic budgets, which better contract management cannot fix.
- Risks:
- Box-ticking reporting, supplier withdrawal and gaming of outcome measures.
How we would judge it
- Baseline:
- Government major projects rated Red: 34 of 172 rated (NISTA, March 2026).
- Leading indicator:
- Share of renewing contracts with published outcomes, whole-life cost and milestones.
- Outcome:
- Delivery against milestones, change orders, late payment and supplier participation.
- Continue, adapt or stop:
- Expand where contracts meet milestones closer to cost than comparable contracts; drop measures that deter bidders without improving delivery.
Sources
- Institute for Government, The role of procurement in delivering mission-led government, Report PDF pp.4–5, p.19 (2025-09-23; relevant passages checked)
- Royal United Services Institute, Procurement Reform Starts with Requirement Formulation and the Supply Chain, “Defining Procurement Requirements” (2024-07-29; full text checked)
- National Audit Office, The Equipment Plan 2023 to 2033, Summary (2023-12; relevant passages checked)
- National Infrastructure and Service Transformation Authority, NISTA Major Projects Annual Report 2025–26 (ratings at 31 March 2026), Ratings by department (2026-07-13; relevant passages checked)
- Institute for Government, The role of procurement in delivering mission-led government, PDF p.4 (2025-09-23; relevant passages checked)
Source published September 2025 (IfG); July 2024 (RUSI); December 2023 (NAO); July 2026 (NISTA); evidence reviewed 2026-10-04. Reconsider if: First central publication of Procurement Act KPI data; A new NISTA annual report; An evaluation of outcome-based contracts.
Also on: Public procurement, Defence — one shared record, so its cost is counted once.
Action 3A53Policy status: external proposal
Meter homes in water-stressed areas, with a social tariff that protects low-income households
Charging by measured use in areas designated as seriously water stressed lowers household consumption from the day a meter is fitted; a social tariff funded within bills limits the cost to low-income households.
The thread: issue, evidence, action
- Issue Threat (Growth & productivity): Water could limit growth: without action England faces a public water supply deficit of up to 5 billion litres a day by 2055, and in late September 2026 ten of the fourteen Environment Agency areas were in drought, with temporary use (hosepipe) bans affecting around 30 million people. Also: threat (Hampshire), opportunityHow acting here reaches it: Metered charging lowers household demand on the same public supplies whose 2055 deficit the growth page records, so less of the gap has to be met by new reservoirs and transfers.
- Evidence Projected public water supply deficit by 2055, without further action; Reservoir storage, England
- Action A53, this action
Assessment (draft, 6 October review)
This action: Meter water-stressed households with an effective social tariff
Delivery RAG: AmberGate: pending
Range if completed: 18.0–21.0 out of 30 (equal weights; not yet assessed: incremental affordability (Co))
National plan: Resilience and sustainability appraisal queue
- Who decides:
- Defra and the water regulator (Ofwat, until the single regulator in the January 2026 white paper replaces it), with water companies in areas designated as seriously water stressed (England)
- Evidence:
- Experimental or quasi-experimental evaluation. A household panel analysis of England’s first universal metering programme compared consumption before and after meters were fitted, with fixed effects and households not yet switched as a comparison; it is one company, one period and a working paper.
- Expected effect:
- Direction plausible; size not established.
- Cost and funding
Not yet costed
Funding: Not yet costed / funding not identified
Why it is shortlisted here: Water bills are the regulated money on this page with the clearest unmet purpose — the projected supply gap — and metering has UK evidence of cutting use, if low-income households are protected.
What it takes
The problem
England faces a public water supply deficit of up to 5 billion litres a day by 2055, and in September 2026 ten of the fourteen Environment Agency areas were in drought. Cutting demand is expected to close most of the gap, but metering is uneven and, without protection, leaves poorer households worse off.
Who is affected, and where
Households in areas of England designated as seriously water stressed, especially in the South East, East and Midlands, where the framework projects deficits to remain. Territory: England. Water policy is devolved. Wales sets its own metering and charging rules (Welsh Government, with Ofwat’s successor for Welsh companies); Scottish Water is publicly owned and charges through council tax bands; Northern Ireland has no domestic water charges. None was reviewed here.
Policy status
Proposed by researchers or others, not government policy. Builds on announced policy: the January 2026 white paper commits companies to smart meters for 50% of homes and businesses by 2030 and to changes in tariff structures, and companies in seriously water-stressed areas may already meter compulsorily (Southern Water did so in 2010–15). Metering every home in those areas with a protected social tariff is a UK Facts proposal, not government policy.
The evidence
- What the research found:
- Metering cut household water consumption by between 18% and 22% on average, with a similar percentage fall across income groups. Less affluent households were on average around £10 a year worse off, higher-income households gained, and for a large share of households the social cost of a meter exceeded its benefit.
- Evaluated on:
- Households in Southern Water’s Universal Metering Programme (Hampshire, Isle of Wight, Sussex and Kent); South East England, 2010–2015
- Transfer to this case:
- Meters are now smart and tariffs differ by company; the 2010–15 effect is evidence on the mechanism, not a forecast for other areas. The framework’s projection that demand management closes most of the deficit is modelled.
- Our recommendation (separate from the research):
- Meter homes in areas designated as seriously water stressed, starting where deficits are largest, and pair it with a social tariff funded within bills; report consumption per person and the bills of low-income households each year.
- Strongest counter-evidence:
- The same study finds that for a large share of households the social cost of a meter outweighs its benefit, and that less affluent households lose on average; it suggests selective metering of larger households could be more efficient than universal metering.
Cost and funding
Cost completeness: Not yet costed. Funding: Not yet costed / funding not identified.
- Meters, installation and a protected social tariff in seriously water-stressed areas (capital; paid by bill-payers, households): Not yet costed. Not estimated here. The 2010–15 programme’s meter costs are a historical price for one company, not a current cost; the social tariff is a transfer between bill-payers, not public spending.
- Who pays:
- Water bill-payers in the areas metered (meters and installation through company allowances set by the regulator); a social tariff is a cross-subsidy from other bill-payers.
- Financing proposed:
- The 2025–30 regulated programme already funds smart-meter roll-out; any extension would be decided in the regulator’s next price review, not from public spending.
- Gap remaining:
- Unknown: neither the cost of metering every home in the designated areas nor the cost of a protected social tariff has been estimated here.
What delivery needs
- Skills:
- Meter installers and customer-support staff.
- Operational capacity:
- Smart-meter supply and data systems in each company.
- Infrastructure:
- Meters and the data network behind them.
- Permissions:
- Designation of seriously water-stressed areas by the Environment Agency; regulator approval of tariffs.
- Law:
- Compulsory metering is permitted in designated areas under existing law; a mandatory social tariff would need a regulatory or legislative decision.
- Public consent:
- Public acceptance of compulsory meters; protection for large low-income households.
First step and stages
First step: Defra and the regulator set a timetable for metering homes in the designated areas with the largest projected deficits, and the design of a social tariff to protect low-income households, before the next price review. (owner: Defra with the water regulator)
- Set the metering timetable and social-tariff design — Defra and the regulator (proposed stage, not an official timetable)
- Fit meters and switch charging after a grace period — Water companies (proposed stage, not an official timetable)
- Report consumption per person and low-income bills — Water companies; regulator (proposed stage, not an official timetable)
Depends on: Environment Agency designation of seriously water-stressed areas; The single new water regulator and its first price review
Trade-offs
- Who gains and who loses:
- Households that use little water, often smaller and higher-income households, gain; large low-income households can lose without a social tariff, which is why the two are paired.
- What else the money or effort could do:
- Bill-funded money and installer time spent on meters is not available for leakage repair or new supply; a social tariff raises other customers’ bills.
- Strongest counterargument:
- Universal metering may cost society more than it saves for many households; selective metering of high users, or leakage repair, could deliver more water per pound.
- Risks:
- Hardship for large low-income households; consumption falls fading over time; installation delays; public opposition.
How we would judge it
- Baseline:
- Public water supply deficit of up to 5 billion litres a day by 2055 (Environment Agency, England); drought status and temporary use bans in the weekly Environment Agency report.
- Leading indicator:
- Share of homes metered in designated areas; take-up of the social tariff.
- Outcome:
- Household consumption per person in metered areas against unmetered comparison areas; bills of low-income households.
- Continue, adapt or stop:
- Continue where consumption falls without low-income bills rising; switch to selective metering where costs exceed water saved.
Sources
- University of Southampton, Department of Economics (Discussion Paper 1801), The effects of the Universal Metering Programme on water consumption, welfare and equity, Abstract; Section 4 (consumption effects) (2018; full text checked)
- Environment Agency, National Framework for Water Resources 2025: water for growth, nature and a resilient future, Executive summary (Section 6 summary: demand management) (2025-06-17; relevant passages checked)
- Department for Environment, Food & Rural Affairs, A new vision for water (white paper), Water Security chapter, Water Efficiency, PDF p.42 (2026-01-20; full text checked)
- University of Southampton, Department of Economics (Discussion Paper 1801), The effects of the Universal Metering Programme on water consumption, welfare and equity, Abstract; Section 6 (welfare and equity) (2018; full text checked)
Source published 2018 (University of Southampton); 17 June 2025 (Environment Agency framework); 20 January 2026 (white paper); evidence reviewed 2026-10-04. Reconsider if: The regulator’s next price review; An updated water resources framework or regional plans; A new evaluation of smart metering in England.
How the options are assessed
One shared record per option — the same one the national plan reads. Delivery RAG, gate and list membership are separate judgements.
Provisional single-reviewer assessments from the 6 October 2026 review; not approved business cases, and not government policy.
GRP-01Delivery RAG: AmberGate: pending
Deliver what is already funded
A broad priority grouping A23, A20; its scores are its own, never an average of its members.
Provisional single-reviewer assessment; not an approved business case.
- Who and where
- Population not yet defined. Jurisdiction: not defined.
- Result so far
- Range if completed: 14.0–20.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))
- Funded now (baseline)
- Funded baseline not yet stated
- The change assessed (marginal)
- Marginal change not yet defined
- Domain home: Follow the money
- In the national plan: Growth and prosperity list
- Previous version: NP6: Set realistic costs before spending, then manage contracts to the result (4 October 2026 slate, superseded 7 October 2026).
What the evidence supports—and the next decision
Procurement, digital delivery and contract management are distinct interventions. Their possible savings cannot be added without checking overlap.
Codex — AI-assisted analytical follow-up · 8 October 2026. Proposed appraisal design; the attributed scores below are unchanged. No funding or delivery agreement is implied.
- Define the change
- Select a service and contract cohort; separate procurement reform, contract management and digital process changes into costed work packages.
- Test whether it works
- Measure service quality and total unit cost against a documented pre-change baseline and comparison contracts. Verify cash released in accounts separately from staff time freed.
- Establish the cost
- Commercial staff, systems, migration, legal work and transition; reconcile savings to budgets and exclude savings already booked elsewhere.
- Protect against harm
- Protect service continuity, contestability and appeal routes; an apparent saving achieved by restricting access fails the service test.
Read with the outcome evidence and sources in the full assessment. Monitoring proposals are not existing baseline measurements. A numerical benefit or cost score needs evidence for the defined increment, not just the scale of the problem.
Full assessment of Deliver what is already funded: ten criteria, scenarios, delivery, costs and monitoring
The ten criteria (0–3)
Each criterion is scored 0 to 3 by the reviewer. “Not yet assessed” means unknown: it is never counted as zero.
Scale and severity (Sc)2 of 3 — Serious harm to a defined group or widespread moderate harm
Reviewer’s reason: Provisional problem-importance judgement from linked site pages; not the scale of achievable benefit.
Increment beyond baseline (Ad)2 of 3 — Specific material change to existing delivery
Reviewer’s reason: Name contracts, renewal dates and weaknesses; recruit commercial expertise; publish baselines, performance and remedies. A missing rating requires a defined marginal change.
Confidence in the proposed action (Ev)1 of 3 — Indirect, mixed, modelled or weak causal support
Reviewer’s reason: Audits diagnose failures; no general cash saving is established for this proposal.
Expected incremental benefit (Bn)Not yet assessed
Reviewer’s reason: Unknown unless a reasonably defined target-population benefit can be judged; no bonus merely for spanning domains.
Residual harms (Hm)2 of 3 — Manageable harm with specified safeguards
Reviewer’s reason: Legal disputes; supplier exits; pushing costs elsewhere.
Incremental affordability (Co)Not yet assessed
Reviewer’s reason: Commercial staff, data systems, legal work and transition costs; separately verify cashable savings.
Delivery capacity (Ca)1 of 3 — Binding scarce resource
Reviewer’s reason: Name contracts, renewal dates and weaknesses; recruit commercial expertise; publish baselines, performance and remedies.
Distribution (Fa)2 of 3 — Mixed or broadly neutral with safeguards
Reviewer’s reason: Provisional distribution judgement for the stated target; verify who pays, who gains and excluded groups.
Meaningful first outcome (Ti)2 of 3 — More than one and up to three years
Reviewer’s reason: First meaningful outcome, not announcement: Quality-adjusted service delivered, whole-life costs and supplier performance.
Readiness (Rd)2 of 3 — Named commissioning/allocation/coordination step
Reviewer’s reason: Contracting authorities and Cabinet Office; Bounded contract-improvement programme
Four weightings
Normalised as 10 × weighted sum ÷ sum of weights, on a 0–30 scale. Where a criterion is not yet assessed, the range is the lowest and highest result if it were later scored 0 or 3 — not a score, a confidence interval or a rank.
- Equal weights: Range if completed: 14.0–20.0 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
- Evidence doubled: Range if completed: 13.6–19.1 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
- Scale doubled: Range if completed: 14.5–20.0 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
- Cost ignored (the funding gate still applies): Range if completed: 15.6–18.9 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
Funding gate: Not passed — the cost is not yet assessed or no allocation is committed for this scope. Ignoring cost in a weighting never removes the gate.
Delivery RAG and gate
Delivery RAG shown: AmberReview’s claim: Amber. Best the recorded evidence allows: Amber.
Review’s reason: Commercial staff, data systems, legal work and transition costs; separately verify cashable savings.
Why it is not Green yet
- Scope (population, place and increment) not verified against the delivery baseline.
- No verified owner with the powers in place.
- Delivery capacity not verified.
- Lifetime incremental costs not complete.
- No credible funding (a committed allocation for the scope).
- Safeguards not specified.
- Monitoring lacks a metric, a data source or a baseline.
Green needs verified scope, a verified owner with the powers, verified capacity, complete lifetime costs with credible funding, specified safeguards and monitoring with a metric, source and baseline. Amber means appraisal gaps remain; Red means a material delivery obstacle. Red does not mean unimportant.
Gate: Pending — appraisal incomplete (review label: “Pending: incomplete appraisal”).
Why: Scores incomplete; Funding gate not passed (cost unknown or no credible funding).
The gate is separate from national list membership: being listed does not make an option eligible, and an eligible option need not be listed.
Cost and funding
Lifetime costing: Not established. Review: “Full incremental costing not established in reviewed material”.
Still to cost: Commercial staff, data systems, legal work and transition costs; separately verify cashable savings.
Funding status: not established in review.
Owner, powers and capacity
Proposed owner: Contracting authorities and Cabinet Office (proposed, unverified).
Powers: needs a decision or allocation. Capacity: binding constraint.
Powers and capacity read from the review’s Rd and Ca anchors; no proposed owner has agreed to act (the review: “Proposed owners have not agreed to act”).
- England:
- not assessed
- Scotland:
- not assessed
- Wales:
- not assessed
- Northern Ireland:
- not assessed
Not defined in the review.
Dependencies, safeguards and risks
Depends on: None recorded.
Safeguards
None specified yet.
Risks and residual harms: Legal disputes; supplier exits; pushing costs elsewhere.
Monitoring and measured results
Metric: Quality-adjusted service delivered, whole-life costs and supplier performance.
Data source: Not yet named. Baseline: Not yet established.
Measures already on the domain page
- Government major projects rated Red: latest 34 of 172 (ratings at 31 March 2026); baseline not published (United Kingdom).
A page measure is not necessarily the review’s metric; linking the two is an editorial decision still to be made.
Evidence for the outcome
Outcome: Quality-adjusted service delivered, whole-life costs and supplier performance.
Audits diagnose failures; no general cash saving is established for this proposal.
SWOT points it addresses
- Targeting named parts of the gap — including help with record-keeping where error dominates — and publishing outcomes for renewing contracts would turn big theoretical numbers into auditable cash and services.
- 34 of 172 rated government major projects were Red (successful delivery appears unachievable, with major issues that do not appear manageable at that stage), 16 ratings were withheld and 1 project was not yet rated. (Public procurement)
Review record
Assessment version: working-review-2026-10-06 (GRP-01@working-review-2026-10-06).
Reviewer: Author of the review blueprint (single reviewer, not named in uk-facts-complete-plan.json). Reviewed: 6 October 2026.
Scored in the working review of 6 October 2026 on the shared ten-criterion scale (one reviewer); not independently calibrated.
First 90 days (review): Produce a signed scope and current-delivery baseline; Name contracts, renewal dates and weaknesses; recruit commercial expertise; publish baselines, performance and remedies. Obtain incremental costs and an accountable decision before expansion.
Decision route: Bounded contract-improvement programme
An editorial screening framework by one reviewer, not a formal appraisal or business case. Proposed owners have not agreed to act.
A19Delivery RAG: AmberGate: pending
Collect the tax already due
Existing action A19, assessed at the same scope.
Provisional single-reviewer assessment; not an approved business case.
- Who and where
- UK taxpayers in the targeted segment (for example small businesses), and everyone who relies on public services. (from the action record) Jurisdiction: UK.
- Result so far
- Range if completed: 13.0–19.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))
- Funded now (baseline)
- A large package is already funded and running: Autumn Budget 2024 expected £6.5bn a year by 2029–30 from 5,000 extra compliance staff and 1,800 debt-management staff. Later measures raised this: HMRC’s August 2026 update gives £10bn of additional tax revenue a year by 2029–30 and plans for 5,500 new compliance caseworkers (more than 2,400 compliance staff recruited since Autumn Budget 2024). That yield is already in the fiscal forecasts. Any further package beyond it is a UK Facts proposal. (from the action record)
- The change assessed (marginal)
- Marginal change not yet defined
- Domain home: Follow the money
- In the national plan: Equality and opportunity list
What the evidence supports—and the next decision
Compliance yield includes different kinds of revenue protection; it is not all cash collected in the year or a transferable marginal return.
Codex — AI-assisted analytical follow-up · 8 October 2026. Proposed appraisal design; the attributed scores below are unchanged. No funding or delivery agreement is implied.
- Define the change
- Select a tax-risk cohort and additional compliance method beyond existing staffing and digital commitments.
- Test whether it works
- Additional collected receipts net of refunds, appeals and costs over time, with a defensible comparison and separate prevention estimates.
- Establish the cost
- Recruitment, training, systems, litigation and taxpayer burden. Reconcile forecast yield to cash and prevent double counting across tax measures.
- Protect against harm
- Protect proportionality, correct assessments, privacy and accessible appeals.
Read with the outcome evidence and sources in the full assessment. Monitoring proposals are not existing baseline measurements. A numerical benefit or cost score needs evidence for the defined increment, not just the scale of the problem.
Full assessment of Collect the tax already due: ten criteria, scenarios, delivery, costs and monitoring
The ten criteria (0–3)
Each criterion is scored 0 to 3 by the reviewer. “Not yet assessed” means unknown: it is never counted as zero.
Scale and severity (Sc)2 of 3 — Serious harm to a defined group or widespread moderate harm
Reviewer’s reason: Provisional problem-importance judgement from linked site pages; not the scale of achievable benefit.
Increment beyond baseline (Ad)2 of 3 — Specific material change to existing delivery
Reviewer’s reason: Reconcile existing forecast baseline; define cases, staff, legal powers and collection horizon; audit net additional receipts. A missing rating requires a defined marginal change.
Confidence in the proposed action (Ev)1 of 3 — Indirect, mixed, modelled or weak causal support
Reviewer’s reason: Compliance activity can yield revenue; the return from the proposed extra high-wealth focus is not established here.
Expected incremental benefit (Bn)Not yet assessed
Reviewer’s reason: Unknown unless a reasonably defined target-population benefit can be judged; no bonus merely for spanning domains.
Residual harms (Hm)1 of 3 — Material harm/unresolved mitigation
Reviewer’s reason: Due-process burdens; yield lags and double counting existing forecasts.
Incremental affordability (Co)Not yet assessed
Reviewer’s reason: Recruitment/training, systems, litigation, taxpayer compliance and collection costs; gross yield is not net cash.
Delivery capacity (Ca)1 of 3 — Binding scarce resource
Reviewer’s reason: Reconcile existing forecast baseline; define cases, staff, legal powers and collection horizon; audit net additional receipts.
Distribution (Fa)2 of 3 — Mixed or broadly neutral with safeguards
Reviewer’s reason: Provisional distribution judgement for the stated target; verify who pays, who gains and excluded groups.
Meaningful first outcome (Ti)2 of 3 — More than one and up to three years
Reviewer’s reason: First meaningful outcome, not announcement: Collected additional revenue net of costs, error and disputes.
Readiness (Rd)2 of 3 — Named commissioning/allocation/coordination step
Reviewer’s reason: HMRC and Treasury; Cost marginal compliance programme
Four weightings
Normalised as 10 × weighted sum ÷ sum of weights, on a 0–30 scale. Where a criterion is not yet assessed, the range is the lowest and highest result if it were later scored 0 or 3 — not a score, a confidence interval or a rank.
- Equal weights: Range if completed: 13.0–19.0 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
- Evidence doubled: Range if completed: 12.7–18.2 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
- Scale doubled: Range if completed: 13.6–19.1 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
- Cost ignored (the funding gate still applies): Range if completed: 14.4–17.8 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
Funding gate: Not passed — the cost is not yet assessed or no allocation is committed for this scope. Ignoring cost in a weighting never removes the gate.
Delivery RAG and gate
Delivery RAG shown: AmberReview’s claim: Amber. Best the recorded evidence allows: Amber.
Review’s reason: Recruitment/training, systems, litigation, taxpayer compliance and collection costs; gross yield is not net cash.
Why it is not Green yet
- Scope (population, place and increment) not verified against the delivery baseline.
- No verified owner with the powers in place.
- Delivery capacity not verified.
- Lifetime incremental costs not complete.
- No credible funding (a committed allocation for the scope).
- Safeguards not specified.
- Monitoring lacks a metric, a data source or a baseline.
Green needs verified scope, a verified owner with the powers, verified capacity, complete lifetime costs with credible funding, specified safeguards and monitoring with a metric, source and baseline. Amber means appraisal gaps remain; Red means a material delivery obstacle. Red does not mean unimportant.
Gate: Pending — appraisal incomplete (review label: “Pending: incomplete appraisal”).
Why: Scores incomplete; Funding gate not passed (cost unknown or no credible funding).
The gate is separate from national list membership: being listed does not make an option eligible, and an eligible option need not be listed.
Cost and funding
Lifetime costing: Not established. Review: “Full incremental costing not established in reviewed material”.
- HMRC staff, training, systems, appeals and overheads for a further compliance package (not costed; C-A19-PACKAGE)
Still to cost: Recruitment/training, systems, litigation, taxpayer compliance and collection costs; gross yield is not net cash.
Funding status: not identified.
Owner, powers and capacity
Proposed owner: HMRC and Treasury (proposed, unverified).
Powers: needs a decision or allocation. Capacity: binding constraint.
Powers and capacity read from the review’s Rd and Ca anchors; no proposed owner has agreed to act (the review: “Proposed owners have not agreed to act”).
- England:
- HMRC and HM Treasury; Parliament for new powers; the OBR certifies costings (action record)
- Scotland:
- HMRC and HM Treasury; Parliament for new powers; the OBR certifies costings (action record)
- Wales:
- HMRC and HM Treasury; Parliament for new powers; the OBR certifies costings (action record)
- Northern Ireland:
- HMRC and HM Treasury; Parliament for new powers; the OBR certifies costings (action record)
HMRC administers UK taxes; Scottish and Welsh income tax and devolved taxes (Revenue Scotland, Welsh Revenue Authority) need their own arrangements, not assessed here.
Dependencies, safeguards and risks
Depends on: None recorded.
Safeguards
None specified yet.
Risks and residual harms: Due-process burdens; yield lags and double counting existing forecasts.
Monitoring and measured results
Metric: Collected additional revenue net of costs, error and disputes.
Data source: Not yet named. Baseline: Not yet established.
Measures already on the domain page
- Tax gap, share of tax due: latest 6.4% (tax year 2024–25 (projection, revised in later editions)); baseline not published (United Kingdom).
A page measure is not necessarily the review’s metric; linking the two is an editorial decision still to be made.
Evidence for the outcome
Outcome: Collected additional revenue net of costs, error and disputes.
Compliance activity can yield revenue; the return from the proposed extra high-wealth focus is not established here.
Effect records for this action
- Net tax receipts beyond forecast: size not established (plausible spillover, limited confidence; United Kingdom)
- Costs to compliant taxpayers wrongly challenged: size not established (plausible spillover, limited confidence; United Kingdom)
SWOT points it addresses
- The estimated tax gap was £59.2bn (6.4% of tax due). £20.8bn came from failure to take reasonable care and £9.3bn from error; £36.7bn arose among small businesses.
- HMRC publishes an annual tax-gap estimate broken down by tax, customer group and behaviour, with an uncertainty rating for each part.
- Average returns overstate what more staff would bring: HMRC could not tell the NAO the marginal return to further investment, and in its large-business directorate — the only unit the audit covers — returns fall from about £95 to about £58 per £1 once overheads are counted.
Review record
Assessment version: working-review-2026-10-06 (A19@working-review-2026-10-06).
Reviewer: Author of the review blueprint (single reviewer, not named in uk-facts-complete-plan.json). Reviewed: 6 October 2026.
Scored in the working review of 6 October 2026 on the shared ten-criterion scale (one reviewer); not independently calibrated.
First 90 days (review): Produce a signed scope and current-delivery baseline; Reconcile existing forecast baseline; define cases, staff, legal powers and collection horizon; audit net additional receipts. Obtain incremental costs and an accountable decision before expansion.
Decision route: Cost marginal compliance programme
An editorial screening framework by one reviewer, not a formal appraisal or business case. Proposed owners have not agreed to act.
A53Delivery RAG: AmberGate: pending
Meter water-stressed households with an effective social tariff
Existing action A53, assessed at the same scope.
Provisional single-reviewer desk assessment, 6 October 2026.
- Who and where
- Households in areas of England designated as seriously water stressed, especially in the South East, East and Midlands, where the framework projects deficits to remain. (from the action record) Jurisdiction: England.
- Result so far
- Range if completed: 18.0–21.0 out of 30 (equal weights; not yet assessed: incremental affordability (Co))
- Funded now (baseline)
- Builds on announced policy: the January 2026 white paper commits companies to smart meters for 50% of homes and businesses by 2030 and to changes in tariff structures, and companies in seriously water-stressed areas may already meter compulsorily (Southern Water did so in 2010–15). Metering every home in those areas with a protected social tariff is a UK Facts proposal, not government policy. (from the action record)
- The change assessed (marginal)
- Target a defined unmetered cohort in designated stressed areas; protect affordability and distinguish use from leakage. (from the 6 October review)
- Domain home: Follow the money
- In the national plan: Resilience and sustainability appraisal queue
What the evidence supports—and the next decision
Metering evidence from one company is not a national effect estimate. Affordability protection changes both costs and distribution.
Codex — AI-assisted analytical follow-up · 8 October 2026. Proposed appraisal design; the attributed scores below are unchanged. No funding or delivery agreement is implied.
- Define the change
- Define an unmetered cohort in a water-stressed area and a funded social-tariff design beyond scheduled rollout.
- Test whether it works
- Weather-adjusted household consumption, bills and hardship with a comparison design; distinguish customer use from network leakage.
- Establish the cost
- Meters, installation, maintenance, billing, administration and tariff support; show who funds cross-subsidy.
- Protect against harm
- Protect essential medical use, large low-income families and people who cannot readily reduce consumption.
Read with the outcome evidence and sources in the full assessment. Monitoring proposals are not existing baseline measurements. A numerical benefit or cost score needs evidence for the defined increment, not just the scale of the problem.
Full assessment of Meter water-stressed households with an effective social tariff: ten criteria, scenarios, delivery, costs and monitoring
The ten criteria (0–3)
Each criterion is scored 0 to 3 by the reviewer. “Not yet assessed” means unknown: it is never counted as zero.
Scale and severity (Sc)2 of 3 — Serious harm to a defined group or widespread moderate harm
Reviewer’s reason: Problem scale judged from the linked domain evidence; not a population estimate of those helped.
Increment beyond baseline (Ad)2 of 3 — Specific material change to existing delivery
Reviewer’s reason: Target a defined unmetered cohort in designated stressed areas; protect affordability and distinguish use from leakage. This is a provisional marginal-change judgement, to confirm against commissioned delivery.
Confidence in the proposed action (Ev)2 of 3 — Relevant evaluated evidence with limitations
Reviewer’s reason: English household-panel evidence supports lower consumption after metering; the proposed tariff package is not separately evaluated.
Expected incremental benefit (Bn)2 of 3 — Material for the target population
Reviewer’s reason: Magnitude judgement for the defined target group, not a quantified national effect. Target a defined unmetered cohort in designated stressed areas; protect affordability and distinguish use from leakage.
Residual harms (Hm)1 of 3 — Material harm/unresolved mitigation
Reviewer’s reason: Large low-income or medically vulnerable households can lose without protection; savings are not all new water supply.
Incremental affordability (Co)Not yet assessed
Reviewer’s reason: Unknown: the proposed increment has not been costed and matched to an approved affordable allocation in this review. Existing programme envelopes are not that allocation.
Delivery capacity (Ca)2 of 3 — Stretched but plausibly obtainable
Reviewer’s reason: Require a funded protection design and additional rollout baseline; do not automatically generalise one company estimate.
Distribution (Fa)2 of 3 — Mixed or broadly neutral with safeguards
Reviewer’s reason: Distribution assessed against the target group and the burdens described here: Large low-income or medically vulnerable households can lose without protection; savings are not all new water supply.
Meaningful first outcome (Ti)3 of 3 — Within one year
Reviewer’s reason: Timing judgement concerns the first meaningful outcome in: Litres per person/day, arrears and essential-use hardship over 12–24 months; tariff take-up. It does not imply all long-term benefits arrive then.
Readiness (Rd)2 of 3 — Named commissioning/allocation/coordination step
Reviewer’s reason: Compare the extra cohort with the committed rollout; cost meters and tariff protection before proceeding. Owner: Water companies, regulator and government within relevant English powers.
Four weightings
Normalised as 10 × weighted sum ÷ sum of weights, on a 0–30 scale. Where a criterion is not yet assessed, the range is the lowest and highest result if it were later scored 0 or 3 — not a score, a confidence interval or a rank.
- Equal weights: Range if completed: 18.0–21.0 out of 30. Not yet assessed: incremental affordability (Co). Funding gate: not passed.
- Evidence doubled: Range if completed: 18.2–20.9 out of 30. Not yet assessed: incremental affordability (Co). Funding gate: not passed.
- Scale doubled: Range if completed: 18.2–20.9 out of 30. Not yet assessed: incremental affordability (Co). Funding gate: not passed.
- Cost ignored (the funding gate still applies): Range if completed: 20.0–20.0 out of 30. Not yet assessed: incremental affordability (Co). The missing criteria carry no weight here, so the ends meet; the record is still incomplete. Funding gate: not passed.
Funding gate: Not passed — the cost is not yet assessed or no allocation is committed for this scope. Ignoring cost in a weighting never removes the gate.
Delivery RAG and gate
Delivery RAG shown: AmberReview’s claim: Amber. Best the recorded evidence allows: Amber.
Review’s reason: Incremental lifetime costs and funding not established. Require a funded protection design and additional rollout baseline; do not automatically generalise one company estimate.
Why it is not Green yet
- Scope (population, place and increment) not verified against the delivery baseline.
- No verified owner with the powers in place.
- Delivery capacity not verified.
- Lifetime incremental costs not complete.
- No credible funding (a committed allocation for the scope).
- Safeguards not specified.
- Monitoring lacks a metric, a data source or a baseline.
Green needs verified scope, a verified owner with the powers, verified capacity, complete lifetime costs with credible funding, specified safeguards and monitoring with a metric, source and baseline. Amber means appraisal gaps remain; Red means a material delivery obstacle. Red does not mean unimportant.
Gate: Pending — appraisal incomplete (review label: “Pending cost, funding, scope and capacity appraisal”).
Why: Scores incomplete; Funding gate not passed (cost unknown or no credible funding).
The gate is separate from national list membership: being listed does not make an option eligible, and an eligible option need not be listed.
Cost and funding
Lifetime costing: Not established.
- Meters, installation and a protected social tariff in seriously water-stressed areas (not costed; C-A53-METERING)
Still to cost: Incremental lifetime costs and funding not established. Require a funded protection design and additional rollout baseline; do not automatically generalise one company estimate.
Funding status: not identified.
Owner, powers and capacity
Proposed owner: Water companies, regulator and government within relevant English powers. (proposed, unverified).
Powers: needs a decision or allocation. Capacity: unverified.
Powers and capacity read from the review’s Rd and Ca anchors; no proposed owner has agreed to act (the review: “Proposed owners have not agreed to act”).
- England:
- Defra and the water regulator (Ofwat, until the single regulator in the January 2026 white paper replaces it), with water companies in areas designated as seriously water stressed (action record)
- Scotland:
- not assessed
- Wales:
- not assessed
- Northern Ireland:
- not assessed
Water policy is devolved. Wales sets its own metering and charging rules (Welsh Government, with Ofwat’s successor for Welsh companies); Scottish Water is publicly owned and charges through council tax bands; Northern Ireland has no domestic water charges. None was reviewed here.
Dependencies, safeguards and risks
Depends on: Require a funded protection design and additional rollout baseline; do not automatically generalise one company estimate.
Safeguards
- cost meters and tariff protection before proceeding (proposed, not yet specified)
- Require a funded protection design and additional rollout baseline (proposed, not yet specified)
- protect affordability and distinguish use from leakage (proposed, not yet specified)
Risks and residual harms: Large low-income or medically vulnerable households can lose without protection; savings are not all new water supply.
Monitoring and measured results
Metric: Litres per person/day, arrears and essential-use hardship over 12–24 months; tariff take-up.
Data source: Not yet named. Baseline: Not yet established.
Measures already on the domain page
- Projected public water supply deficit by 2055, without further action: latest up to 5 (National Framework for Water Resources, June 2025); baseline not published (England).
- Reservoir storage, England: latest 56.4% (week of 18–24 September 2026); baseline not published (England).
A page measure is not necessarily the review’s metric; linking the two is an editorial decision still to be made.
Evidence for the outcome
Outcome: Litres per person/day, arrears and essential-use hardship over 12–24 months; tariff take-up.
English household-panel evidence supports lower consumption after metering; the proposed tariff package is not separately evaluated.
Sources: southampton.ac.uk (P-SOTON-UMP-2018)
SWOT points it addresses
- Water bill-payers are funding a £104bn upgrade of the water sector in 2025–30, including nine new reservoirs and £700m to cut leakage; steering that money, and how water is charged, at the projected supply gap could close more of it for each pound billed.
- Water could limit growth: without action England faces a public water supply deficit of up to 5 billion litres a day by 2055, and in late September 2026 ten of the fourteen Environment Agency areas were in drought, with temporary use (hosepipe) bans affecting around 30 million people. (Growth & productivity)
- Water and the sea are local risks now: in late September 2026 Southern Water was at drought level 1 in its Hampshire and Isle of Wight supply zones with temporary use bans in force, and in Portsmouth 8,077 homes and 704 commercial properties in Southsea are at risk from coastal flooding, which a coastal scheme funded in 2020 is being built to reduce. (Hampshire)
Review record
Assessment version: working-review-2026-10-06 (A53@working-review-2026-10-06).
Reviewer: Author of the review blueprint (single reviewer, not named in uk-facts-complete-plan.json). Reviewed: 6 October 2026.
Carried from the earlier domain review (C record): must be calibrated jointly with the G/W/E/NG/NW/NE records before any combined comparison.
Decision route: Compare the extra cohort with the committed rollout; cost meters and tariff protection before proceeding.
An earlier assessment exists on the 4 October 2026 selection table (nine H/M/L bands; superseded 7 October 2026). Its bands are kept, not converted into these scores.
An editorial screening framework by one reviewer, not a formal appraisal or business case. Proposed owners have not agreed to act.
Decision briefs
The leading option set out as a decision someone could take: who decides, who benefits, the best evidence, cost and funding, and the main trade-off. The full research record is one click away.
Decision briefPublic-policy proposalReviewed 2026-10-04
Test what extra tax checks on small businesses actually collect before paying for more of them
The thread: issue, evidence, action
- Issue Weakness: The estimated tax gap was £59.2bn (6.4% of tax due). £20.8bn came from failure to take reasonable care and £9.3bn from error; £36.7bn arose among small businesses. Also: threat, strength
- Evidence Tax gap, share of tax due
- Action Collect more tax through specific, auditable compliance work
- Decision required
- HMRC runs a randomised trial of warning letters and targeted checks in one small-business segment where income is self-reported, and publishes the extra cash collected against a control group — before money is committed to, or revenue scored for, any compliance package beyond the 2024 one.
- Who and where
- Small businesses filing self-assessment or company returns in the chosen segment, and everyone who relies on public services. Applies in: UK.
- Accountable body
- HM Revenue & Customs, with HM Treasury
- Intervention
- Randomly send warning letters or open checks for one small-business segment, with a control group.
- Best evidence, and where it applies
- A randomised audit experiment in Denmark found evasion of 0.3% on income reported by third parties but 37% on self-reported income, and that warning letters changed what people reported.Studied in: About 42,800 Danish taxpayers (Audits of 2006 income; letters in 2008).How closely the comparison transfers to this decision: Denmark — partial.
- Extra cost of this change
- Capital: none identified in the brief.Recurring: none identified in the brief.One-off or mixed: Staff, letters, checks, appeals and overheads for the trial and any further package — Not yet costed; Independent evaluation — not yet established.
- Funding
- Not funded: no funding route identified yet.Committed to this change: none.Possible source, not an award: none identified.Unfunded: Trial cost not yet estimated; any scaled package would need its own funding decision and an OBR-certified costing.
- Savings and wider benefits
- Not yet specified: no cashable saving or avoided cost has been costed for this change. Expected outcomes are listed one by one in the research appendix and are never added together or counted as money available.
- First 90-day step
- HMRC publishes the segment, the forecast assumption for it, the randomisation design and the outcome measure (cash beyond forecast)The proposed first milestone; a 90-day date is not yet specified. Owner: HMRC. Proposed by UK Facts, not an official deadline.
- Twelve-month milestone
- Not yet specified.Time to a first useful result: Letter effects within one filing cycle; enquiry outcomes and cash over two to three years.
- Outcome, and when to scale or stop
- Measure: Change in reported income and tax due after letters, against control.Scale if: Cash beyond the forecast, net of the trial’s full cost including overheads, is clearly positive and wrongful challenges are not rising.Stop if: Cash collected falls well short of the costing, or upheld appeals and complaints rise.
- Main trade-off
- Compliance staff on checks are not answering taxpayers’ queries, and honest firms that are checked bear real costs; the extra yield to more enforcement is not known.
- Source and review date
- Unwilling or Unable to Cheat? Evidence from a Tax Audit Experiment in Denmark (NBER Working Paper 15769; published in Econometrica 79(3), 2011) (2010 (working paper); 2011 (Econometrica)); Taxing large businesses (HC 1647, Session 2024–26) (27 February 2026). Reviewed 2026-10-04.
An editorial proposal by UK Facts for discussion, not government policy. Records: A19 · effects E-A19-RECEIPTS, E-A19-TAXPAYERS · costs C-A19-PACKAGE
Research appendix: study design, effect sizes and limits, alternatives, full costing, international comparisons and how we would know
1.The change, in plain words
Test what extra tax checks on small businesses actually collect before paying for more of them
2.The decision requested
- Decision
- Commission a randomised trial in one named small-business segment (for example self-assessment trading income where the 2026 tax-gap estimates show failure to take reasonable care), fund it from HMRC’s existing compliance budget, and require cash collected beyond the forecast — not “yield protected” — as the test for scaling.
- Accountable institution
- HM Revenue & Customs, with HM Treasury
- Geography
- UK
- Powers
- Existing HMRC compliance and information powers; no new legislation for letters and enquiries. Scotland and Wales income tax rates differ but HMRC administers them.
- Delivery partners
- HM Treasury; Office for Budget Responsibility (certification of any scaled costing); Tax agents and representative bodies (guidance and burden); Independent evaluator
3.Who it is for, and what changes beyond today
- Target population
- Small businesses filing self-assessment or company returns in the chosen segment, and everyone who relies on public services.
- Eligibility
- One segment where income is mainly self-reported and the tax-gap estimates attribute most of the gap to error or failure to take reasonable care; randomised between letter, check and control groups.
- Scale
- A trial sized by HMRC for statistical power within existing compliance capacity; not a national roll-out.
- Baseline
- Tax gap £59.2bn (6.4% of liabilities) in 2024–25; small businesses £36.7bn of it; by behaviour, failure to take reasonable care £20.8bn and error £9.3bn, evasion £7.1bn. The Autumn Budget 2024 package — £1.4bn over five years for 5,000 compliance staff and £262m for 1,800 debt staff — is expected to raise £6.5bn a year by 2029–30 and is already in the forecasts.
Source: HM Revenue and Customs, Measuring tax gaps 2026 edition: tax gap estimates for 2024 to 2025 (Tables 1.3 and 7.1); HM Treasury, Autumn Budget 2024 (HC 295), print version (Paragraphs 2.16–2.17, 5.11–5.13)
- Change beyond existing law or funding
- HMRC already runs compliance work and the 2024 package is funded and scored. The change is a controlled trial that measures cash collected beyond what the forecast assumes, before any further package is costed — so the same revenue is not counted twice.
4.How it would work
Do: Randomly send warning letters or open checks for one small-business segment, with a control group Changing: so that reported income rises where it is under-reported, and the extra cash can be measured against the forecast
Net tax receipts beyond the forecast from the segment
Hypothesis to testEffect record E-A19-RECEIPTS
HMRC could not tell the NAO the marginal return to further investment; the trial measures it.
Costs to compliant taxpayers wrongly challenged
Hypothesis to testEffect record E-A19-TAXPAYERS
Measured through enquiries closed with no change, appeals upheld and complaints.
Outcomes are kept separate and never added into one impact figure.
5.Best evidence
- Author or institution:
- Kleven, Knudsen, Kreiner, Pedersen and Saez (university economists, with the Danish tax administration)
- Published:
- 2010 (working paper); 2011 (Econometrica)
- Evaluation period:
- Audits of 2006 income; letters in 2008
- Design:
- Randomised field experiment
- Sample or population:
- About 42,800 Danish taxpayers
- Effect and uncertainty:
- Evasion 0.3% on third-party-reported income versus 37% on self-reported income; a prior audit raised next-year reported income by about 45% of the audit adjustment; letters raised the share adjusting income by 1.65 points from 13.37%.
- Limits:
- Danish individuals, not UK small businesses or VAT; short-run effects; extensive third-party reporting in Denmark.
Where: Abstract; pp.2–3, 28–31. Affiliation is provenance, not proof of quality.
Taxing large businesses (HC 1647, Session 2024–26)
- Author or institution:
- National Audit Office
- Published:
- 27 February 2026
- Evaluation period:
- 2017–18 to 2024–25
- Design:
- Audit of HMRC’s large business directorate
- Sample or population:
- About 2,000 large business groups
- Effect and uncertainty:
- Compliance yield of £15.8bn in 2024–25 is revenue “collected or protected”, not cash; about £95 per £1 of staff pay but about £58 per £1 with overheads; HMRC could not say what marginal return further investment would bring.
- Limits:
- Large businesses only; average returns are not marginal returns.
Where: Paragraphs 1.12 and 3.6. Affiliation is provenance, not proof of quality.
6.Alternatives, counter-evidence and who loses
- Closest feasible alternative
- Simplify rules and improve guidance and digital records for small firms (error and failure to take reasonable care are over half the gap), rather than more enforcement.
- Strongest counter-evidence
- Returns diminish as easier cases are worked; much “yield” is revenue protected that never arrives as cash; wrongly challenged taxpayers bear real costs.
Source: National Audit Office, Taxing large businesses (HC 1647, Session 2024–26) (Paragraph 3.6)
- Distributional effects
- Falls on non-compliant small businesses; compliant competitors gain; small firms checked in error bear time and adviser costs.
- Main downside
- A trial delays scaling by at least a filing cycle, and a weak result could be read as “compliance doesn’t pay” when it shows only this segment’s return.
| Option | Who is reached | Evidence | Likely outcome and timing | Cost and funding | Main trade-off |
|---|---|---|---|---|---|
| The proposalRandomised letter-and-check trial in one small-business segment, then scale only on cash beyond forecast | One segment of small businesses | Danish randomised experiment; NAO on marginal returns | Letter effects within a year; cash over two to three years | Not yet costed; HMRC compliance budget | Slower than funding staff now |
| Current policyCurrent policy: the funded Autumn Budget 2024 package (5,000 compliance and 1,800 debt staff) | All segments HMRC targets | Scored by the OBR; returns not yet measured | £6.5bn a year by 2029–30 (already in forecasts) | £1.4bn and £262m over five years, plus £154m for systems; funded | Marginal return unknown; cannot be counted again |
| AlternativeFund a further compliance package now on average-return assumptions | Taxpayers HMRC selects | Average returns overstate marginal returns (NAO) | Uncertain; staff take time to become productive | Would need new funding | Risk of scoring revenue that never arrives |
| AlternativeSimplify rules and support record-keeping for small firms | Small businesses making errors | Error and failure to take reasonable care are over half the gap | Slow; effect size unknown | Not costed | Does not deter deliberate under-reporting |
The options compared, including current policy
The proposal
Randomised letter-and-check trial in one small-business segment, then scale only on cash beyond forecast
- Who is reached
- One segment of small businesses
- Evidence
- Danish randomised experiment; NAO on marginal returns
- Likely outcome and timing
- Letter effects within a year; cash over two to three years
- Cost and funding
- Not yet costed; HMRC compliance budget
- Main trade-off
- Slower than funding staff now
Current policy
Current policy: the funded Autumn Budget 2024 package (5,000 compliance and 1,800 debt staff)
- Who is reached
- All segments HMRC targets
- Evidence
- Scored by the OBR; returns not yet measured
- Likely outcome and timing
- £6.5bn a year by 2029–30 (already in forecasts)
- Cost and funding
- £1.4bn and £262m over five years, plus £154m for systems; funded
- Main trade-off
- Marginal return unknown; cannot be counted again
Alternative
Fund a further compliance package now on average-return assumptions
- Who is reached
- Taxpayers HMRC selects
- Evidence
- Average returns overstate marginal returns (NAO)
- Likely outcome and timing
- Uncertain; staff take time to become productive
- Cost and funding
- Would need new funding
- Main trade-off
- Risk of scoring revenue that never arrives
Alternative
Simplify rules and support record-keeping for small firms
- Who is reached
- Small businesses making errors
- Evidence
- Error and failure to take reasonable care are over half the gap
- Likely outcome and timing
- Slow; effect size unknown
- Cost and funding
- Not costed
- Main trade-off
- Does not deter deliberate under-reporting
7.What other countries or the devolved nations show
Country lesson · Denmark, Audits of 2006 income (2007); warning letters in 2008
Random tax audits and warning letters in Denmark
Evidence: Experimental or quasi-experimental evaluationPartial match: some conditions differ
- What was changed
- The Danish tax authority randomly audited half of a sample of about 42,800 taxpayers in full, and the next year sent randomly assigned letters warning that returns had a 100% or 50% chance of audit.
- Study design and population
- Randomised field experiment About 42,800 Danish individual taxpayers (25,020 employees, 17,764 self-employed)
- Measured outcome there
- Detected evasion was 0.3% of income reported by third parties (employers, banks) but 37% of self-reported income. A prior audit raised next-year reported income by about 45% of the audit adjustment; warning letters raised the share adjusting their reported income by 1.65 points from 13.37%.
- Cost status
- Audit costs per case not reported in the paper; the yield of a national programme was not estimated.
- What failed or remains uncertain
- Letter effects were measured over one year only; where income is third-party reported, audits found almost nothing, so extra audits there add cost without yield.
- Why the UK differs
- The UK’s tax gap is dominated by small businesses (£36.7bn of £59.2bn in 2024–25) and by failure to take reasonable care and error rather than evasion; Danish third-party reporting is more extensive; the experiment measured individuals, not companies or VAT.
- First change required here
- Before funding more staff, HMRC randomises a letter-and-audit trial in one small-business segment with self-reported income and publishes cash collected beyond the forecast against a control group.
Not a UK forecast: the effect above was measured in that place and population. Source: National Bureau of Economic Research, Unwilling or Unable to Cheat? Evidence from a Tax Audit Experiment in Denmark (NBER Working Paper 15769; published in Econometrica 79(3), 2011) (Abstract; pp.2–3, 28–31). Reviewed 2026-10-04.
8.What delivery needs first
- staff — Trained compliance staff, who take time to become productive; the 2024 recruitment is still being absorbed. (Scarce resource shared with other priorities; owner: HMRC)
- data — A segment definition and a forecast baseline for it, so cash beyond forecast can be identified. (Requirement; owner: HMRC with the OBR)
- law — A lawful basis, ethics review and taxpayer safeguards for randomising letters and enquiries. (Requirement; owner: HMRC)
9.What it would cost
How the cost is built up: Letters + checks (staff time including overheads) + appeals + evaluation; benefit counted only as cash collected beyond the forecast, net of repayments, never as “yield protected”.
| Component | Unit and quantity | Unit cost or amount | Type, price year, period | Status |
|---|---|---|---|---|
| Staff, letters, checks, appeals and overheads for the trial and any further packageOne small-business segment beyond the Autumn Budget 2024 package | trial; quantity to be set from need and capacity | Not yet costed (ledger C-A19-PACKAGE) | one-off revenue; price year not stated; One filing cycle plus follow-up | Not yet established |
| Independent evaluationDesign, analysis and publication | one evaluation; quantity to be set from need and capacity | Not yet established | one-off revenue; price year not stated; Trial period | Not yet established |
Staff, letters, checks, appeals and overheads for the trial and any further package
One small-business segment beyond the Autumn Budget 2024 package
Not yet costed (ledger C-A19-PACKAGE)
one-off revenue; price year not stated; One filing cycle plus follow-up; Not yet established
Independent evaluation
Design, analysis and publication
Not yet established one evaluation
one-off revenue; price year not stated; Trial period; Not yet established
10.Who pays, and what is missing
- Programme envelope (a possible route, not an award)
- None identified
- Allocation committed to this change
- None
- Remaining gap
- Trial cost not yet estimated; any scaled package would need its own funding decision and an OBR-certified costing.
- Proposed financing
- HMRC’s existing compliance budget for the trial. The £6.5bn a year from the 2024 package is already counted in the forecasts and cannot pay for anything new.
- Responsible payer
- central government
- Budget displaced
- Other HMRC compliance or customer-service work during the trial.
11.First milestone and time to a useful result
HMRC publishes the segment, the forecast assumption for it, the randomisation design and the outcome measure (cash beyond forecast) (Owner: HMRC. Proposed by UK Facts, not an official deadline.)
Time to first useful result: Letter effects within one filing cycle; enquiry outcomes and cash over two to three years.
What could delay it: Compliance staff are committed to the 2024 package Disputes take years to settle, delaying cash results
12.How we would know
- Baseline
- Tax gap estimate for the chosen segment (2024–25) and the forecast cash from it.
- Comparison
- Randomised control group in the same segment.
- Leading indicator
- Change in reported income and tax due after letters, against control.
- Follow-up
- Cash collected at one, two and three years, net of repayments; enquiries closed with no change; appeals upheld.
- Continue if
- Cash beyond the forecast, net of the trial’s full cost including overheads, is clearly positive and wrongful challenges are not rising.
- Adapt if
- Letters work but checks do not (or the reverse): scale the cheaper element only.
- Stop if
- Cash collected falls well short of the costing, or upheld appeals and complaints rise.
- Thresholds
- Not yet set: A minimum detectable effect and a cost-recovery threshold should be set in the trial protocol from HMRC’s segment data before launch.
What is not yet known, and how to find out
- What the trial costs, including overheads and appeals (cost)Next step: HMRC to cost the protocol from its unit costs for letters and enquiries.Scope: One segment, one filing cycle plus follow-up · Data or quotes needed: Staff time per letter and per enquiry; overhead rates; appeal rates · Who can estimate it: HMRC
- The marginal cash return to extra compliance work in small businesses (effect)Next step: Run the randomised trial described here.Defensible route: bounded pilot
- How much the tax-gap estimate for the segment overlaps what the forecast already assumes (data)Next step: HMRC and the OBR to publish the forecast assumption for the segment before the trial.
Sources last checked 4 October 2026 · Owner: Evidence editor (James Harris) · Next check: the first trigger: HMRC measuring tax gaps (annual).
Decision briefPublic-policy proposalReviewed 2026-10-04
Follow the asylum accommodation money, then decide the 2029 renewal on cost per suitable night and outcomes
The thread: issue, evidence, action
- Issue Weakness (Public procurement): 34 of 172 rated government major projects were Red (successful delivery appears unachievable, with major issues that do not appear manageable at that stage), 16 ratings were withheld and 1 project was not yet rated. Also: opportunityHow acting here reaches it: Buying measurable results and managing contracts through delivery is meant to bring more major projects out of Red, the ratings the procurement page records for public money spent through contracts.
- Evidence Government major projects rated Red
- Action Buy measurable results and manage contracts through delivery
- Decision required
- The Home Office publishes the money chain for its asylum accommodation contracts — budget, providers, hotels versus dispersed housing, cost and standards — and decides what replaces the contracts ending in August 2029 by comparing an outcome-based re-let with council or public delivery on whole-life cost.
- Who and where
- People seeking asylum who are accommodated by the Home Office, and the communities where they are housed. Applies in: UK.
- Accountable body
- Home Office
- Intervention
- Publish the chain from budget to provider to type of accommodation, and compare replacement models on cost per suitable night and outcomes.
- Best evidence, and where it applies
- The NAO found the 10-year contract estimate rose from £4.5bn to £15.3bn, hotels held about 35% of people but 76% of cost, and the nine KPIs had not been revised since the contracts began.Studied in: Home Office asylum accommodation contracts (2019 to January 2025).How closely the comparison transfers to this decision: England and Wales (within-UK case) — partial.
- Extra cost of this change
- Capital: none identified in the brief.Recurring: Current contracts, estimated whole-term cost (historic estimate, for context) — £15,300,000,000 contract set.One-off or mixed: Commercial staff, contract oversight, transition and supplier compliance for the renewal — Not yet costed.
- Funding
- Not funded yet: a possible funding route exists, but nothing is allocated to this change.Committed to this change: none.Possible source, not an award: none identified.Unfunded: The transition cost of any council or public model is not established.
- Savings and wider benefits
- Not yet specified: no cashable saving or avoided cost has been costed for this change. Expected outcomes are listed one by one in the research appendix and are never added together or counted as money available.
- First 90-day step
- The Home Office publishes the first annual money chain (spend by provider and accommodation type, cost per night, KPI results) and its options appraisal scope for the 2029 replacementThe proposed first milestone; a 90-day date is not yet specified. Owner: Home Office. Proposed by UK Facts, not an official deadline.
- Twelve-month milestone
- Not yet specified.Time to a first useful result: The first chain within a year; the renewal decision before the replacement procurement begins.
- Outcome, and when to scale or stop
- Measure: Hotel share of people and of cost, published annually.Scale if: Published costs per suitable night fall and standards and move-on improve.Stop if: A model cannot provide enough suitable places without hotels — then keep a re-let with revised measures.
- Main trade-off
- A council or public model could cut hotel use but needs housing and staff that do not yet exist; a re-let keeps capacity but repeats the incentives that produced hotel dependence.
- Source and review date
- The Home Office’s asylum accommodation contracts (HC 874) (7 May 2025). Reviewed 2026-10-04.
An editorial proposal by UK Facts for discussion, not government policy. Records: A23 · effects E-A23-SERVICE · costs C-A23-CAPABILITY
Research appendix: study design, effect sizes and limits, alternatives, full costing, international comparisons and how we would know
1.The change, in plain words
Follow the asylum accommodation money, then decide the 2029 renewal on cost per suitable night and outcomes
2.The decision requested
- Decision
- Publish an annual money chain for the asylum accommodation contracts and, before the replacement procurement passes its Strategic Outline Case, apply the public interest test (in force from April 2027) and compare an outcome-based re-let with council-led and public delivery on cost per suitable night, standards and move-on.
- Accountable institution
- Home Office
- Geography
- UK
- Powers
- The Home Office’s statutory asylum-support duty and its contract-management powers; the Procurement Act 2023 for the replacement; PPN 024 for the public interest test.
- Delivery partners
- Cabinet Office (Government Commercial Function); HM Treasury; Councils and devolved governments; Current providers (Clearsprings, Mears, Serco); National Audit Office
3.Who it is for, and what changes beyond today
- Target population
- People seeking asylum who are accommodated by the Home Office, and the communities where they are housed.
- Eligibility
- The seven regional Asylum Accommodation and Support Contracts (January 2019 to 31 August 2029) and their replacement.
- Scale
- The whole contract set: £15.3bn estimated over ten years.
- Baseline
- Contract estimate up from £4.5bn to £15.3bn over ten years; £1.7bn spent in the first seven months of 2024–25, of which hotels £1.3bn (76%) while holding about 35% of people; 222 hotels on 1 January 2025 (348 a year earlier). Nine KPIs, not revised since the contracts began; £4m of deductions since 2019–20. Contracts can be ended on 270 days’ notice, with supplier costs payable if ended within seven years of mobilisation.
Source: National Audit Office, The Home Office’s asylum accommodation contracts (HC 874) (Paragraphs 1.14, 1.18, 2.2–2.6, 4, 8, 10; Figure 2)
- Change beyond existing law or funding
- The NAO has published the chain once; the Home Office does not report it annually, and the replacement model has not been compared with public alternatives on whole-life cost. The change adds an annual published chain and a public-versus-re-let comparison before the procurement route is fixed.
4.How it would work
Do: Publish the chain from budget to provider to type of accommodation, and compare replacement models on cost per suitable night and outcomes Changing: so that the renewal rewards suitable, lower-cost housing and timely move-on rather than hotel nights
Contracts delivering the specified service on time and near cost
Hypothesis to testEffect record E-A23-SERVICE
Recommended by research and audit; no evaluation estimates the effect of outcome-based renewal on asylum accommodation.
Lower cost per person per night through less hotel use
Hypothesis to test
Depends mostly on the number of people needing accommodation, which turns on asylum decision speed (the immigration brief), not on the contract alone.
Outcomes are kept separate and never added into one impact figure.
5.Best evidence
The Home Office’s asylum accommodation contracts (HC 874)
- Author or institution:
- National Audit Office
- Published:
- 7 May 2025
- Evaluation period:
- 2019 to January 2025
- Design:
- Value-for-money audit
- Sample or population:
- Home Office asylum accommodation contracts
- Effect and uncertainty:
- Contract estimate £4.5bn rising to £15.3bn; hotels 76% of cost and about 35% of people (2024–25, first seven months); nine KPIs unchanged since the start; large sites without performance measures.
- Limits:
- An audit, not an evaluation of alternative models; cost per person per night by type was not given in this report.
Where: Summary paragraphs 1–12; paragraphs 1.14, 1.18, 2.2–2.6; Figure 2. Affiliation is provenance, not proof of quality.
6.Alternatives, counter-evidence and who loses
- Closest feasible alternative
- Extend or re-let the current contracts on similar terms with revised KPIs.
- Strongest counter-evidence
- Most of the cost growth came from the number of people needing accommodation, which contracts do not control; bringing services in-house has not guaranteed better results (probation was reunified in 2021 and its performance worsened).
Source: National Audit Office, Building an effective and resilient probation service (HC 1354, Session 2024–2026) (Key findings paragraph 5)
- Distributional effects
- People in hotels and the areas hosting large sites are most affected; councils taking on provision gain control but bear delivery risk; incumbent providers may lose.
- Main downside
- A switch of model during high demand risks a capacity gap, which would push people back into hotels.
| Option | Who is reached | Evidence | Likely outcome and timing | Cost and funding | Main trade-off |
|---|---|---|---|---|---|
| The proposalPublish the money chain; compare an outcome-based re-let with council and public delivery before 2029 | People in asylum accommodation; host communities; taxpayers | NAO audit of the contracts; probation case for in-house limits | Chain within a year; new model from September 2029 | Appraisal cost not established; Home Office budget | Transition risk during high demand |
| Current policyCurrent policy: contracts run to August 2029 with nine unchanged KPIs | Same | NAO: KPIs unchanged, hotels dominate cost | No change to 2029 | £15.3bn estimated over ten years | Hotel dependence persists |
| AlternativeEnd the contracts early on 270 days’ notice | Same | Contract terms (NAO Figure 2) | Within a year of notice | Supplier costs payable if within seven years of mobilisation | Termination costs and capacity risk |
The options compared, including current policy
The proposal
Publish the money chain; compare an outcome-based re-let with council and public delivery before 2029
- Who is reached
- People in asylum accommodation; host communities; taxpayers
- Evidence
- NAO audit of the contracts; probation case for in-house limits
- Likely outcome and timing
- Chain within a year; new model from September 2029
- Cost and funding
- Appraisal cost not established; Home Office budget
- Main trade-off
- Transition risk during high demand
Current policy
Current policy: contracts run to August 2029 with nine unchanged KPIs
- Who is reached
- Same
- Evidence
- NAO: KPIs unchanged, hotels dominate cost
- Likely outcome and timing
- No change to 2029
- Cost and funding
- £15.3bn estimated over ten years
- Main trade-off
- Hotel dependence persists
Alternative
End the contracts early on 270 days’ notice
- Who is reached
- Same
- Evidence
- Contract terms (NAO Figure 2)
- Likely outcome and timing
- Within a year of notice
- Cost and funding
- Supplier costs payable if within seven years of mobilisation
- Main trade-off
- Termination costs and capacity risk
7.What other countries or the devolved nations show
Country lesson · England and Wales (within-UK case), Contracts ended December 2020; reunified in the public sector June 2021
Outsourcing probation, then bringing it back in-house, in England and Wales
Evidence: Expert or audit recommendationPartial match: some conditions differ
- What was changed
- Supervision of many offenders was contracted to private Community Rehabilitation Companies under the Transforming Rehabilitation reforms; after poor results the contracts were ended early and all offender management returned to the public Probation Service.
- Study design and population
- Audit reviews of an implemented reform (no controlled comparison) People on probation in England and Wales
- Measured outcome there
- Outsourcing: at least £467m paid above the original contract terms and contracts ended 14 months early; reoffences per reoffender rose 22% while the share reoffending fell 2.5 points. Insourcing: by 2024–25 the reunified service met 7 of 27 targets (26%), down from 50% in its first year.
- Cost status
- Historic: extra contract payments of at least £467m; probation spending £1.45bn in 2023–24.
- What failed or remains uncertain
- Both models disappointed. Bringing a service in-house did not by itself restore performance: staffing shortfalls and workloads mattered more than ownership.
- Why the UK differs
- A case from within the UK, but probation is a statutory public-protection service with a single public employer available; for asylum accommodation the alternatives (councils, housing associations, the Home Office itself) would have to build capacity first.
- First change required here
- Any renewal decision compares a re-let with in-house or council delivery on whole-life cost and on the capacity the public option would need, rather than on ownership alone.
Not a UK forecast: the effect above was measured in that place and population. Source: National Audit Office, Transforming Rehabilitation: Progress review (HC 1986, Session 2017–2019) (Paragraphs 1.4, 15, 19, 20); National Audit Office, Building an effective and resilient probation service (HC 1354, Session 2024–2026) (Key findings paragraph 5). Reviewed 2026-10-04.
8.What delivery needs first
- dependency — The number of people needing accommodation, set by asylum decision and appeal times (the immigration brief). (Genuine veto: nothing proceeds without it; owner: Home Office)
- infrastructure — Suitable dispersed housing in areas willing to host it. (Scarce resource shared with other priorities; owner: Councils and providers)
- procurement — The replacement procurement timetable: a decision before the Strategic Outline Case so the public interest test applies. (Requirement; owner: Home Office and Cabinet Office)
- staff — Contract-management and commercial staff to run outcome measures. (Scarce resource shared with other priorities; owner: Home Office)
9.What it would cost
How the cost is built up: Annual chain publication (analyst time) + options appraisal for the replacement (commercial and finance time) + transition costs of the chosen model; the accommodation itself is priced in the appraisal per suitable night.
| Component | Unit and quantity | Unit cost or amount | Type, price year, period | Status |
|---|---|---|---|---|
| Commercial staff, contract oversight, transition and supplier compliance for the renewalThe asylum accommodation contracts and their replacement | per procurement; quantity to be set from need and capacity | Not yet costed (ledger C-A23-CAPABILITY) | mixed; price year not stated; 2026–27 to 2029–30 | Not yet established |
| Current contracts, estimated whole-term cost (historic estimate, for context)Seven regional contracts, January 2019 to August 2029 | contract set; 1 | £15,300,000,000 | recurring; as estimated by the Home Office, reported May 2025 prices; 2019–2029 | Historic costContext only: the spending the renewal decision governs, not a cost of this proposal. Source: National Audit Office, The Home Office’s asylum accommodation contracts (HC 874) (Paragraph 4) |
Commercial staff, contract oversight, transition and supplier compliance for the renewal
The asylum accommodation contracts and their replacement
Not yet costed (ledger C-A23-CAPABILITY)
mixed; price year not stated; 2026–27 to 2029–30; Not yet established
Current contracts, estimated whole-term cost (historic estimate, for context)
Seven regional contracts, January 2019 to August 2029
£15,300,000,000 contract set
recurring; as estimated by the Home Office, reported May 2025 prices; 2019–2029; Historic cost
Context only: the spending the renewal decision governs, not a cost of this proposal.
Source: National Audit Office, The Home Office’s asylum accommodation contracts (HC 874) (Paragraph 4)
10.Who pays, and what is missing
- Programme envelope (a possible route, not an award)
- None identified
- Allocation committed to this change
- None
- Remaining gap
- The transition cost of any council or public model is not established.
- Proposed financing
- The Home Office asylum support budget already pays for accommodation; the appraisal and publication use its commercial budget.
- Responsible payer
- central government, councils
- Budget displaced
- Within the Home Office budget; councils taking on provision would need new funding rather than absorbing it.
11.First milestone and time to a useful result
The Home Office publishes the first annual money chain (spend by provider and accommodation type, cost per night, KPI results) and its options appraisal scope for the 2029 replacement (Owner: Home Office. Proposed by UK Facts, not an official deadline.)
Time to first useful result: The first chain within a year; the renewal decision before the replacement procurement begins.
What could delay it: Asylum demand stays high, limiting room to change model Councils lack housing or staff to bid The procurement is fixed before the public interest test applies in April 2027
12.How we would know
- Baseline
- NAO figures for 2024–25 (hotels 76% of cost, about 35% of people; £15.3bn ten-year estimate).
- Comparison
- Cost per suitable night and move-on times under the current contracts versus each replacement option, appraised on whole-life cost.
- Leading indicator
- Hotel share of people and of cost, published annually.
- Follow-up
- Each year to 2029, then the first two years of the replacement.
- Continue if
- Published costs per suitable night fall and standards and move-on improve.
- Adapt if
- Costs fall but standards or move-on worsen: revise the outcome measures.
- Stop if
- A model cannot provide enough suitable places without hotels — then keep a re-let with revised measures.
- Thresholds
- Not yet set: Cost-per-night benchmarks should come from the options appraisal and the Home Office business case.
What is not yet known, and how to find out
- What council-led or public delivery would cost per suitable night, including transition (cost)Next step: Include it in the options appraisal with councils’ quotes for dispersed housing and support.Scope: Replacement for the seven regional contracts · Data or quotes needed: Council and housing-association quotes; staffing; transition costs · Who can estimate it: Home Office with councils
- Cost per person per night for hotels and dispersed housing (data)Next step: Home Office to publish it in the annual chain; figures quoted in the press were not verified at source for this brief.
- Whether outcome-based contracts reduce hotel use (effect)Next step: Pilot outcome measures in one region before the national re-let.Defensible route: bounded pilot
Sources last checked 4 October 2026 · Owner: Evidence editor (James Harris) · Next check: the first trigger: Home Office asylum accommodation contract changes or the 2029 renewal decision.
More decision briefs on other pages
- Set realistic costs before spending, then manage the contracts that deliver the priorities to the result — the brief for “Buy measurable results and manage contracts through delivery”, on Public procurement
What it would take
The order things have to happen in
First, the prerequisite
Name the part of the gap and what forecasts already assume for it
Owner: HMRC with HM Treasury
No date: the timing depends on the steps before it.
Then, the decision
Fund a pilot with an independently scrutinised costing of net cash
Owner: HM Treasury; OBR certifies
No date: the timing depends on the steps before it.
Then, delivery
Publish outcome baselines for a set of renewing contracts
Owner: Cabinet Office with departments
No date: the timing depends on the steps before it.
Finally, the measured outcome
Cash collected and contract milestones reported each year
Owner: HMRC; NAO; contracting authorities
No date: the timing depends on the steps before it.
Who pays, and what is still missing
Cost, committed funding and the remaining gap for the same scope and years. A programme envelope is not an award to a project; a proposal is not committed money. None of these costs has been established yet, so no total is shown.
Cost and funding ledger
HMRC staff, training, systems, appeals and overheads for a further compliance package
A19 · administration · not costed
- Amount
- Not yet costed
- Who pays
- central government
- Committed
- None identified
- Proposed, not committed
- —
- Gap
- Not established
Commercial staff, contract oversight, transition, maintenance and supplier compliance
A23 · administration · not costed
- Amount
- Not yet costed
- Who pays
- central government, councils
- Committed
- None identified
- Proposed, not committed
- —
- Gap
- Not established
Meters, installation and a protected social tariff in seriously water-stressed areas
A53 · capital · not costed
- Amount
- Not yet costed
- Who pays
- bill-payers, households
- Committed
- None identified
- Proposed, not committed
- —
- Gap
- Not established
“Not yet costed” means no defensible cost has been found — not that the action is free. Lifetime benefits, benefit-cost ratios and forecast savings are never shown here as money available to spend.
Effects on record, with evidence ratings (4 records)
What the evidence says each action changes
| Action | Outcome and area | Effect | Compared with | Evidence |
|---|---|---|---|---|
| Collect more tax through specific, auditable compliance work | Net tax receipts beyond forecast Public finances and tax | Direction plausible; size not established | — | plausible spillover; limited confidence; United KingdomHMRC could not tell the NAO the marginal return to further investment; average yield ratios overstate it, and yield is not all cash. |
| Collect more tax through specific, auditable compliance work | Costs to compliant taxpayers wrongly challenged Public finances and tax · harm | Size not established | — | plausible spillover; limited confidence; United KingdomA risk to monitor through upheld disputes and service measures; not quantified. |
| Buy measurable results and manage contracts through delivery | Contracts delivering the specified service on time and near cost Public service delivery | Direction plausible; size not established | — | plausible spillover; limited confidence; United KingdomRecommended by research and audit; no evaluation estimates the effect. |
| Buy measurable results and manage contracts through delivery | Defence equipment programmes delivered closer to budget and schedule Defence and security | Direction plausible; size not established | — | plausible spillover; limited confidence; United KingdomAudit and expert recommendations, not an evaluation: no source estimates how much better contract management would reduce overruns, and policy changes cause some of them. |
How we would know
The outcome measures to watch. A baseline is where we start, not a target; where there is no official target we say so.
Projected public water supply deficit by 2055, without further action
billion litres a day · England
- Baseline
- Not published
- Latest
- up to 5
- National Framework for Water Resources, June 2025
Target: none — no official target for the deficit; water resources plans aim to close it by 2055.
Source: Environment Agency, National Framework for Water Resources 2025: water for growth, nature and a resilient future (Executive summary). Next release: next national framework and regional water resources plans (no date published) (check the release calendar).
Reservoir storage, England
% of capacity · England
- Baseline
- Not published
- Latest
- 56.4%
- week of 18–24 September 2026
Target: none — no target; the Environment Agency compares storage with the average for the time of year (18.6 points below in late September 2026).
Source: Environment Agency, Dry weather and drought in England: 18 to 24 September 2026 (Reservoir stocks). Next release: weekly during drought (Environment Agency dry weather reports) (check the release calendar).
Tax gap, share of tax due
% of theoretical liabilities · United Kingdom
- Baseline
- Not published
- Latest
- 6.4%
- tax year 2024–25 (projection, revised in later editions)
Target: none — no official tax-gap target; the compliance package is costed in cash, not as a gap reduction.
Source: HM Revenue and Customs, Measuring tax gaps 2026 edition: tax gap estimates for 2024 to 2025 (Table 1.2). Next release: annual (June) (check the release calendar).
Government major projects rated Red
projects (of 172 rated) · United Kingdom
- Baseline
- Not published
- Latest
- 34 of 172
- ratings at 31 March 2026
Target: none — no official target.
Source: National Infrastructure and Service Transformation Authority, NISTA Major Projects Annual Report 2025–26 (ratings at 31 March 2026) (Delivery confidence ratings). Next release: annual (summer) (check the release calendar).
Measured results
What each option would be judged on, and the latest value of the measures already on this page. A measure moving is not proof that an option caused it.
Deliver what is already funded
Judged on: Quality-adjusted service delivered, whole-life costs and supplier performance.
Data source: not yet named; baseline: not yet established.
- Government major projects rated RedLatest: 34 of 172 (ratings at 31 March 2026). Baseline: not published. United Kingdom.
National plan: Growth and prosperity list
Judged on: Collected additional revenue net of costs, error and disputes.
Data source: not yet named; baseline: not yet established.
- Tax gap, share of tax dueLatest: 6.4% (tax year 2024–25 (projection, revised in later editions)). Baseline: not published. United Kingdom.
National plan: Equality and opportunity list
Meter water-stressed households with an effective social tariff
Judged on: Litres per person/day, arrears and essential-use hardship over 12–24 months; tariff take-up.
Data source: not yet named; baseline: not yet established.
- Projected public water supply deficit by 2055, without further actionLatest: up to 5 (National Framework for Water Resources, June 2025). Baseline: not published. England.
- Reservoir storage, EnglandLatest: 56.4% (week of 18–24 September 2026). Baseline: not published. England.
National plan: Resilience and sustainability appraisal queue
Where the ideas come from
Research, counter-evidence and methods (13 sources)
- Measuring tax gaps 2026 edition: tax gap estimates for 2024 to 2025 — HM Revenue and Customs, 2026-06-23.Official statistics; United Kingdom. Relevant passages checked, 2026-10-04. Limits: An estimate of tax not paid, including error, insolvency and legal disputes — not a measure of what extra enforcement could collect.
- Taxing large businesses (HC 1647, Session 2024–26) — National Audit Office, 2026-02-27.Value-for-money audit of HMRC’s large business directorate; About 2,000 large business groups; about 2,500 full-time-equivalent HMRC staff; United Kingdom. Relevant passages checked, 2026-10-04. Limits: Large businesses only. Yield is skewed by a few very large interventions and is not a measure of cash that would be raised by expanding enforcement.
- HMRC performance update: 2026 to 2027 quarter 1 (13 August 2026) — HM Revenue and Customs, 2026-08-13.Corporate report (Burnham government). Full text checked, 2026-10-04. Limits: “£10 billion of additional tax revenue per year by 2029 to 2030”; plans to “recruit and train 5,500 new compliance caseworkers”, “more than 2,400 since Autumn Budget 2024”; “we have recruited a new team of 350 criminal investigators”; 2026-27 yield aim with “at least a quarter of it to come from work focused on stopping” non-compliance; tax-debt ratio.
- Autumn Budget 2024 (HC 295): “Closing the tax gap” — HM Treasury, 2024-10-30.Budget document; United Kingdom. Relevant passages checked, 2026-10-04. Limits: The £6.5bn is already in the fiscal forecasts, so it cannot fund anything new. No separate HMRC investment amount is stated in this section.
- The role of procurement in delivering mission-led government — Institute for Government (Ben Paxton, Nick Davies), 2025-09-23.Interview-based analysis with recommendations; United Kingdom (mainly central government). Relevant passages checked, 2026-10-04. Limits: Qualitative: no estimate of savings or service effects. It does not contain a £461bn figure — the site’s £461.3bn whole-public-sector total comes from PESA 2026 (P-HMT-PESA-2026).
- A new vision for water (white paper) — Department for Environment, Food & Rural Affairs, 2026-01-20.White paper (Starmer government); England and Wales. Full text checked (Read in the PDF “Defra Water White Paper 2026 (with correction slip)”.), 2026-10-04. Limits: Government policy intentions; most measures need the new regulator or legislation.
- National Framework for Water Resources 2025: water for growth, nature and a resilient future — Environment Agency, 2025-06-17.Official planning framework (modelled scenarios); England. Relevant passages checked, 2026-10-04. Limits: Modelled scenarios of population, climate and environmental needs; “up to” is the top of a range. England only.
- Pursuing Recoveries and Preventing Reoccurrence: Final Report of the Covid Counter Fraud Commissioner (CP 1462) — HM Treasury, December 2025.Official report (command paper); United Kingdom. Relevant passages checked, 2026-10-04.
- Procurement Reform Starts with Requirement Formulation and the Supply Chain — Royal United Services Institute (Sir Julian Brazier, Ryan Shea), 2024-07-29.Expert commentary; United Kingdom (Ministry of Defence). Full text checked, 2026-10-04. Limits: Commentary with anecdotal examples; predates the 2025 Strategic Defence Review and the 2026 Defence Investment Plan. One author is a former defence minister.
- The Equipment Plan 2023 to 2033 — National Audit Office, 2023-12.Public audit; United Kingdom. Relevant passages checked, 2026-10-04. Limits: Predates the 2025 Strategic Defence Review and 2026 Defence Investment Plan; the MOD stopped publishing an equipment plan after this edition.
- NISTA Major Projects Annual Report 2025–26 (ratings at 31 March 2026) — National Infrastructure and Service Transformation Authority, 2026-07-13.Official transparency data; United Kingdom. Relevant passages checked, 2026-10-04. Limits: A delivery-confidence rating is a judgement about a project’s prospects, not a measure of military readiness or of value for money.
- The effects of the Universal Metering Programme on water consumption, welfare and equity — University of Southampton, Department of Economics (Discussion Paper 1801) (Ornaghi C, Tonin M), 2018.Household panel of metered consumption before and after compulsory meter installation, with fixed effects and comparisons with households not yet switched.; Households in Southern Water’s Universal Metering Programme (about half a million meters installed); Southern Water area (Hampshire, Isle of Wight, Sussex, Kent). Full text checked, 2026-10-04. Limits: One company area and period; not peer-reviewed in this version; costs of meters and of the social tariff are programme-specific.
- Dry weather and drought in England: 18 to 24 September 2026 — Environment Agency, 2026-10-02.Official weekly situation report; England. Relevant passages checked, 2026-10-04. Limits: A point-in-time status that changes week to week; replace with the latest report before reuse.
Counter-evidence and criticism
- Collect more tax through specific, auditable compliance work: Returns diminish as easier cases are worked; yield includes revenue “protected” that never arrives as cash; wrongly challenged taxpayers bear real costs. (National Audit Office)
- Buy measurable results and manage contracts through delivery: More reporting can deter small suppliers and add cost; outcome contracts are hard to specify for complex services; social-value requirements complicate price comparison. (Institute for Government)
- Meter homes in water-stressed areas, with a social tariff that protects low-income households: The same study finds that for a large share of households the social cost of a meter outweighs its benefit, and that less affluent households lose on average; it suggests selective metering of larger households could be more efficient than universal metering. (University of Southampton, Department of Economics (Discussion Paper 1801))
“Full text checked” means we read the report itself; “relevant passages” means the sections behind each figure; “summary or abstract only” means we could not read the full study, so no number from it is published here without another source.
Other options compared — not on the shortlist (3)
Other options compared
Options from earlier work on this page that are not on the shortlist. They remain valid choices; their evidence is shown as before.
- preventionStatus: operating
Prevent and recover public-sector fraud and error
- Aims to:
- Less money lost from schemes and contracts, and more of what is lost recovered.
- How:
- Fraud checks built into schemes before money is paid; investigators and new legal powers pursue recovery after.
- Who decides:
- Public Sector Fraud Authority (Cabinet Office and HM Treasury), departments, HMRC, the Insolvency Service.
- Main constraint:
- Recovery is slow and partial once companies dissolve; prevention adds friction to schemes that must pay quickly.
- Evidence:
- Moderate evidence — evaluated, with limits on scope or transfer
See the trade-offs and evidence
- What the evidence shows
- The Covid Counter Fraud Commissioner found £1.8bn recovered of an estimated £10.9bn lost, with much of the rest beyond recovery — evidence that prevention is worth more than recovery. Disputed PPE contracts were cut from 55 (£1.26bn) to 8 (£325m of potential recoveries).
- Policy status
- The Commissioner’s December 2025 report said the Public Authorities (Fraud, Error and Recovery) Bill, extending the time limit for Covid fraud action, would shortly receive Royal Assent.
- Resources
- Counter-fraud investigators, data-matching and legal capacity.
- Consent and decisions needed
- New data-sharing and recovery powers raise civil-liberties questions debated in Parliament.
- Time
- Prevention acts on new schemes immediately; recovery cases take years.
- Cost and yield
- No published figure for the net return on additional counter-fraud spending across government.
- Trade-offs and who pays
- Tighter checks slow payments to genuine claimants in an emergency.
- How we would know it worked
- Leading indicator: Cash recovered (received, not claimed) each year. Outcome: Lower estimated fraud and error rates in new schemes. It would not be working if: Announced recoveries are not matched by cash received.
- structuralStatus: legislated
Regulate private payments in regulated monopolies
- Aims to:
- Dividends and bonuses in water and energy networks linked to performance for customers.
- How:
- Regulators set allowed returns and can block payments; new law lets Ofwat ban bonuses where companies fail environmental standards.
- Who decides:
- Ofwat and Ofgem; Defra and DESNZ for legislation.
- Main constraint:
- Companies need investors to fund large investment programmes; tighter returns can raise their cost of capital.
- Evidence:
- Limited evidence — plausible mechanism, little direct evaluation
See the trade-offs and evidence
- What the evidence shows
- Water dividends declared fell from £1.0bn in 2023–24 to £0.645bn in 2024–25, but the fall cannot be attributed to any one rule. Whether payment restrictions improve services has not been evaluated.
- Policy status
- Water (Special Measures) Act 2025.
- Resources
- Regulator staff and enforcement capacity.
- Consent and decisions needed
- Price reviews and legislation; customers pay through bills either way.
- Time
- Takes effect at each price review (five-year periods).
- Cost and yield
- Not a revenue measure; changes who receives money rather than raising it for government.
- Trade-offs and who pays
- Lower payouts to shareholders may mean higher borrowing costs or less investment.
- How we would know it worked
- Leading indicator: Dividends and bonuses paid relative to performance targets. Outcome: Fewer pollution incidents and leaks; stable bills. It would not be working if: Payments fall but performance does not improve.
- structuralStatus: operating
Reallocate spending through the Spending Review
- Aims to:
- Money moved from lower- to higher-value uses within existing totals.
- How:
- The Treasury and departments compare the value of programmes and move budgets at a spending review.
- Who decides:
- HM Treasury, departments, Parliament (Estimates).
- Main constraint:
- Most spending is demand-led or contractual; little can move in a single year.
- Evidence:
- Limited evidence — plausible mechanism, little direct evaluation
See the trade-offs and evidence
- What the evidence shows
- Spending reviews routinely reallocate money; systematic evidence on whether reallocations improved outcomes is sparse because most programmes are not evaluated against a counterfactual.
- Resources
- Evaluation capacity across departments.
- Consent and decisions needed
- Ministerial agreement and parliamentary votes; every reallocation has losers.
- Time
- At each spending review (every two to three years).
- Cost and yield
- None directly; the cost is what is given up.
- Trade-offs and who pays
- Every line moved takes money from a service someone relies on.
- How we would know it worked
- Leading indicator: Share of spending covered by robust evaluation. Outcome: Outcome measures improving in programmes that gained money. It would not be working if: Money moves but outcome measures do not.
| Option | Resources | Time | Evidence | Outcome to watch |
|---|---|---|---|---|
| Prevent and recover public-sector fraud and error | Counter-fraud investigators, data-matching and legal capacity. | Prevention acts on new schemes immediately; recovery cases take years. | moderate | Lower estimated fraud and error rates in new schemes. |
| Regulate private payments in regulated monopolies | Regulator staff and enforcement capacity. | Takes effect at each price review (five-year periods). | limited | Fewer pollution incidents and leaks; stable bills. |
| Reallocate spending through the Spending Review | Evaluation capacity across departments. | At each spending review (every two to three years). | limited | Outcome measures improving in programmes that gained money. |
Plan reviewed 2026-10-04. How we judge evidence.
How this connects
- The whole annual budget, on one scale
Receipts, spending, borrowing and the debt interest bill, with the debt shown separately.
- What could each revenue option raise?
Design-specific yields, with what is already in the forecasts and what overlaps.
- Water in public ownership: what would it cost and save?
Ofwat’s figures, with the assumptions that decide the answer.
A model, not an official costing.
- The electricity grid in public ownership: a model
Ofgem’s figures on financing costs, debt taken on and who carries the risk.
A model, not an official costing.
Sources and methods (14)
- HMRC, Measuring tax gaps 2026 edition, 1. Tax gaps: summary (estimates for the 2024 to 2025 tax year) (released 23 June 2026) — Official statistics (HMRC): headline tax gap estimate, £59.2bn and 6.4% of tax due, 2024–25
- HMRC, Measuring tax gaps 2026 edition: online tables, Table 1.2 (by type of tax, with total liabilities), Table 1.3 (by customer group), Table 7.1 (illustrative, by behaviour), column 2024-25 (released 23 June 2026) — Official statistics (HMRC): tax gap by type of tax, customer group and behaviour
- HM Treasury, Public Expenditure Statistical Analyses 2026, Table 4.2 (released 16 July 2026) — Official statistics (HM Treasury): public spending by function
- OBR, Public finances databank (September 2026); outturn consistent with ONS/HM Treasury Public sector finances, 22 September 2026, sheets "Aggregates (£bn)", "Aggregates (per cent of GDP)" and "Receipts (£bn)" (released September 2026) — Official statistics and forecasts (OBR databank): total managed expenditure
- HM Treasury, Autumn Budget 2024 (HC 295), section “Closing the tax gap”: £6.5 billion a year by 2029-30 (released 30 October 2024) — Government fiscal-event document (costing certified by the OBR): compliance package yield
- HM Treasury, Pursuing Recoveries and Preventing Reoccurrence: Final Report of the Covid Counter Fraud Commissioner (CP 1462) (released December 2025) — Official report (HM Treasury command paper): Covid fraud and error losses, recoveries and PPE disputes
- Ofwat, Monitoring financial resilience report 2024-25, dividends declared and sector net debt, companies in England and Wales (released November 2025) — Regulator publication (Ofwat): water company dividends and net debt
- National Grid plc, National Grid plc - Annual Report & Accounts 2026 - ESEF (FCA National Storage Mechanism, filing NI-000146094), consolidated income statement, profit before tax, statutory column (released 2026-06-03) — Company audited accounts: group profit before tax
- SSE plc, Annual Financial Report 2026 in Structured Electronic Format (FCA National Storage Mechanism, filing NI-000146697), consolidated income statement, profit before tax, statutory column (released 2026-06-12) — Company audited accounts: group profit before tax
- Centrica plc, Centrica plc Annual Report and Accounts 2025 (tagged) (FCA National Storage Mechanism, filing NI-000141809), consolidated income statement, profit before tax, statutory column (released 2026-02-19) — Company audited accounts: group profit before tax
- Drax Group plc, Annual Report and Accounts 2025 (ESEF) (FCA National Storage Mechanism, filing NI-000143806), consolidated income statement, profit before tax, statutory column (released 2026-03-25) — Company audited accounts: group profit before tax
- Public Sector Fraud Authority (GOV.UK organisation page) — Government body (Cabinet Office and HM Treasury): owner of the counter-fraud option
- Water (Special Measures) Act 2025 — Legislation: Water (Special Measures) Act 2025, the regulation option
- HM Treasury, Spending Review 2025 (released 11 June 2025) — Government fiscal-event document: Spending Review 2025, the reallocation option
Method notes
- Editorial rule: evidence first; interpretation is attributed; where a comparison involves a value choice, the page says so. The page offers analysis — for example that help with record-keeping may matter as much as investigations — and names it as inference, with its limits, wherever it appears.
- The headline figure is HMRC table 1.2, column 2024-25: total tax gap £59.2bn against total theoretical liabilities £924.4bn, 6.4% (6.40% unrounded). The components by type of tax sum to the total; none is additional to it.
- Company profits are statutory group profit before tax for the whole group (worldwide), as reported — not adjusted or “underlying” measures, and not UK-only.
- The tax gap’s latest two years are projections from earlier data and are revised in later editions; HMRC rates the uncertainty of each component.
- A recovery counts here only when cash has been received. Claims, awards and announced recoveries are different stages.