Brexit · United Kingdom · trade 2019 to 2025
Brexit added trade barriers. Which can Britain now remove?
Goods exports to the EU in 2025 were 14% below 2019 by volume — an observed change, not all caused by Brexit. A food and plant agreement is being negotiated to reduce some checks. Customs declarations and other trade barriers would remain.
Priority: Set out which trade barriers could be reduced, by which route, and what each would require in rule alignment, implementation and policy autonomy. What would change it →
Evidence last reviewed 3 October 2026
Overview
The short version
Three key measures
How did goods exports to the EU change?
−14%vs 2019, by volume
UK goods exports to the EU in 2025 against 2019, excluding precious metals and price changes. To non-EU countries: −8%. Since January 2021 EU-bound goods need customs declarations and food and plant checks. An observed comparison, not a measured estimate of Brexit’s effect: a 2021 measurement break and other shocks sit in the same years.
Trade in goods and services →United Kingdom · 2019 to 2025
Source: How did goods exports to the EU change?
Site calculation · ONS, UK trade time series (MRET), chained volume measures, CDIDs JIM8, JIN3, JIM7, JIN2 (goods excluding precious metals); IKBE, IKBF (services)
What do forecasters estimate it costs in the long run?
4%lower productivity (modelled)
The OBR assumes long-run productivity 4% below where it would have been inside the EU — an estimate against a path that cannot be observed. An NBER study puts GDP 6% to 8% lower by the end of 2025. Different measures, different methods.
Investment and productivity estimates →United Kingdom · Long run (OBR); to end-2025 (NBER)
Source: What do forecasters estimate it costs in the long run?
Modelled scenario · Office for Budget Responsibility, Brexit analysis
Was the new control over migration used?
−42kEU+ net migration
In the year to December 2025 more EU+ nationals left the UK than arrived, after free movement ended on 31 December 2020. Non-EU+ net migration, set by UK visa rules, was +350k. A legal change, visibly used — its effect on total numbers depended on later choices.
Migration’s changing composition →United Kingdom · year to December 2025
Source: Was the new control over migration used?
Provisional · ONS, Long-term international migration, provisional: year ending December 2025, Table 1
Who feels this most?
The costs of new border paperwork are mostly fixed per consignment, so they weigh most on small exporters. The most detailed academic study of UK–EU trade after 2021 found a large and lasting drop in the number of low-value export relationships, alongside a 25% fall in imports from the EU relative to the rest of the world. Trade in detail.
Which barriers can Britain now remove?
- Food and plant checks — closest to removal. A UK–EU agreement on sanitary and phytosanitary (SPS) rules, agreed in principle in May 2025 and still being negotiated, would remove export health certificates and most routine checks. The price is following EU food and plant rules in those areas without a vote on them. Read the decision brief.
- Carbon border charges — under negotiation. Linking the UK and EU carbon markets would exempt UK goods from the EU’s carbon border levy.
- Customs declarations and rules of origin — stay. Declarations remain even inside a customs union; rules-of-origin checks go only inside one. The single market would remove most other goods and services barriers but brings back free movement. Compare all the options.
The evidence
The evidence, question by question
What changed, and how do we know?
Brexit is three different kinds of question. Some answers are legal facts with a date. Some are measured by official statistics. The largest — what the economy would look like had the UK stayed — can only be estimated by models. The ledger keeps them apart and says how strong each piece of evidence is.
What changed, and how do we know?
The legal changes are certain; the trade frictions are measurable; the economy-wide cost is an estimate
Each row separates a dated legal change, what official statistics show happened, and what models estimate relative to staying in the EU. Columns are not scored or added: an empty cell means no reliable evidence, not zero effect.
- Legal fact
- Strong evidence
- Moderate evidence
- Limited evidence
- No reliable estimate
Immigration
31 Dec 2020Legal or institutional change
What the law or treaty now says
Legal factFree movement ended. One points-based system now covers EU and non-EU nationals, set entirely in UK law.
Observed outcome
What official statistics show happened
Strong evidenceEU+ net migration went from +322k (year to June 2016) to −42k (year to December 2025). Non-EU+ rose to +1,047k, then fell to +350k.
Modelled estimate
Compared with staying in the EU — not observed
No reliable estimateNo widely used estimate of migration without Brexit.
More on immigration →Who is affected, limits and sources
- Who is affected:
- EU citizens; employers in care, hospitality, food processing and haulage that relied on EU recruitment.
- Limits of the evidence:
- Migration estimates are provisional and heavily revised. The non-EU rise reflects later visa policy, not the end of free movement itself.
Goods trade
1 Jan 2021Legal or institutional change
What the law or treaty now says
Legal factThe UK left the single market and customs union. The Trade and Cooperation Agreement keeps zero tariffs for goods meeting rules of origin, but adds customs declarations and food and plant checks.
Observed outcome
What official statistics show happened
Moderate evidenceGoods exports to the EU −14% by volume since 2019; to non-EU −8%. Imports from the EU −2%; from elsewhere +10%.
Modelled estimate
Compared with staying in the EU — not observed
Moderate evidenceCEP/LSE study: the trade deal caused a sudden, persistent 25% fall in imports from the EU relative to the rest of the world, a smaller and temporary relative fall in exports, and the loss of many small export relationships. OBR: trade intensity 15% lower in the long run.
More on goods trade →Who is affected, limits and sources
- Who is affected:
- Small exporters (paperwork costs are per consignment), food and farming businesses, manufacturers with EU supply chains.
- Limits of the evidence:
- A measurement break in EU goods data from January 2021; the pandemic and energy shock hit the same years.
- Sources:
- UK Government, Agreements reached between the UK and the EU (Trade and Cooperation Agreement, December 2020); ONS, UK trade time series (MRET), chained volume measures; Freeman, Manova, Prayer and Sampson, “UK trade in the wake of Brexit”, CEP Discussion Paper 1847 (LSE); Office for Budget Responsibility, Brexit analysis
Services trade
1 Jan 2021Legal or institutional change
What the law or treaty now says
Legal factNo automatic right to sell services across the EU and no blanket recognition of professional qualifications; firms need authorisation member state by member state.
Observed outcome
What official statistics show happened
Moderate evidenceServices exports to all partners +26% by volume since 2019. ONS publishes the EU/non-EU split only in current prices.
Modelled estimate
Compared with staying in the EU — not observed
No reliable estimateNo estimate on this site that isolates the effect on services.
More on services trade →Who is affected, limits and sources
- Who is affected:
- Professional, financial and creative services firms; touring performers.
- Limits of the evidence:
- Without an EU split in volume terms, services growth cannot be attributed to particular markets.
Investment, productivity and GDP
2016 onwardsLegal or institutional change
What the law or treaty now says
No reliable estimateNo single legal change: the effect runs through uncertainty from the 2016 vote and through trade costs from 2021.
Observed outcome
What official statistics show happened
Moderate evidenceBusiness investment +14% on 2016 Q2 by 2026 Q2. Observed growth does not show what would have happened otherwise.
Modelled estimate
Compared with staying in the EU — not observed
Moderate evidenceOBR: long-run productivity 4% lower than if the UK had remained, two-fifths of it already by 2021. NBER (Bloom et al.): GDP 6% to 8%, investment 12% to 13% and productivity 3% to 4% lower by end-2025.
More on investment, productivity and gdp →Who is affected, limits and sources
- Who is affected:
- Everyone through incomes and tax revenue; the estimates are economy-wide averages, not effects on each household.
- Limits of the evidence:
- Counterfactuals cannot be observed. The estimates use different measures and methods and should not be swapped for one another.
Trade policy
2023–2024Legal or institutional change
What the law or treaty now says
Legal factAn independent trade policy: new agreements with Australia and New Zealand (in force 2023) and accession to the CPTPP (2024).
Observed outcome
What official statistics show happened
No reliable estimateToo recent to measure separately from other trade changes.
Modelled estimate
Compared with staying in the EU — not observed
Moderate evidenceGovernment impact assessments: Australia +0.08% of GDP by 2035, New Zealand +0.03%, CPTPP about £2bn a year by 2040.
More on trade policy →Who is affected, limits and sources
- Who is affected:
- Exporters to those markets; UK farmers facing more import competition.
- Limits of the evidence:
- The government’s own models; small relative to the estimated EU effect, and not designed to offset it.
Regulation, subsidies, farming and fishing
2020–2023Legal or institutional change
What the law or treaty now says
Legal factNew UK regimes for farm support (Agriculture Act 2020), fishing (Fisheries Act 2020) and subsidies (Subsidy Control Act 2022), and powers to revoke or amend retained EU law (2023).
Observed outcome
What official statistics show happened
No reliable estimateNo single official measure of how far UK rules have diverged, or of the effect of divergence.
Modelled estimate
Compared with staying in the EU — not observed
No reliable estimateNo reliable aggregate estimate.
More on regulation, subsidies, farming and fishing →Who is affected, limits and sources
- Who is affected:
- Farmers (support now tied to environmental schemes rather than land area), fishing fleets, firms selling into both markets.
- Limits of the evidence:
- Using the freedom to diverge can raise costs for firms that must also meet EU rules; how much it has been used is contested.
Northern Ireland
2021; Feb 2023Legal or institutional change
What the law or treaty now says
Legal factNorthern Ireland follows EU goods rules and keeps an open land border; goods from Great Britain pass checks in the Irish Sea, eased by the Windsor Framework. The Assembly voted in December 2024 to continue the arrangements, without cross-community support.
Observed outcome
What official statistics show happened
Limited evidenceSee the Northern Ireland chapter: power-sharing was suspended from February 2022 to February 2024.
Modelled estimate
Compared with staying in the EU — not observed
No reliable estimateNo reliable estimate of the net economic effect of dual market access.
More on northern ireland →Who is affected, limits and sources
- Who is affected:
- Northern Ireland businesses and consumers; traders moving goods from Great Britain.
- Limits of the evidence:
- Economic effects are hard to separate from the wider UK picture.
Read across a row, not down a column. Two things are certain: the UK now writes its own rules in each area listed, and goods trade with the EU carries costs it did not before 2021. The observed trade change is moderately strong evidence of friction, weakened by a measurement break and the pandemic. The economy-wide cost rests on models: the OBR and the main academic study both estimate a cost, on different measures and of different sizes. There is no agreed rate for converting autonomy into GDP, so no total is given.
Did goods and services trade follow the same path?
Goods exports to the EU are 14% below 2019; services exports are 26% above
Two panels, each indexed to 2019 = 100. First panel: UK goods exports by destination, excluding precious metals. Second panel: UK services exports and imports, all partners (ONS publishes services volumes only for the world total).
Goods exports, by destination
1996–2026 displayed window · observations only. Shading marks years outside the displayed record.
Services, all partners
1996–2026 displayed window · observations only. Shading marks years outside the displayed record.
The gap in the EU goods line marks the January 2021 change from survey returns to customs declarations. Both panels share the same scale.
By volume, goods exports to the EU in 2025 were 14% below 2019; to the rest of the world, 8% below. That gap is consistent with new border frictions, but it is not a clean measure of Brexit: the measurement break and other shocks sit in the same years. Services exports grew 26% over the same period. Neither line shows what trade would have been inside the EU.
United Kingdom · 2000 to 2025, calendar years · Accredited official statistics; recent years are revised as new data arrive
Sources, definitions and data — Goods exports to the EU are 14% below 2019; services exports are 26% above
- Geography:
- United Kingdom — UK trade in goods and services, balance-of-payments basis
- Measure:
- Volume index, 2019 = 100 (chained volume measures, seasonally adjusted)
- Period:
- 2000 to 2025, calendar years
- Status:
- Accredited official statistics; recent years are revised as new data arrive
- Calculation:
- Site calculation: each ONS chained-volume series divided by its own 2019 value × 100. Volumes remove price changes, so nominal and real values are not mixed.
- Compare with:
- Each series’ own 2019 level; goods exports to non-EU countries (−8%) as a partial control for shocks that hit all trade
- Not included / breaks:
- A structural break in EU goods trade from January 2021 (customs declarations replaced the Intrastat survey), shown as a gap in the EU line. The pandemic and the 2022 energy shock fall inside the same window. Precious metals are excluded because gold flows through London swamp the non-EU figures. A services split by EU and non-EU exists only in current prices, so it is not compared here.
Source: ONS, UK trade time series (MRET), chained volume measures, CDIDs JIM8, JIN3, JIM7, JIN2 (goods excluding precious metals); IKBE, IKBF (services) (released 11 September 2026). Chart BREXIT-02.
View the data as a table
| Year | Goods exports to EU | Goods exports to non-EU | Services exports (all) | Services imports (all) |
|---|---|---|---|---|
| 2000 | 87.0 | 57.2 | 45.0 | 47.6 |
| 2001 | 90.1 | 56.9 | 46.2 | 48.8 |
| 2002 | 92.7 | 56.0 | 46.2 | 50.8 |
| 2003 | 86.8 | 59.8 | 49.6 | 52.8 |
| 2004 | 86.7 | 61.8 | 54.8 | 56.6 |
| 2005 | 90.7 | 69.3 | 58.7 | 59.1 |
| 2006 | 112.8 | 67.7 | 64.3 | 61.3 |
| 2007 | 95.2 | 68.9 | 70.9 | 63.0 |
| 2008 | 91.6 | 72.8 | 74.8 | 62.4 |
| 2009 | 84.1 | 66.6 | 69.7 | 59.4 |
| 2010 | 89.5 | 75.3 | 71.1 | 62.4 |
| 2011 | 93.0 | 81.9 | 76.2 | 63.0 |
| 2012 | 88.1 | 85.0 | 78.5 | 65.1 |
| 2013 | 87.1 | 85.2 | 79.4 | 67.2 |
| 2014 | 89.7 | 85.1 | 79.9 | 72.7 |
| 2015 | 91.4 | 89.5 | 83.2 | 79.8 |
| 2016 | 95.3 | 90.4 | 87.2 | 83.3 |
| 2017 | 101.3 | 96.9 | 93.0 | 87.8 |
| 2018 | 101.4 | 99.6 | 98.5 | 96.4 |
| 2019 | 100.0 | 100.0 | 100.0 | 100.0 |
| 2020 | 87.5 | 87.2 | 89.3 | 77.2 |
| 2021 | 86.0 | 91.6 | 94.2 | 78.6 |
| 2022 | 94.3 | 94.8 | 109.9 | 100.0 |
| 2023 | 89.1 | 94.6 | 112.7 | 108.2 |
| 2024 | 86.5 | 92.3 | 120.9 | 115.0 |
| 2025 | 85.8 | 91.7 | 126.5 | 118.5 |
Scroll the table sideways to see every column.
Who feels this most?
Food and farming businesses face the heaviest checks: animal and plant products need export health certificates and can be physically inspected — the area a UK–EU food-safety agreement is meant to address. Northern Ireland has a position unlike any other region: access to both markets for goods, and a trade border with Great Britain. Northern Ireland.
EU citizens and the employers who recruited them felt the end of free movement most directly: EU+ net migration went from +322k in the year to June 2016 to −42k in the year to December 2025. Migration’s changing composition.
Shareable visual summary
Visual summary
Image currentEvery figure printed in the image matches today’s record, and its primary sources have been checked.
The OBR’s 4% compares two futures — it is not an observed fall.
The OBR assumes long-run productivity will be about 4% lower than if the UK had stayed in the EU. Index 100 against 96 illustrates that assumption; it is not GDP history.
Schematic: long-run productivity index (assumption, not data)
- Remain counterfactual100
- OBR assumption96
Illustrates the OBR assumption. No forecast path or confidence interval is implied.
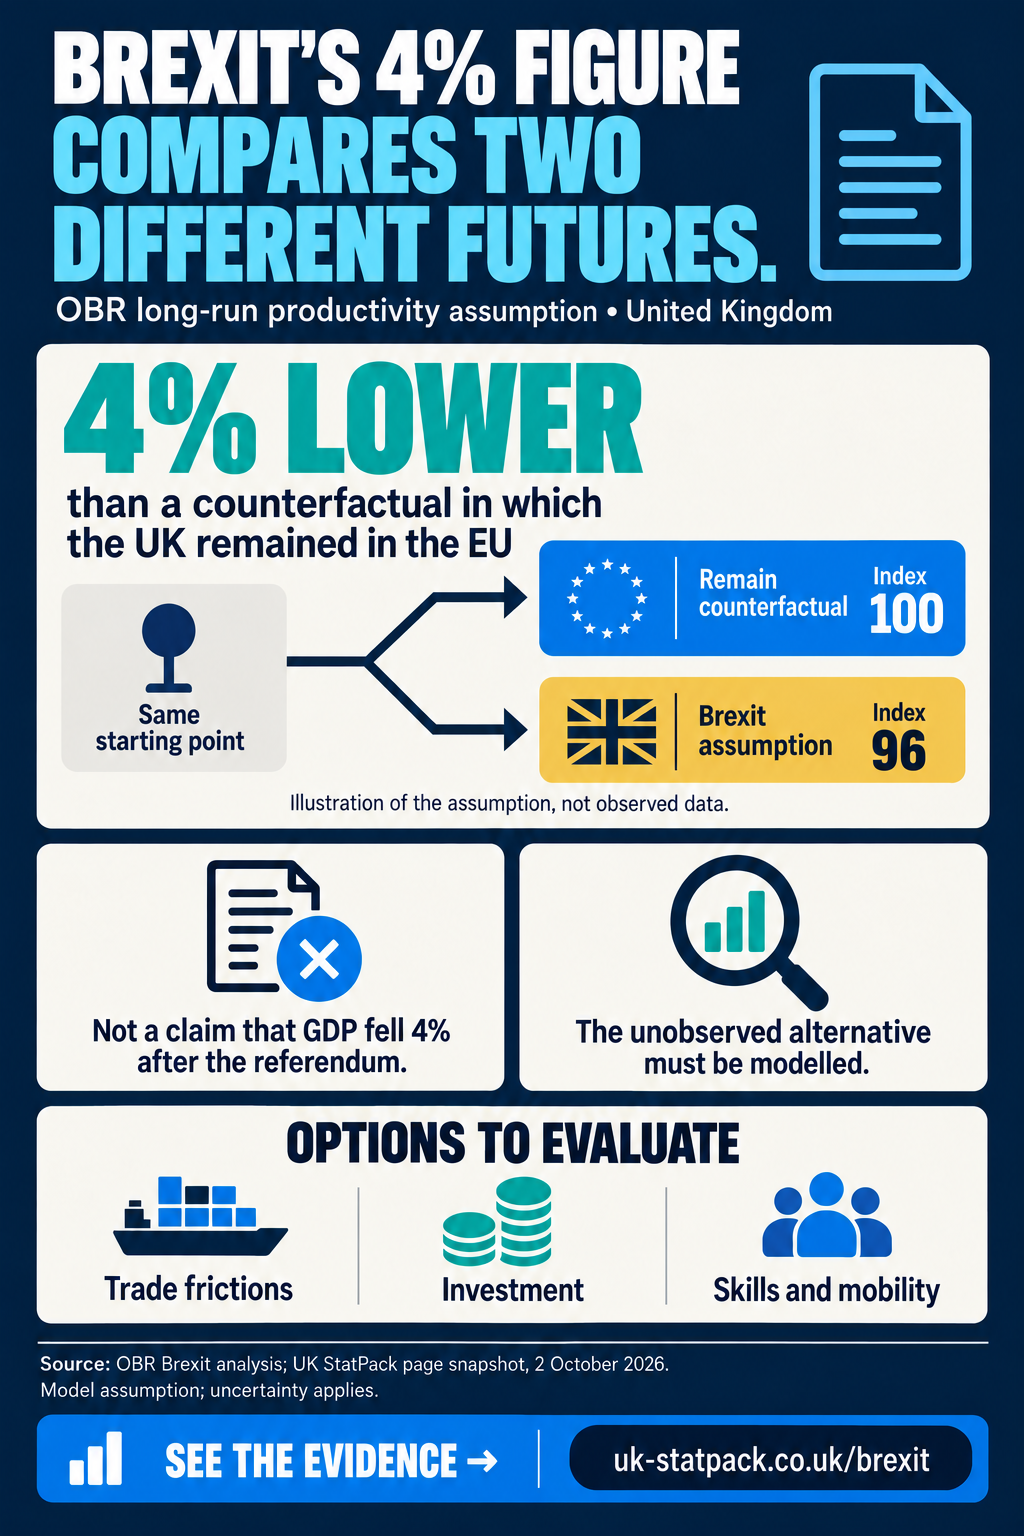
Text and data version
The OBR’s 4% compares two futures — it is not an observed fall. The OBR assumes long-run productivity will be about 4% lower than if the UK had stayed in the EU. Index 100 against 96 illustrates that assumption; it is not GDP history.
| Measure | Value | Period | Geography | Type | Source |
|---|---|---|---|---|---|
| OBR assumption: long-run productivity relative to remaining in the EU | 4% lower | Long run (about 15 years from 2016) | United Kingdom | model assumption | OBR, Brexit analysis |
Image description: Brexit infographic: the OBR assumes long-run productivity about 4% lower than in a remain counterfactual — an assumption, not an observed fall.
All visual summaries, their source records and their publication state are listed on Shareable visuals.
Go deeper
The outcome ledger: what changed, area by area?Legal change, observed outcome and modelled estimate for each area, each with its own date, source and limit.Weighted by evidence, not by equal columns.Read the chapter → The outcome ledger: what changed, area by area? Trade: did goods and services follow different paths? +15.8%1997–2025United Kingdom · £ million, chained volume measureExports to the EU in volume terms. A 2021 recording break means the whole change cannot be attributed to Brexit.159,275 → 184,4811997–2025Exports and imports, EU and non-EU, with the 2021 measurement break shown.Read the chapter → Trade: did goods and services follow different paths?Sources and data
Chained volume measure (prices held constant), seasonally adjusted, balance-of-payments basis. Levels are re-referenced in each annual national accounts vintage, so this file is always replaced whole; compare growth or an index, not levels across vintages. From January 2021 UK goods trade with the EU is compiled from customs declarations instead of the Intrastat survey; ONS says a structural break remains in EU goods series from that date.
Source dataset →Period £ million, chained volume measure Status 1997 159,275 Outturn 1998 165,881 Outturn 1999 172,195 Outturn 2000 187,042 Outturn 2001 193,853 Outturn 2002 199,363 Outturn 2003 186,700 Outturn 2004 186,559 Outturn 2005 195,139 Outturn 2006 242,681 Outturn 2007 204,834 Outturn 2008 197,040 Outturn 2009 180,789 Outturn 2010 192,402 Outturn 2011 200,119 Outturn 2012 189,404 Outturn 2013 187,406 Outturn 2014 192,988 Outturn 2015 196,537 Outturn 2016 204,888 Outturn 2017 217,894 Outturn 2018 218,066 Outturn 2019 215,079 Outturn 2020 188,264 Outturn 2021 185,054 Outturn 2022 202,888 Outturn 2023 191,567 Outturn 2024 186,104 Outturn 2025 184,481 Outturn Investment and productivity: what is observed, and what is modelled? +36.9%1996 Q1–2026 Q1United Kingdom · index (2023=100)Observed UK productivity. This is not a counterfactual estimate of the effect of EU exit.73.1 → 100.11996 Q1–2026 Q1How the estimates differ, and why observed growth cannot settle them.Read the chapter → Investment and productivity: what is observed, and what is modelled?Sources and data
ONS’s headline productivity measure and the one behind "the UK productivity puzzle" — the post-2008 slowdown in output-per-hour growth relative to its pre-2008 trend. Index basis, not a level in £, so only growth/ratios are meaningful, never a raw cross-country £ comparison from this series alone. Index rebased to 2023=100 in the 2025 Blue Book-aligned update; prior published index (base year 2019 or 2022 depending on vintage) is not on the same footing for absolute index values, though growth rates chain through.
Source dataset →Period index (2023=100) Status 1996 Q1 73.1 Outturn 1996 Q2 73.2 Outturn 1996 Q3 73.6 Outturn 1996 Q4 74.3 Outturn 1997 Q1 74.6 Outturn 1997 Q2 74.9 Outturn 1997 Q3 75.3 Outturn 1997 Q4 76.4 Outturn 1998 Q1 76.6 Outturn 1998 Q2 77.1 Outturn 1998 Q3 77 Outturn 1998 Q4 78 Outturn 1999 Q1 78 Outturn 1999 Q2 78 Outturn 1999 Q3 79.1 Outturn 1999 Q4 80.2 Outturn 2000 Q1 82.3 Outturn 2000 Q2 81.9 Outturn 2000 Q3 82.4 Outturn 2000 Q4 82.3 Outturn 2001 Q1 83.2 Outturn 2001 Q2 83 Outturn 2001 Q3 83.5 Outturn 2001 Q4 83.8 Outturn 2002 Q1 84.1 Outturn 2002 Q2 84.9 Outturn 2002 Q3 84.9 Outturn 2002 Q4 85.4 Outturn 2003 Q1 86 Outturn 2003 Q2 86.6 Outturn 2003 Q3 87.4 Outturn 2003 Q4 88.5 Outturn 2004 Q1 87.8 Outturn 2004 Q2 88.4 Outturn 2004 Q3 88.4 Outturn 2004 Q4 87.9 Outturn 2005 Q1 88.6 Outturn 2005 Q2 89.5 Outturn 2005 Q3 89.7 Outturn 2005 Q4 90.8 Outturn 2006 Q1 91 Outturn 2006 Q2 91.3 Outturn 2006 Q3 91.2 Outturn 2006 Q4 91.1 Outturn 2007 Q1 92.1 Outturn 2007 Q2 92.6 Outturn 2007 Q3 93.2 Outturn 2007 Q4 93.9 Outturn 2008 Q1 93.3 Outturn 2008 Q2 93.9 Outturn 2008 Q3 92.4 Outturn 2008 Q4 91 Outturn 2009 Q1 90.7 Outturn 2009 Q2 90.7 Outturn 2009 Q3 91.3 Outturn 2009 Q4 91.6 Outturn 2010 Q1 92.6 Outturn 2010 Q2 92.9 Outturn 2010 Q3 93 Outturn 2010 Q4 92.6 Outturn 2011 Q1 92.6 Outturn 2011 Q2 93.6 Outturn 2011 Q3 93.3 Outturn 2011 Q4 93.6 Outturn 2012 Q1 93.6 Outturn 2012 Q2 92.9 Outturn 2012 Q3 92.9 Outturn 2012 Q4 92.5 Outturn 2013 Q1 92.6 Outturn 2013 Q2 92.9 Outturn 2013 Q3 92.4 Outturn 2013 Q4 92.9 Outturn 2014 Q1 92.8 Outturn 2014 Q2 92.8 Outturn 2014 Q3 93.4 Outturn 2014 Q4 93.3 Outturn 2015 Q1 93.2 Outturn 2015 Q2 93.8 Outturn 2015 Q3 94 Outturn 2015 Q4 92.7 Outturn 2016 Q1 93.7 Outturn 2016 Q2 94.3 Outturn 2016 Q3 94.5 Outturn 2016 Q4 94.8 Outturn 2017 Q1 95.1 Outturn 2017 Q2 95.4 Outturn 2017 Q3 97 Outturn 2017 Q4 97.4 Outturn 2018 Q1 97 Outturn 2018 Q2 97.1 Outturn 2018 Q3 96.6 Outturn 2018 Q4 96.8 Outturn 2019 Q1 95.9 Outturn 2019 Q2 96.2 Outturn 2019 Q3 97.3 Outturn 2019 Q4 97.5 Outturn 2020 Q1 97.4 Outturn 2020 Q2 95.1 Outturn 2020 Q3 102.4 Outturn 2020 Q4 97.6 Outturn 2021 Q1 98.8 Outturn 2021 Q2 100.3 Outturn 2021 Q3 99.3 Outturn 2021 Q4 99.7 Outturn 2022 Q1 100.3 Outturn 2022 Q2 100.4 Outturn 2022 Q3 100.6 Outturn 2022 Q4 100.2 Outturn 2023 Q1 99.7 Outturn 2023 Q2 100.2 Outturn 2023 Q3 100.5 Outturn 2023 Q4 99.6 Outturn 2024 Q1 99.1 Outturn 2024 Q2 99.8 Outturn 2024 Q3 98.3 Outturn 2024 Q4 99.7 Outturn 2025 Q1 99.6 Outturn 2025 Q2 99.1 Outturn 2025 Q3 99.4 Outturn 2025 Q4 99.1 Outturn 2026 Q1 100.1 Outturn Migration: what changed once free movement ended?EU+ net migration turned negative (−42k in the year to December 2025); non-EU+ rose, then fell back.Composition versus total, and which decisions drove each.Read the chapter → Migration: what changed once free movement ended? Northern Ireland: what is different there?Access to both the UK and EU goods markets, a trade border in the Irish Sea, and EU rules without a vote.The Windsor Framework and the 2024 consent vote.Read the chapter → Northern Ireland: what is different there?
Evidence → choices → outcomes
What could improve it?
Less avoidable friction in UK–EU trade, with the autonomy each choice gives up stated openly.
These options link to their national assessment, including funding, delivery constraints and remaining uncertainties.
Assessed option · provisional
Cut EU trade friction with a scoped food-and-farm deal
Conclude the SPS agreement.
8/10 criteria scored
Coverage of the appraisal, not an impact score.
Delivery: Red
Whole-life costs incomplete
Evidence and delivery constraints
Observed trade friction does not identify the effect of a future agreement; scope and baseline need updating.
Define covered goods, alignment, oversight and border changes; secure agreement and business transition.
How we assessed these options
What would it take to improve this?
What can change within the present relationship?
The outcome we want: Less avoidable friction in UK–EU trade, with the autonomy each choice gives up stated openly.
The main constraint: Lower friction depends on a negotiated UK–EU agreement and implementing legislation, and each gain in access is traded against regulatory autonomy — a negotiation, legislation and consent constraint, with the remaining border processes falling hardest on small exporters.
Constraint type: legislation, public consent, coordination.
The options on the table
What is funded now, and the changes assessed against it — the current baseline and the alternatives, before the position today and the actions.
Provisional single-reviewer assessments from the 6 October 2026 review; not approved business cases, and not government policy.
Cut EU trade friction with a scoped food-and-farm dealDelivery RAG: Red
- Funded now
- Agreed in principle in May 2025; at September 2026 the FSA reported negotiations “at an advanced stage” after the July 2026 summit was postponed, with implementation planning assuming summer 2027 and legislation expected through an anticipated European Partnership Bill. Not yet an operating agreement.
- The change assessed
- Conclude the SPS agreement.
Range if completed: 11.0–17.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))
Alternatives already on record: 19 options listed under the points in the position today (11 without an action record), and 4 earlier options under other options compared. They have not been scored in the review.
The position today
Which quadrant a point sits in is our analytical judgement, not a statistical category. Each point says whether it is a measured fact, our synthesis or a risk.
What we can build on Strengths
There is a working treaty base to build on: the Trade and Cooperation Agreement, and a May 2025 Common Understanding committing both sides to negotiate an agri-food (SPS) agreement.
Measured factConfidence: High· TCA in force from 2021; Common Understanding 19 May 2025· United Kingdom and EU
Source: UK Government, Agreements reached between the UK and the EU (Trade and Cooperation Agreement, December 2020) (Agreement text); UK Government, UK–EU Summit key documentation (Common Understanding, 19 May 2025; Joint Statement, 17 December 2025) (Common Understanding, SPS section)
Options assessed against this point: Cut EU trade friction with a scoped food-and-farm deal (Red delivery RAG)
What government has committed to
Policy: Work towards a Common Sanitary and Phytosanitary (SPS) Area with dynamic alignment and “a short list of limited exceptions”; both sides aimed to conclude SPS, carbon-market linking and a youth experience scheme by the next summit.
- Who and when:
- Starmer government (to July 2026), 19 May 2025.
- Since 20 July 2026:
- Kept by the Burnham government. Reaffirmed in the Commons (10 September 2026) and with the Commission President (22 September 2026); the summit date is not set. Source: House of Commons, EU-UK Relationship, House of Commons, 10 September 2026 (Hansard) (Minister Hamish Falconer: “I am determined to get the SPS agreement done”).
- Source:
- Cabinet Office, UK–EU Summit: Common Understanding (19 May 2025) (Paragraphs 24 and 27–29)
Checked 4 October 2026. A commitment is not delivery.
Options (3)
ShortlistedReduce food-trade friction through a clearly scoped agreement
Builds on the treaty base to remove most certificates and checks on agri-food trade.
Who: Cabinet Office; Defra; FSA · Evidence: Observational analysis · Status: Announced proposal
Source: Food Standards Agency, An update to the Board on the Food Standards Agency’s SPS programme: September 2026 (Paragraphs 2.2 and 3.4)
Link the UK and EU carbon markets
A second agreement on the same base avoids carbon border charges on UK exports.
Who: DESNZ; Cabinet Office · Evidence: Untested proposal · Status: Announced proposal
Source: Cabinet Office, Joint statement on the Withdrawal Agreement Joint Committee and TCA Partnership Council meetings, 2 February 2026 (Statement text)
Mutual recognition of professional qualifications
The Common Understanding sets up dialogues on qualifications and business mobility, which could extend the base beyond goods.
Who: Cabinet Office; DBT · Evidence: Untested proposal · Status: Announced proposal
Source: Cabinet Office, UK–EU Summit: Common Understanding (19 May 2025) (Paragraph 46)
Services exports, mostly untouched by border checks, were +26% higher in volume in 2025 than in 2019.
Measured factConfidence: High· 2019 to 2025· United Kingdom
Source: Office for National Statistics, UK trade time series (MRET), chained volume measures (CDID IKBE (chained volume))
What government has committed to
Policy: Dialogues on business entry and stay and on recognition of professional qualifications; no negotiating commitment on services market access.
- Who and when:
- Starmer government (to July 2026), 19 May 2025.
- Since 20 July 2026:
- Not confirmed either way since the change of Prime Minister on 20 July 2026. No Burnham-era statement on services dialogues was found.
- Source:
- Cabinet Office, UK–EU Summit: Common Understanding (19 May 2025) (Paragraph 46)
Checked 4 October 2026. A commitment is not delivery.
Options (2)
Mutual recognition of professional qualifications and services access
Easier recognition and business mobility protect the services exports that grew while goods fell.
Who: Cabinet Office; DBT · Evidence: Untested proposal · Status: Announced proposal
Source: Cabinet Office, UK–EU Summit: Common Understanding (19 May 2025) (Paragraph 46)
A youth experience scheme and Erasmus+ association
Widens two-way labour mobility that services firms rely on.
Who: Home Office; Cabinet Office · Evidence: Untested proposal · Status: Announced proposal
Source: Cabinet Office, Joint statement on the Withdrawal Agreement Joint Committee and TCA Partnership Council meetings, 2 February 2026 (Statement text)
What is holding us back Weaknesses
Goods exports to the EU were −14% in volume between 2019 and 2025, against −8% to the rest of the world; the EU series has a recording break in January 2021.
Measured factConfidence: Moderate· 2019 to 2025· United Kingdom
Source: Office for National Statistics, UK trade time series (MRET), chained volume measures (CDIDs JIM8 and JIN3 (goods excluding precious metals))
Options assessed against this point: Cut EU trade friction with a scoped food-and-farm deal (Red delivery RAG)
What government has committed to
Legislation: A European Partnership Bill to implement the SPS, carbon-market and electricity agreements; the government estimates the food and drink deal “could add up to £5.1 billion a year” (its own estimate). Rejoining a customs union is ruled out.
- Who and when:
- Starmer government (to July 2026), 13 May 2026.
- Since 20 July 2026:
- Kept by the Burnham government. The Burnham government keeps the negotiation and the red lines; the Bill had not been introduced by 4 October 2026. Source: House of Lords, UK Automotive and Components Sector, House of Lords, 9 September 2026 (Hansard) (Lord Leong: “we are not joining the customs union”).
Checked 4 October 2026. A commitment is not delivery.
Options (3)
ShortlistedReduce food-trade friction through a clearly scoped agreement
Removing export health certificates and routine checks lowers the cost of selling agri-food to the EU.
Who: Cabinet Office; Defra; FSA · Evidence: Observational analysis · Status: Announced proposal
Source: LSE Centre for Economic Performance, UK trade in the wake of Brexit (CEP Discussion Paper 1847) (Introduction, PDF p.4)
Rejoin a customs union or the single market
Would remove tariff and rules-of-origin paperwork (a customs union alone leaves SPS and regulatory checks) and end an independent trade policy.
Who: UK Government; EU · Evidence: Modelled scenario · Status: External proposal
Source: LSE Centre for Economic Performance, UK trade in the wake of Brexit (CEP Discussion Paper 1847) (Introduction)
Accept current arrangements and focus on non-EU markets
Relies on other trade deals; goods exports to the rest of the world are also below 2019, so this does not close the EU gap.
Who: Department for Business and Trade · Evidence: Observational analysis · Status: Established
Source: Office for National Statistics, UK trade time series (MRET), chained volume measures (Goods exports by partner, volume)
The new rules cut the number of product-country varieties exported to the EU by about 30%, driven by the loss of low-value trade relationships — consistent with smaller exporters leaving smaller EU markets.
Measured factConfidence: Moderate· 2021 (published April 2022)· United Kingdom
Source: LSE Centre for Economic Performance, UK trade in the wake of Brexit (CEP Discussion Paper 1847) (Introduction, PDF p.4)
What government has committed to
Policy: Defra intends the SPS agreement to take effect in mid-2027 and to support businesses “of all sizes” to prepare.
- Who and when:
- Starmer government (to July 2026), 9 March 2026.
- Since 20 July 2026:
- Kept by the Burnham government. The guidance was updated under the Burnham government; the FSA reports that small firms have “little awareness” of the agreement. Source: Defra, SPS agreement: preparing your business (Change history: updates of 24–30 July 2026).
- Source:
- Defra, SPS agreement: preparing your business (Opening paragraphs)
Checked 4 October 2026. A commitment is not delivery.
Options (3)
ShortlistedMake the remaining border process usable for small exporters
Simpler guidance, templates and help aimed at small firms address the exits behind the fall in varieties.
Who: Defra; DBT; FSA · Evidence: Untested proposal · Status: Site-editorial action
Source: Food Standards Agency, An update to the Board on the Food Standards Agency’s SPS programme: September 2026 (Paragraph 4.7 (SME awareness))
Reduce food-trade friction through a clearly scoped agreement
Removing fixed per-consignment certificate costs helps small, low-value trade most.
Who: Cabinet Office; Defra · Evidence: Observational analysis · Status: Announced proposal
Source: LSE Centre for Economic Performance, UK trade in the wake of Brexit (CEP Discussion Paper 1847) (Introduction, PDF p.4)
Phase in the new rules with transition and sell-through periods
Gives small firms time to adapt rather than leave EU markets.
Who: Defra; FSA · Evidence: Untested proposal · Status: External proposal
Source: Food Standards Agency, An update to the Board on the Food Standards Agency’s SPS programme: September 2026 (Paragraph 4.4)
What could improve things Opportunities
A concluded SPS agreement would remove most export health certificates and routine checks on agri-food trade, and practical help could make the remaining processes usable for small firms.
Depends on: Negotiations conclude, implementing legislation passes, and the UK accepts dynamic alignment with EU SPS rules in scope.
Our synthesisConfidence: Moderate
Source: UK Government, UK–EU Summit package explainer (19 May 2025) (PDF p.1); Food Standards Agency, An update to the Board on the Food Standards Agency’s SPS programme: September 2026 (Paragraph 2.2)
Options assessed against this point: Cut EU trade friction with a scoped food-and-farm deal (Red delivery RAG)
What government has committed to
Policy: Conclude the SPS agreement, with implementation planned for summer 2027 and legislation expected through a European Partnership Bill.
- Who and when:
- Starmer government (to July 2026), 13 May 2026.
- Since 20 July 2026:
- Kept by the Burnham government. The FSA is preparing for implementation in summer 2027 (board paper, 15 September 2026). Source: House of Commons, EU-UK Relationship, House of Commons, 10 September 2026 (Hansard) (Minister Hamish Falconer on concluding the SPS agreement).
Checked 4 October 2026. A commitment is not delivery.
Options (3)
ShortlistedReduce food-trade friction through a clearly scoped agreement
Concluding the agreement realises the opportunity directly.
Who: Cabinet Office; Defra; FSA · Evidence: Observational analysis · Status: Announced proposal
Source: Food Standards Agency, An update to the Board on the Food Standards Agency’s SPS programme: September 2026 (Paragraphs 2.2 and 3.4)
Make the remaining border process usable for small exporters
Help with what remains lets small firms use the agreement.
Who: Defra; DBT · Evidence: Untested proposal · Status: Site-editorial action
Allow early access to products with EU authorisations
Smooths the switch for firms during implementation.
Who: FSA; Defra · Evidence: Untested proposal · Status: External proposal
Source: Food Standards Agency, An update to the Board on the Food Standards Agency’s SPS programme: September 2026 (Paragraphs 4.4 and 5.15)
What could make it worse Threats
The agreement is not yet concluded: the July 2026 summit was postponed after the change of government, exceptions such as gene editing were still being negotiated, and alignment obligations would limit future divergence.
Risk, not a certaintyConfidence: Moderate
Source: Food Standards Agency, An update to the Board on the Food Standards Agency’s SPS programme: September 2026 (Paragraph 2.2); UK in a Changing Europe, UK-EU Regulatory Divergence Tracker Q1 2026 (sixteenth edition) (PDF pp.9–10)
Options assessed against this point: Cut EU trade friction with a scoped food-and-farm deal (Red delivery RAG)
What government has committed to
Policy: Conclude the SPS negotiations “as soon as possible” and hold the postponed EU–UK summit later in 2026; no date set.
- Who and when:
- Burnham government (from 20 July 2026), 22 September 2026.
- Since 20 July 2026:
- Made by the current government. The July 2026 summit was postponed after the change of government (FSA paper, paragraph 2.2); the European Partnership Bill had not been introduced by 4 October 2026.
- Source:
- Prime Minister’s Office, PM meeting with President of the European Commission Ursula von der Leyen: 22 September 2026 (Readout: “the next EU-UK summit later in the year”)
Checked 4 October 2026. A commitment is not delivery.
Options (2)
ShortlistedReduce food-trade friction through a clearly scoped agreement
Publishing the scope and exceptions with the deal reduces uncertainty about what alignment covers.
Who: Cabinet Office; Defra · Evidence: Observational analysis · Status: Announced proposal
Source: UK in a Changing Europe, UK-EU Regulatory Divergence Tracker Q1 2026 (sixteenth edition) (PDF pp.9–10)
Give Parliament a say before EU law is applied
The European Partnership Bill’s scrutiny process addresses the consent risk of dynamic alignment.
Who: Parliament · Evidence: Untested proposal · Status: Announced proposal
Source: Prime Minister’s Office, The King’s Speech 2026: background briefing notes (13 May 2026) (p.17)
Barriers are rising outside the EU too: after US tariffs from April 2025, UK goods exports to the United States fell 10.2% in 2025 (current prices), against 1.8% for all UK goods exports, and in April 2026 most UK goods still faced a 10% US tariff while the May 2025 deal was only partly implemented.
Risk, not a certaintyConfidence: Moderate· 2024 to 2025; tariffs as at April 2026· United Kingdom
Source: Office for National Statistics, UK trade time series (MRET): goods exports to the United States (J9C5) and to all countries (BOKG) (CDIDs J9C5 and BOKG (annual, current prices)); House of Commons Library, US trade tariffs (Research Briefing CBP-10240) (Summary (archived copy, 22 May 2026))
What government has committed to
Policy: General terms of the US–UK Economic Prosperity Deal: up to 100,000 UK cars a year at a 10% tariff, a route to removing the 25% steel and aluminium tariffs, and tariff-free pharmaceuticals; only partly implemented by April 2026.
- Who and when:
- Starmer government (to July 2026), 8 May 2025.
- Since 20 July 2026:
- Not confirmed either way since the change of Prime Minister on 20 July 2026. No Burnham-government statement on the deal was found; the US legal basis for the 10% tariff changed in February 2026 (Commons Library, April 2026).
- Source:
- Department for Business and Trade and Prime Minister’s Office, US–UK Economic Prosperity Deal (EPD): general terms (General terms document)
Checked 4 October 2026. A commitment is not delivery.
Options (3)
Complete the deal’s unimplemented terms, starting with steel and aluminium
Removes the 25% tariff on the sector still most exposed.
Who: Department for Business and Trade · Evidence: Untested proposal · Status: Announced proposal
Source: House of Commons Library, US trade tariffs (Research Briefing CBP-10240) (Summary (archived copy, 22 May 2026))
Reduce friction with the EU, the larger market, through the SPS agreement
Lowers costs on trade the UK can influence through a negotiation already under way.
Who: Cabinet Office and Defra with the European Commission · Evidence: Observational analysis · Status: Announced proposal
Source: Food Standards Agency, An update to the Board on the Food Standards Agency’s SPS programme: September 2026 (Paragraph 2.2)
Diversify exports through other trade agreements and export support
Spreads exposure so a single market’s tariffs reach a smaller share of sales.
Who: Department for Business and Trade · Evidence: Untested proposal · Status: External proposal
The actions worth examining
Our shortlist for this page. Research quality, policy status, cost and funding are judged separately; none of these is government policy unless its status says so.Our shortlist. None is government policy unless its status says so.
Action 1A29Policy status: announced proposal
Reduce food-trade friction through a clearly scoped agreement
A UK–EU SPS agreement with dynamic alignment would remove most export health certificates and routine border checks, in exchange for following EU rules in scope.
The thread: issue, evidence, action
Assessment (draft, 6 October review)
This action: Cut EU trade friction with a scoped food-and-farm deal
Delivery RAG: RedGate: pending
Range if completed: 11.0–17.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))
National plan: Growth and prosperity list
- Who decides:
- UK government (Defra, Cabinet Office) and the European Commission; Parliament for implementing legislation; devolved administrations (UK)
- Evidence:
- Observational analysis. Strong evidence on the costs of the frictions an agreement would remove; the gains from this agreement are government estimates of administrative savings, not evaluated trade effects.
- Expected effect:
- Direction plausible; size not established.
- Cost and funding
Not yet costed
Funding: Not a direct public-spending programme
Why it is shortlisted here: The largest friction the current relationship can realistically remove, and the one under negotiation now.
What it takes
The problem
Since 2021, animal and plant products traded with the EU face certificates and checks that add cost and have pushed some smaller exporters out.
Who is affected, and where
Agri-food exporters and importers in Great Britain, consumers, and Northern Ireland traders. Territory: UK. Food and agriculture are partly devolved; the Scottish and Welsh governments and the Northern Ireland Executive have roles in implementation, not assessed here.
Policy status
Announced by government, not yet in place. Agreed in principle in May 2025; at September 2026 the FSA reported negotiations “at an advanced stage” after the July 2026 summit was postponed, with implementation planning assuming summer 2027 and legislation expected through an anticipated European Partnership Bill. Not yet an operating agreement.
The evidence
- What the research found:
- CEP research found the TCA cut the number of product-country varieties exported to the EU by about 30%, driven by low-value trade relationships. The government says the agreement would remove export health certificates (up to £200 a consignment) and routine checks on goods such as dairy, fish and meat, now subject to 100% paperwork and up to 30% physical checks.
- Evaluated on:
- UK–EU goods trade after the Trade and Cooperation Agreement; United Kingdom and EU, 2021 onwards
- Transfer to this case:
- Administrative savings per consignment do not translate directly into trade growth or GDP.
- Our recommendation (separate from the research):
- Track certificates, border delays, rejected consignments and exporter numbers before and after; publish what alignment requires firms and regulators to change.
- Strongest counter-evidence:
- Dynamic alignment means taking EU rules the UK does not vote on, limiting divergence in areas such as gene editing; enforcement obligations follow; gains differ sharply by sector and firm size.
Effects on record
- Cost and time of agri-food trade with the EU: Direction plausible; size not established. plausible spillover, limited confidence; Great Britain and EU. Savings per consignment are government statements, not evaluated trade effects; the agreement is not yet concluded.
- UK freedom to set its own food and plant rules: A cost or harm; size not established. plausible spillover, moderate confidence; United Kingdom. Whether this is a cost is a value judgement; the trade-off is real.
Cost and funding
Cost completeness: Not yet costed. Funding: Not a direct public-spending programme.
- Public administration, business compliance and transition for an SPS agreement (administration; paid by central government, employers): Not yet costed. No published estimate of implementation or business alignment costs. A GDP estimate is not tax receipts.
- FSA SPS programme funding from HM Treasury, 2026–27 (amount not published): amount not established, 2026–27 to 2026–27 — not committed (allocated to this scope). Covers FSA readiness only, not Defra, port health or business costs.
- Who pays:
- Government (Defra, FSA, port health authorities) for implementation; businesses for changes to processes, labelling and IT to align with EU rules.
- Financing proposed:
- The FSA secured 2026–27 funding from HM Treasury for its SPS programme (amount not published); funding for later years is under consideration. A GDP estimate is not tax receipts.
- Gap remaining:
- Unknown: neither total implementation cost nor business compliance cost has been published.
What delivery needs
- Skills:
- Regulatory and veterinary staff.
- Operational capacity:
- FSA, Defra and port health readiness.
- Infrastructure:
- Border control post use changes.
- Permissions:
- EU agreement.
- Law:
- Implementing legislation (an anticipated European Partnership Bill).
- Public consent:
- Parliamentary approval; acceptance of dynamic alignment.
First step and stages
First step: Publish the final scope, the exceptions and the affected product groups once negotiations conclude. (owner: Defra and the Cabinet Office)
- Conclude negotiations — UK government and European Commission (proposed stage, not an official timetable)
- Pass implementing legislation — Parliament (proposed stage, not an official timetable)
- Operate the agreement (FSA planning assumption: summer 2027, not an agreed date) — Defra, FSA, port health authorities
Depends on: Conclusion of negotiations; Implementing legislation; A30 for remaining border processes
Trade-offs
- Who gains and who loses:
- Food exporters, especially smaller firms, gain most; firms that wanted to diverge from EU rules lose flexibility.
- What else the money or effort could do:
- Negotiating capital spent here is not available for other EU issues.
- Strongest counterargument:
- Regulatory autonomy has value, including for new technologies; non-EU trade deals may be constrained.
- Risks:
- Delay; disputes over exceptions; benefits concentrated in a few sectors.
How we would judge it
- Baseline:
- Goods exports to the EU 14% lower in volume in 2025 than in 2019 (ONS).
- Leading indicator:
- Export health certificates issued; border delays.
- Outcome:
- Rejected consignments, exporter numbers and agri-food trade with the EU against comparable trade.
- Continue, adapt or stop:
- Review if certificates and checks are not removed within a year of operation.
Earlier option on this page
This card replaces the option “A UK–EU agreement on food and plant checks (SPS)” (announced: Agreed in principle at the May 2025 summit; the December 2025 joint statement aimed to finish negotiations by the next summit.). Its evidence: The government says the deal would remove export health certificates costing up to £200 a consignment and end routine checks on products such as dairy, fish and meat, which currently face 100% document checks and up to 30% physical checks. Those are administrative savings stated by the government, not an evaluation of trade effects. UK Government, UK–EU Summit key documentation (Common Understanding, 19 May 2025; Joint Statement, 17 December 2025) · UK Government, UK–EU Summit package explainer (19 May 2025)
Sources
- UK in a Changing Europe, UK-EU Regulatory Divergence Tracker Q1 2026 (sixteenth edition), PDF pp.9–10 (2026-04; relevant passages checked)
- Food Standards Agency, An update to the Board on the Food Standards Agency’s SPS programme: September 2026, Paragraphs 2.2, 3.4, 5.16 (2026-09-15; relevant passages checked)
- UK Government, UK–EU Summit package explainer (19 May 2025), PDF p.1 (2025-05-19; full text checked)
- LSE Centre for Economic Performance, UK trade in the wake of Brexit (CEP Discussion Paper 1847), Introduction, PDF p.4 (2022-04; relevant passages checked)
- UK in a Changing Europe, UK-EU Regulatory Divergence Tracker Q1 2026 (sixteenth edition), PDF pp.9–10 (2026-04; relevant passages checked)
Source published April 2026 (UKICE); September 2026 (FSA); April 2022 (CEP); evidence reviewed 2026-10-04. Reconsider if: Negotiations conclude or stall; The European Partnership Bill is published; A new UKICE divergence tracker.
Action 2A30Policy status: site-editorial action
Make the remaining border process usable for small exporters
Map one costly exporter journey, remove duplication that can lawfully be removed, and test joined-up guidance and digital documents with a cohort of small exporters.
The thread: issue, evidence, action
- Issue Weakness: The new rules cut the number of product-country varieties exported to the EU by about 30%, driven by the loss of low-value trade relationships — consistent with smaller exporters leaving smaller EU markets. Also: weakness
- Evidence Goods exports to the EU, volume change since 2019
- Action A30, this action
Assessment (draft, 6 October review)
Not assessed in the 6 October review; this action stays in the topic plan with its own evidence.
- Who decides:
- Department for Business and Trade, HMRC and border authorities, with devolved business-support bodies (UK)
- Evidence:
- Untested proposal. The problem is evidenced by trade research; the remedy has not been evaluated and its unit cost is unknown.
- Expected effect:
- Direction plausible; size not established.
- Cost and funding
Not yet costed
Funding: Not yet costed / funding not identified
Why it is shortlisted here: Some checks and paperwork will remain whatever is agreed, and small exporters bear them most.
What it takes
The problem
Fixed costs of exporting to the EU rose in 2021 and the loss of low-value export relationships suggests smaller exporters were hit hardest; rules will remain even with an SPS agreement.
Who is affected, and where
Small and medium-sized UK exporters to the EU. Territory: UK. Trade policy is reserved; business support is partly devolved, so pilots in Scotland, Wales and Northern Ireland need devolved partners.
Policy status
UK Facts proposal. A UK Facts operating proposal; existing export support services were not audited in this review.
The evidence
- What the research found:
- CEP research found a large, persistent drop in the number of UK export relationships with the EU driven by low-value trade, and conjectures that higher fixed costs pushed small exporters out of small EU markets.
- Evaluated on:
- UK exporters to the EU, 2021 onwards; United Kingdom
- Our recommendation (separate from the research):
- Pilot with a defined SME cohort, measure compliance time and cost, and expand only if exporters keep trading.
- Strongest counter-evidence:
- Process support cannot remove legal barriers; firms that stopped exporting may not return; subsidised support can pay for what would have happened anyway.
Cost and funding
Cost completeness: Not yet costed. Funding: Not yet costed / funding not identified.
- Digital integration, support staff and firms’ compliance time for an SME pilot (administration; paid by central government, employers): Not yet costed. Existing trade-support allocations were not audited in this review.
- Who pays:
- Department for Business and Trade and HMRC (digital integration and support staff); firms (time spent on compliance).
- Financing proposed:
- Check existing trade-support allocations first; none identified here.
- Gap remaining:
- Unknown.
What delivery needs
- Skills:
- Customs and SPS specialists.
- Operational capacity:
- Business support advisers.
- Infrastructure:
- Interoperable digital documentation.
- Permissions:
- EU acceptance of any digital documents.
- Law:
- None for guidance; possibly secondary legislation for documents.
- Public consent:
- Firms willing to take part.
First step and stages
First step: Map one costly exporter journey and identify duplication that can lawfully be removed. (owner: Department for Business and Trade with HMRC)
- Map the journey and pick an SME cohort — Department for Business and Trade (proposed stage, not an official timetable)
- Pilot joined-up guidance and digital documents — DBT, HMRC, devolved partners (proposed stage, not an official timetable)
- Evaluate and expand or stop — Independent evaluator (proposed stage, not an official timetable)
Depends on: A29: which SPS checks remain; Border systems
Trade-offs
- Who gains and who loses:
- Small exporters gain most; firms without digital capacity may not.
- What else the money or effort could do:
- Support staff and IT budgets not used elsewhere.
- Strongest counterargument:
- Large firms drive aggregate exports; small-exporter support may not move national trade figures.
- Risks:
- Digital exclusion, duplicated systems and deadweight.
How we would judge it
- Baseline:
- About 30% fewer product-country export varieties to the EU after the TCA (CEP estimate).
- Leading indicator:
- Compliance time and cost for the pilot cohort.
- Outcome:
- Sustained exporter participation compared with similar firms.
- Continue, adapt or stop:
- Stop if pilot firms do not export more than a comparison group after a year.
Sources
- LSE Centre for Economic Performance, UK trade in the wake of Brexit (CEP Discussion Paper 1847), Introduction, PDF p.4 (2022-04; relevant passages checked)
- UK in a Changing Europe, UK-EU Regulatory Divergence Tracker Q1 2026 (sixteenth edition), PDF p.4 (2026-04; relevant passages checked)
- LSE Centre for Economic Performance, UK trade in the wake of Brexit (CEP Discussion Paper 1847), Abstract (2022-04; relevant passages checked)
Source published April 2022 (CEP); April 2026 (UKICE); evidence reviewed 2026-10-04. Reconsider if: An SPS agreement changes the remaining checks; Official data on exporter numbers by size.
How the options are assessed
One shared record per option — the same one the national plan reads. Delivery RAG, gate and list membership are separate judgements.
Provisional single-reviewer assessments from the 6 October 2026 review; not approved business cases, and not government policy.
A29Delivery RAG: RedGate: pending
Cut EU trade friction with a scoped food-and-farm deal
Existing action A29, assessed at the same scope.
Provisional single-reviewer assessment; not an approved business case.
- Who and where
- Agri-food exporters and importers in Great Britain, consumers, and Northern Ireland traders. (from the action record) Jurisdiction: UK.
- Result so far
- Range if completed: 11.0–17.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))
- Funded now (baseline)
- Agreed in principle in May 2025; at September 2026 the FSA reported negotiations “at an advanced stage” after the July 2026 summit was postponed, with implementation planning assuming summer 2027 and legislation expected through an anticipated European Partnership Bill. Not yet an operating agreement. (from the action record)
- The change assessed (marginal)
- Conclude the SPS agreement. (from the superseded 4 October selection table)
- Domain home: Brexit
- In the national plan: Growth and prosperity list
What the evidence supports—and the next decision
Reduced food and farm border friction is narrower than reversing the economy-wide effects of Brexit.
Codex — AI-assisted analytical follow-up · 8 October 2026. Proposed appraisal design; the attributed scores below are unchanged. No funding or delivery agreement is implied.
- Define the change
- Appraise the actual SPS agreement and its implementation requirements against current border procedures, separately for affected products and businesses.
- Test whether it works
- Certification cost, rejected consignments, delays and trade in affected goods; distinguish new trade from diversion and changes in demand.
- Establish the cost
- Public implementation and inspection, business adjustment, ongoing compliance and distribution across firms. Use the agreed legal text before a final estimate.
- Protect against harm
- Retain food safety and biosecurity. Do not transfer an economy-wide Brexit estimate to this agreement.
Read with the outcome evidence and sources in the full assessment. Monitoring proposals are not existing baseline measurements. A numerical benefit or cost score needs evidence for the defined increment, not just the scale of the problem.
Full assessment of Cut EU trade friction with a scoped food-and-farm deal: ten criteria, scenarios, delivery, costs and monitoring
The ten criteria (0–3)
Each criterion is scored 0 to 3 by the reviewer. “Not yet assessed” means unknown: it is never counted as zero.
Scale and severity (Sc)2 of 3 — Serious harm to a defined group or widespread moderate harm
Reviewer’s reason: Provisional problem-importance judgement from linked site pages; not the scale of achievable benefit.
Increment beyond baseline (Ad)2 of 3 — Specific material change to existing delivery
Reviewer’s reason: Define covered goods, alignment, oversight and border changes; secure agreement and business transition. A missing rating requires a defined marginal change.
Confidence in the proposed action (Ev)1 of 3 — Indirect, mixed, modelled or weak causal support
Reviewer’s reason: Observed trade friction does not identify the effect of a future agreement; scope and baseline need updating.
Expected incremental benefit (Bn)Not yet assessed
Reviewer’s reason: Unknown unless a reasonably defined target-population benefit can be judged; no bonus merely for spanning domains.
Residual harms (Hm)1 of 3 — Material harm/unresolved mitigation
Reviewer’s reason: External agreement required; regulatory autonomy and uneven sector impacts.
Incremental affordability (Co)Not yet assessed
Reviewer’s reason: Public implementation, business compliance, adjustment and distributional costs under alternative agreements.
Delivery capacity (Ca)1 of 3 — Binding scarce resource
Reviewer’s reason: Define covered goods, alignment, oversight and border changes; secure agreement and business transition.
Distribution (Fa)2 of 3 — Mixed or broadly neutral with safeguards
Reviewer’s reason: Provisional distribution judgement for the stated target; verify who pays, who gains and excluded groups.
Meaningful first outcome (Ti)1 of 3 — More than three but less than ten years
Reviewer’s reason: First meaningful outcome, not announcement: Border time/cost, trade and consumer prices, with external shocks separated.
Readiness (Rd)1 of 3 — Legislation/external agreement or major enabling work
Reviewer’s reason: UK government and EU counterparts; relevant devolved authorities; Negotiation and scenario appraisal
Four weightings
Normalised as 10 × weighted sum ÷ sum of weights, on a 0–30 scale. Where a criterion is not yet assessed, the range is the lowest and highest result if it were later scored 0 or 3 — not a score, a confidence interval or a rank.
- Equal weights: Range if completed: 11.0–17.0 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
- Evidence doubled: Range if completed: 10.9–16.4 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
- Scale doubled: Range if completed: 11.8–17.3 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
- Cost ignored (the funding gate still applies): Range if completed: 12.2–15.6 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
Funding gate: Not passed — the cost is not yet assessed or no allocation is committed for this scope. Ignoring cost in a weighting never removes the gate.
Delivery RAG and gate
Delivery RAG shown: RedReview’s claim: Red. Best the recorded evidence allows: Red.
Review’s reason: External agreement required; regulatory autonomy and uneven sector impacts.
Why it is not Green yet
- Delivery obstacle: External agreement required; regulatory autonomy and uneven sector impacts..
- Scope (population, place and increment) not verified against the delivery baseline.
- No verified owner with the powers in place.
- Delivery capacity not verified.
- Lifetime incremental costs not complete.
- No credible funding (a committed allocation for the scope).
- Safeguards not specified.
- Monitoring lacks a metric, a data source or a baseline.
Green needs verified scope, a verified owner with the powers, verified capacity, complete lifetime costs with credible funding, specified safeguards and monitoring with a metric, source and baseline. Amber means appraisal gaps remain; Red means a material delivery obstacle. Red does not mean unimportant.
Gate: Pending — appraisal incomplete (review label: “Pending: incomplete appraisal”).
Why: Scores incomplete; Funding gate not passed (cost unknown or no credible funding).
The gate is separate from national list membership: being listed does not make an option eligible, and an eligible option need not be listed.
Cost and funding
Lifetime costing: Not established. Review: “Full incremental costing not established in reviewed material”.
- Public administration, business compliance and transition for an SPS agreement (not costed; C-A29-IMPLEMENTATION)
Still to cost: Public implementation, business compliance, adjustment and distributional costs under alternative agreements.
Funding status: not a spending proposal.
Owner, powers and capacity
Proposed owner: UK government and EU counterparts; relevant devolved authorities (proposed, unverified).
Powers: needs legislation or external agreement. Capacity: binding constraint.
Powers and capacity read from the review’s Rd and Ca anchors; no proposed owner has agreed to act (the review: “Proposed owners have not agreed to act”).
- England:
- UK government (Defra, Cabinet Office) and the European Commission; Parliament for implementing legislation; devolved administrations (action record)
- Scotland:
- UK government (Defra, Cabinet Office) and the European Commission; Parliament for implementing legislation; devolved administrations (action record)
- Wales:
- UK government (Defra, Cabinet Office) and the European Commission; Parliament for implementing legislation; devolved administrations (action record)
- Northern Ireland:
- UK government (Defra, Cabinet Office) and the European Commission; Parliament for implementing legislation; devolved administrations (action record)
Food and agriculture are partly devolved; the Scottish and Welsh governments and the Northern Ireland Executive have roles in implementation, not assessed here.
Dependencies, safeguards and risks
Depends on: None recorded.
Safeguards
None specified yet.
Risks and residual harms: External agreement required; regulatory autonomy and uneven sector impacts.
Monitoring and measured results
Metric: Border time/cost, trade and consumer prices, with external shocks separated.
Data source: Not yet named. Baseline: Not yet established.
Measures already on the domain page
- Goods exports to the EU, volume change since 2019: latest −14% (2025); baseline not published (United Kingdom).
A page measure is not necessarily the review’s metric; linking the two is an editorial decision still to be made.
Evidence for the outcome
Outcome: Border time/cost, trade and consumer prices, with external shocks separated.
Observed trade friction does not identify the effect of a future agreement; scope and baseline need updating.
Effect records for this action
- Cost and time of agri-food trade with the EU: size not established (plausible spillover, limited confidence; Great Britain and EU)
- UK freedom to set its own food and plant rules: size not established (plausible spillover, moderate confidence; United Kingdom)
SWOT points it addresses
- Goods exports to the EU were −14% in volume between 2019 and 2025, against −8% to the rest of the world; the EU series has a recording break in January 2021.
- There is a working treaty base to build on: the Trade and Cooperation Agreement, and a May 2025 Common Understanding committing both sides to negotiate an agri-food (SPS) agreement.
- A concluded SPS agreement would remove most export health certificates and routine checks on agri-food trade, and practical help could make the remaining processes usable for small firms.
- The agreement is not yet concluded: the July 2026 summit was postponed after the change of government, exceptions such as gene editing were still being negotiated, and alignment obligations would limit future divergence.
Review record
Assessment version: working-review-2026-10-06 (A29@working-review-2026-10-06).
Reviewer: Author of the review blueprint (single reviewer, not named in uk-facts-complete-plan.json). Reviewed: 6 October 2026.
Scored in the working review of 6 October 2026 on the shared ten-criterion scale (one reviewer); not independently calibrated.
First 90 days (review): Produce a signed scope and current-delivery baseline; Define covered goods, alignment, oversight and border changes; secure agreement and business transition. Obtain incremental costs and an accountable decision before expansion.
Decision route: Negotiation and scenario appraisal
An earlier assessment exists on the 4 October 2026 selection table (nine H/M/L bands; superseded 7 October 2026). Its bands are kept, not converted into these scores.
An editorial screening framework by one reviewer, not a formal appraisal or business case. Proposed owners have not agreed to act.
Decision briefs
The leading option set out as a decision someone could take: who decides, who benefits, the best evidence, cost and funding, and the main trade-off. The full research record is one click away.
Decision briefPublic-policy proposalReviewed 2026-10-04
Finish the UK–EU food and plant health deal — and set the baseline to measure it before it starts
The thread: issue, evidence, action
- Issue Weakness: Goods exports to the EU were −14% in volume between 2019 and 2025, against −8% to the rest of the world; the EU series has a recording break in January 2021. Also: threat, opportunity, strength
- Evidence Goods exports to the EU, volume change since 2019
- Action Reduce food-trade friction through a clearly scoped agreement
- Decision required
- The UK government concludes the SPS agreement, publishes its final scope and exceptions, legislates through the planned European Partnership Bill and, before it operates (planned summer 2027), publishes a baseline of certificates, checks, rejected consignments and exporter numbers so the effect can be measured.
- Who and where
- Agri-food exporters and importers in Great Britain, consumers, and Northern Ireland traders. Applies in: UK.
- Accountable body
- UK government (Defra and the Cabinet Office), with the European Commission
- Intervention
- Align UK sanitary and phytosanitary rules with the EU’s in scope, in exchange for removing certificates and routine border checks.
- Best evidence, and where it applies
- The government says the agreement would remove export health certificates (saving up to £200 a consignment) and routine checks on goods now facing 100% paperwork and up to 30% physical checks; LSE research found UK exports to the EU lost about 30% of product-country varieties after the TCA, mostly low-value trade relationships.Studied in: UK exports to the EU and the rest of the world (2021 against earlier years).How closely the comparison transfers to this decision: Switzerland and the European Union — partial.
- Extra cost of this change
- Capital: none identified in the brief.Recurring: none identified in the brief.One-off or mixed: Public administration, business compliance and transition — Not yet costed; Independent evaluation with pre-implementation baseline — not yet established.
- Funding
- Mainly a legal or regulatory change: administration costs still need a budget.Committed to this change: none.Possible source, not an award: none identified.Unfunded: Neither total implementation cost nor business compliance cost has been published; the FSA’s one-year readiness funding covers only the FSA.
- Savings and wider benefits
- Not yet specified: no cashable saving or avoided cost has been costed for this change. Expected outcomes are listed one by one in the research appendix and are never added together or counted as money available.
- First 90-day step
- Publication of the final scope, exceptions and affected product groups, with a baseline dataset for the evaluationThe proposed first milestone; a 90-day date is not yet specified. Owner: Defra and the Cabinet Office. Proposed by UK Facts, not an official deadline.
- Twelve-month milestone
- Not yet specified.Time to a first useful result: First operational data a year after implementation (planned summer 2027).
- Outcome, and when to scale or stop
- Measure: Certificates and checks removed in practice; border waiting times.Scale if: Certificates and routine checks are removed and small-exporter numbers recover relative to the comparison.Stop if: Not a stop decision: if certificates and checks are not removed within a year of operation, review the implementation with the EU.
- Main trade-off
- Removing certificates and checks requires following EU food and plant rules in scope without a vote on them, limiting UK divergence (for example in gene editing).
- Source and review date
- UK trade in the wake of Brexit (CEP Discussion Paper 1847) (2022); UK–EU Summit package explainer (19 May 2025) (19 May 2025). Reviewed 2026-10-04.
An editorial proposal by UK Facts for discussion, not government policy. Records: A29 · effects E-A29-FRICTION, E-A29-AUTONOMY · costs C-A29-IMPLEMENTATION
Research appendix: study design, effect sizes and limits, alternatives, full costing, international comparisons and how we would know
1.The change, in plain words
Finish the UK–EU food and plant health deal — and set the baseline to measure it before it starts
2.The decision requested
- Decision
- Conclude the agreement and publish the final scope, exceptions and affected product groups; legislate; and commission an evaluation with a pre-implementation baseline and a comparison (agri-food trade not covered by the agreement, or trade with non-EU partners).
- Accountable institution
- UK government (Defra and the Cabinet Office), with the European Commission
- Geography
- UK
- Powers
- Treaty-making prerogative, implemented through the anticipated European Partnership Bill and secondary legislation; devolved administrations for devolved food and agriculture law.
- Delivery partners
- European Commission; Food Standards Agency and Food Standards Scotland; Animal and Plant Health Agency; Port health authorities; Devolved governments; Trade bodies
3.Who it is for, and what changes beyond today
- Target population
- Agri-food exporters and importers in Great Britain, consumers, and Northern Ireland traders.
- Eligibility
- Animal and plant products in the agreement’s final scope (for example dairy, fish, eggs and red meat exported to the EU).
- Scale
- All GB–EU agri-food trade in scope.
- Baseline
- At September 2026 the July summit had been postponed; negotiations were “at an advanced stage”, with implementation planned for summer 2027. GB goods exports to the EU were 14% lower in volume in 2025 than in 2019 (ONS), a change with several causes, not only Brexit. About 140,000 export health certificates were signed in January–July 2021 alone.
Source: Food Standards Agency, An update to the Board on the Food Standards Agency’s SPS programme: September 2026 (board paper) (Paragraphs 2.2, 5.16); Office for National Statistics, UK trade time series (MRET), chained volume measures (Goods exports to the EU, chained volume); National Audit Office, The UK border: post UK–EU transition period (HC 736, Session 2021–22) (Paragraph 2.15)
- Change beyond existing law or funding
- The agreement is government policy under negotiation. What this brief adds is the evaluation design: a published baseline and comparison set before operation, so that savings per consignment can be distinguished from trade growth and from other causes.
4.How it would work
Do: Align UK sanitary and phytosanitary rules with the EU’s in scope, in exchange for removing certificates and routine border checks Changing: so that the fixed cost and delay of each consignment fall, especially for small, low-value shipments
Lower cost and time of agri-food trade with the EU
Hypothesis to testEffect record E-A29-FRICTION
Savings per consignment are government statements, not evaluated trade effects; the agreement is not yet concluded.
Less UK freedom to set its own food and plant rules
Hypothesis to testEffect record E-A29-AUTONOMY
Whether this is a cost is a value judgement; the trade-off is real.
Outcomes are kept separate and never added into one impact figure.
5.Best evidence
UK trade in the wake of Brexit (CEP Discussion Paper 1847)
- Author or institution:
- Centre for Economic Performance, LSE
- Published:
- 2022
- Evaluation period:
- 2021 against earlier years
- Design:
- Observational analysis of product-level trade data
- Sample or population:
- UK exports to the EU and the rest of the world
- Effect and uncertainty:
- About a 30% fall in product-country export varieties to the EU after the TCA, driven by low-value trade relationships; conjectures higher fixed costs pushed small exporters out.
- Limits:
- Observational; covers all goods, not only SPS goods; early period.
Where: Introduction; PDF p.4. Affiliation is provenance, not proof of quality.
UK–EU Summit package explainer (19 May 2025)
- Author or institution:
- UK government (Cabinet Office)
- Published:
- 19 May 2025
- Evaluation period:
- Not an evaluation
- Design:
- Government statement of intended effects
- Sample or population:
- GB–EU agri-food trade
- Effect and uncertainty:
- Removal of export health certificates, saving up to £200 a consignment; removal of routine checks on dairy, fish, eggs and red meat (now 100% paperwork, up to 30% physical).
- Limits:
- Government’s own claims of savings, not measured outcomes.
Where: SPS section. Affiliation is provenance, not proof of quality.
6.Alternatives, counter-evidence and who loses
- Closest feasible alternative
- A narrower equivalence-based deal (as Switzerland’s veterinary agreement was originally built) that keeps more UK rule-making but removes fewer checks.
- Strongest counter-evidence
- Dynamic alignment means taking EU rules the UK does not vote on; enforcement obligations follow; gains differ sharply by sector and firm size.
Source: UK in a Changing Europe, UK-EU Regulatory Divergence Tracker Q1 2026 (sixteenth edition) (PDF pp.9–10)
- Distributional effects
- Food exporters, especially smaller firms, gain most; firms wanting to diverge from EU rules lose flexibility; importers and consumers may see lower costs for EU food.
- Main downside
- Benefits may be concentrated in a few sectors while the alignment obligation covers all goods in scope.
| Option | Who is reached | Evidence | Likely outcome and timing | Cost and funding | Main trade-off |
|---|---|---|---|---|---|
| The proposalConclude the SPS agreement with dynamic alignment; baseline and evaluate it | GB agri-food exporters and importers | Government statements; CEP trade analysis | From summer 2027 if concluded | Implementation not costed; FSA readiness funded for 2026–27 only | Rule-taking in scope |
| Current policyCurrent position: certificates and checks continue while negotiations go on | Same | NAO on post-2021 border costs | No change | Ongoing costs to firms | Small exporters remain priced out of small markets |
| AlternativeA narrower equivalence deal covering fewer products | Fewer exporters | Swiss arrangement (no trade evaluation) | Uncertain; needs EU agreement | Not costed | Fewer checks removed |
The options compared, including current policy
The proposal
Conclude the SPS agreement with dynamic alignment; baseline and evaluate it
- Who is reached
- GB agri-food exporters and importers
- Evidence
- Government statements; CEP trade analysis
- Likely outcome and timing
- From summer 2027 if concluded
- Cost and funding
- Implementation not costed; FSA readiness funded for 2026–27 only
- Main trade-off
- Rule-taking in scope
Current policy
Current position: certificates and checks continue while negotiations go on
- Who is reached
- Same
- Evidence
- NAO on post-2021 border costs
- Likely outcome and timing
- No change
- Cost and funding
- Ongoing costs to firms
- Main trade-off
- Small exporters remain priced out of small markets
Alternative
A narrower equivalence deal covering fewer products
- Who is reached
- Fewer exporters
- Evidence
- Swiss arrangement (no trade evaluation)
- Likely outcome and timing
- Uncertain; needs EU agreement
- Cost and funding
- Not costed
- Main trade-off
- Fewer checks removed
7.What other countries or the devolved nations show
Country lesson · Switzerland and the European Union, Border veterinary checks abolished 1 January 2009
A common veterinary area between Switzerland and the EU
Evidence: Expert or audit recommendationPartial match: some conditions differ
- What was changed
- Under Annex 11 of the 1999 EU–Swiss agricultural agreement, the EU recognised Swiss veterinary and food-safety law as equivalent; veterinary border checks between Switzerland and the EU ended and trade in animal products is treated like trade between member states.
- Study design and population
- Description of an operating arrangement; no evaluation of trade effects found Swiss and EU traders in animals and animal products
- Measured outcome there
- Administrative result: veterinary border controls removed since 2009; third-country goods are checked at Swiss airports instead. No measured trade effect was found.
- Cost status
- Not published.
- What failed or remains uncertain
- Trade effects are unmeasured. Switzerland keeps its law aligned (over 90% with EU food law, by its own account); customs duties and customs formalities remain.
- Why the UK differs
- The UK–EU arrangement is proposed on dynamic alignment, not recognised equivalence, and covers a much larger trade flow; the UK left EU structures rather than building up from outside them.
- First change required here
- Set an evaluation baseline (certificates, checks, rejected consignments, exporter numbers) before the SPS agreement operates, so its effect can be measured where the Swiss one never was.
Not a UK forecast: the effect above was measured in that place and population. Source: Swiss Federal Food Safety and Veterinary Office (FSVO/BLV), International agreements (Swiss–EU veterinary agreement, Annex 11 of the 1999 Agricultural Agreement) (Veterinary agreement section). Reviewed 2026-10-04.
8.What delivery needs first
- dependency — The European Commission and member states agree the final text. (Genuine veto: nothing proceeds without it; owner: European Commission)
- law — The European Partnership Bill and secondary legislation; devolved consent where devolved law is affected. (Genuine veto: nothing proceeds without it; owner: Parliament and devolved legislatures)
- data — Certificate, check and rejection data published before operation, for the baseline. (Requirement; owner: Defra, APHA and FSA)
- staff — FSA, APHA and port health staff to run the new regime. (Requirement; owner: FSA, APHA and councils)
9.What it would cost
How the cost is built up: Defra, FSA, APHA and port health implementation + business changes to processes, labelling and IT + evaluation. A GDP estimate is not tax receipts and is not netted off.
| Component | Unit and quantity | Unit cost or amount | Type, price year, period | Status |
|---|---|---|---|---|
| Public administration, business compliance and transitionGreat Britain–EU agri-food trade | programme; quantity to be set from need and capacity | Not yet costed (ledger C-A29-IMPLEMENTATION) | mixed; price year not stated; 2026–27 onwards | Not yet established |
| Independent evaluation with pre-implementation baselineCertificates, checks, rejections, exporter numbers and trade | one evaluation; quantity to be set from need and capacity | Not yet established | one-off revenue; price year not stated; 2027 onwards | Not yet established |
Public administration, business compliance and transition
Great Britain–EU agri-food trade
Not yet costed (ledger C-A29-IMPLEMENTATION)
mixed; price year not stated; 2026–27 onwards; Not yet established
Independent evaluation with pre-implementation baseline
Certificates, checks, rejections, exporter numbers and trade
Not yet established one evaluation
one-off revenue; price year not stated; 2027 onwards; Not yet established
10.Who pays, and what is missing
- Programme envelope (a possible route, not an award)
- None identified
- Allocation committed to this change
- None
- Remaining gap
- Neither total implementation cost nor business compliance cost has been published; the FSA’s one-year readiness funding covers only the FSA.
- Proposed financing
- Mainly a treaty and legal change. The FSA secured HM Treasury funding for its SPS readiness in 2026–27 (amount not published); funding for later years is being considered.
- Responsible payer
- central government, employers
- Budget displaced
- Departmental implementation budgets; businesses’ own compliance costs.
11.First milestone and time to a useful result
Publication of the final scope, exceptions and affected product groups, with a baseline dataset for the evaluation (Owner: Defra and the Cabinet Office. Proposed by UK Facts, not an official deadline.)
Time to first useful result: First operational data a year after implementation (planned summer 2027).
What could delay it: The postponed summit delays conclusion The European Partnership Bill is not introduced in time Exceptions are wider than expected
12.How we would know
- Baseline
- Export health certificates issued, checks, rejected consignments and GB agri-food exporter numbers in the year before operation.
- Comparison
- Agri-food trade outside the agreement’s scope and GB exports of the same products to non-EU partners.
- Leading indicator
- Certificates and checks removed in practice; border waiting times.
- Follow-up
- One and three years after operation.
- Continue if
- Certificates and routine checks are removed and small-exporter numbers recover relative to the comparison.
- Adapt if
- Checks fall but exporter numbers do not: look at the remaining frictions (customs, rules of origin, catch certificates).
- Stop if
- Not a stop decision: if certificates and checks are not removed within a year of operation, review the implementation with the EU.
- Thresholds
- Not yet set: No published business case or impact assessment sets numerical trade targets.
What is not yet known, and how to find out
- Total implementation and business compliance cost (cost)Next step: Defra to publish an impact assessment with the European Partnership Bill.Scope: GB–EU agri-food trade in scope · Data or quotes needed: Departmental and port health costs; business survey of alignment costs · Who can estimate it: Defra (impact assessment)
- Effect on trade volumes and exporter numbers (effect)Next step: Evaluate against the pre-implementation baseline and comparison.Defensible route: evaluation of existing delivery
- The final scope and exceptions (legal)Next step: Await the concluded text; update the brief on publication.
Sources last checked 4 October 2026 · Owner: Evidence editor (James Harris) · Next check: HMRC UK overseas trade in goods statistics: August 2026 (15 October 2026) or the first trigger: Text, ratification or entry into force of the UK–EU sanitary and phytosanitary agreement.
Decision briefPublic-policy proposalReviewed 2026-10-04
Fix one small exporter’s journey: a seafood firm still needs catch certificates and customs after the SPS deal
The thread: issue, evidence, action
- Issue Weakness: The new rules cut the number of product-country varieties exported to the EU by about 30%, driven by the loss of low-value trade relationships — consistent with smaller exporters leaving smaller EU markets. Also: weakness
- Evidence Goods exports to the EU, volume change since 2019
- Action Make the remaining border process usable for small exporters
- Decision required
- The Department for Business and Trade, HMRC and Defra map the full journey of a small GB seafood exporter sending consignments to the EU, remove the duplication that can lawfully be removed, and test joined-up guidance and digital documents with a cohort of small firms against a comparison group.
- Who and where
- Small and medium-sized GB seafood exporters to the EU. Applies in: Great Britain.
- Accountable body
- Department for Business and Trade
- Intervention
- Map the remaining steps for one exporter type, remove lawful duplication and test single-entry digital documents with support.
- Best evidence, and where it applies
- Defra says catch certificates and processing statements will still be required for wild-caught seafood after the SPS agreement, and customs controls will remain; the NAO found exporting could take more than 20 steps rather than two.Studied in: UK border operations and traders (January to July 2021).How closely the comparison transfers to this decision: Switzerland and the European Union — partial.
- Extra cost of this change
- Capital: none identified in the brief.Recurring: none identified in the brief.One-off or mixed: Digital integration, support staff and firms’ compliance time — Not yet costed.
- Funding
- Not funded: no funding route identified yet.Committed to this change: none.Possible source, not an award: none identified.Unfunded: Not costed; no funding route identified.
- Savings and wider benefits
- Not yet specified: no cashable saving or avoided cost has been costed for this change. Expected outcomes are listed one by one in the research appendix and are never added together or counted as money available.
- First 90-day step
- A published map of the small seafood exporter journey after the SPS agreement, marking each step as removed, remaining or duplicatedThe proposed first milestone; a 90-day date is not yet specified. Owner: Department for Business and Trade with HMRC and Defra. Proposed by UK Facts, not an official deadline.
- Twelve-month milestone
- Not yet specified.Time to a first useful result: The map within six months of the agreement’s final text; pilot results a year after it starts.
- Outcome, and when to scale or stop
- Measure: Compliance time and cost per consignment.Scale if: Pilot firms’ time and cost per consignment fall and they keep exporting relative to the comparison group.Stop if: Pilot firms do not export more than the comparison group after a year.
- Main trade-off
- Process support cannot remove legal requirements, and subsidised help may pay for exporting that would have happened anyway.
- Source and review date
- The UK border: post UK–EU transition period (HC 736, Session 2021–22) (5 November 2021). Reviewed 2026-10-04.
An editorial proposal by UK Facts for discussion, not government policy. Records: A30 · costs C-A30-PILOT
Research appendix: study design, effect sizes and limits, alternatives, full costing, international comparisons and how we would know
1.The change, in plain words
Fix one small exporter’s journey: a seafood firm still needs catch certificates and customs after the SPS deal
2.The decision requested
- Decision
- Commission a mapped journey for small seafood exporters (from catch to EU customer), publish which steps remain after the SPS agreement and which duplicate each other, and run a bounded pilot of single-entry digital documents and assisted support with a comparison group.
- Accountable institution
- Department for Business and Trade
- Geography
- Great Britain
- Powers
- Existing departmental powers for trade support and HMRC’s customs systems; the IUU catch-documentation rules are outside the SPS agreement and stay in force.
- Delivery partners
- HMRC; Defra (catch documentation); Animal and Plant Health Agency; Seafood trade bodies and logistics hubs; Devolved business-support bodies
3.Who it is for, and what changes beyond today
- Target population
- Small and medium-sized GB seafood exporters to the EU.
- Eligibility
- Firms sending wild-caught seafood consignments to EU customers, including those using logistics hubs to consolidate shipments.
- Scale
- A pilot cohort sized by DBT for comparison; not a national scheme.
- Baseline
- Today each consignment needs an export health certificate certified by an official vet or certifying officer (APHA charges no issuing fee but exporters pay for inspection and certification), a catch certificate and processing statement, and customs declarations. After the SPS agreement, catch documentation and customs controls remain. About 30% fewer product-country export varieties to the EU after the TCA (CEP).
Source: Defra / APHA; House of Commons, Get an export health certificate (guidance) and written answer 128122 on EHC fees (Guidance; written answer 128122); Department for Environment, Food and Rural Affairs, Fish and shellfish: preparing your business (SPS agreement guidance) (IUU and customs sections); LSE Centre for Economic Performance, UK trade in the wake of Brexit (CEP Discussion Paper 1847) (Introduction, PDF p.4)
- Change beyond existing law or funding
- The SPS agreement removes health certificates and routine checks; the business-preparation guidance says what remains. Nobody has mapped the remaining small-exporter journey step by step or tested whether joined-up documents cut its time and cost.
4.How it would work
Do: Map the remaining steps for one exporter type, remove lawful duplication and test single-entry digital documents with support Changing: so that the fixed time and cost of each small consignment fall
Lower compliance time and cost per consignment for pilot firms
Hypothesis to test
No official per-consignment estimate exists beyond the £200 certificate saving; the pilot measures it.
More small firms keep exporting to the EU, compared with similar firms
Hypothesis to test
The CEP conjecture that fixed costs pushed small exporters out is untested.
Outcomes are kept separate and never added into one impact figure.
5.Best evidence
The UK border: post UK–EU transition period (HC 736, Session 2021–22)
- Author or institution:
- National Audit Office
- Published:
- 5 November 2021
- Evaluation period:
- January to July 2021
- Design:
- Value-for-money audit
- Sample or population:
- UK border operations and traders
- Effect and uncertainty:
- About 140,000 export health certificates signed in seven months; smaller traders could no longer use groupage in the same way; exporting could take more than 20 steps rather than two (industry estimate).
- Limits:
- Early period; step counts and cost estimates come from industry representatives.
Where: Summary paragraph 13; paragraph 2.15. Affiliation is provenance, not proof of quality.
6.Alternatives, counter-evidence and who loses
- Closest feasible alternative
- Rely on the SPS agreement and existing export support services without a journey-specific pilot.
- Strongest counter-evidence
- Process support cannot remove legal barriers; firms that stopped exporting may not return; subsidised support can pay for what would have happened anyway.
Source: LSE Centre for Economic Performance, UK trade in the wake of Brexit (CEP Discussion Paper 1847) (Introduction)
- Distributional effects
- Small exporters gain most; firms without digital capacity may not unless assisted support is offered.
- Main downside
- A journey pilot for one sector may not generalise to others.
| Option | Who is reached | Evidence | Likely outcome and timing | Cost and funding | Main trade-off |
|---|---|---|---|---|---|
| The proposalMap and pilot the small seafood exporter journey after the SPS deal | A cohort of small seafood exporters | Defra guidance on remaining steps; NAO on step counts | Map within six months; results after a year | Not costed; no route identified | Cannot remove legal requirements |
| Current policyCurrent policy: SPS agreement plus existing business-preparation guidance | All affected firms | Defra guidance; call for information | From mid-2027 | Within departmental budgets | Remaining steps not mapped per journey |
The options compared, including current policy
The proposal
Map and pilot the small seafood exporter journey after the SPS deal
- Who is reached
- A cohort of small seafood exporters
- Evidence
- Defra guidance on remaining steps; NAO on step counts
- Likely outcome and timing
- Map within six months; results after a year
- Cost and funding
- Not costed; no route identified
- Main trade-off
- Cannot remove legal requirements
Current policy
Current policy: SPS agreement plus existing business-preparation guidance
- Who is reached
- All affected firms
- Evidence
- Defra guidance; call for information
- Likely outcome and timing
- From mid-2027
- Cost and funding
- Within departmental budgets
- Main trade-off
- Remaining steps not mapped per journey
7.What other countries or the devolved nations show
Country lesson · Switzerland and the European Union, Border veterinary checks abolished 1 January 2009
A common veterinary area between Switzerland and the EU
Evidence: Expert or audit recommendationPartial match: some conditions differ
- What was changed
- Under Annex 11 of the 1999 EU–Swiss agricultural agreement, the EU recognised Swiss veterinary and food-safety law as equivalent; veterinary border checks between Switzerland and the EU ended and trade in animal products is treated like trade between member states.
- Study design and population
- Description of an operating arrangement; no evaluation of trade effects found Swiss and EU traders in animals and animal products
- Measured outcome there
- Administrative result: veterinary border controls removed since 2009; third-country goods are checked at Swiss airports instead. No measured trade effect was found.
- Cost status
- Not published.
- What failed or remains uncertain
- Trade effects are unmeasured. Switzerland keeps its law aligned (over 90% with EU food law, by its own account); customs duties and customs formalities remain.
- Why the UK differs
- The UK–EU arrangement is proposed on dynamic alignment, not recognised equivalence, and covers a much larger trade flow; the UK left EU structures rather than building up from outside them.
- First change required here
- Set an evaluation baseline (certificates, checks, rejected consignments, exporter numbers) before the SPS agreement operates, so its effect can be measured where the Swiss one never was.
Not a UK forecast: the effect above was measured in that place and population. Source: Swiss Federal Food Safety and Veterinary Office (FSVO/BLV), International agreements (Swiss–EU veterinary agreement, Annex 11 of the 1999 Agricultural Agreement) (Veterinary agreement section). Reviewed 2026-10-04.
8.What delivery needs first
- dependency — The SPS agreement’s final scope, which decides which steps disappear. (Genuine veto: nothing proceeds without it; owner: Defra and the European Commission)
- infrastructure — HMRC and Defra systems able to accept data once (customs and catch documentation). (Scarce resource shared with other priorities; owner: HMRC and Defra)
- law — The IUU catch-certificate requirement stays; only duplication can be removed. (Requirement; owner: Defra)
9.What it would cost
How the cost is built up: Journey mapping + system changes for single entry + support staff × cohort + evaluation.
| Component | Unit and quantity | Unit cost or amount | Type, price year, period | Status |
|---|---|---|---|---|
| Digital integration, support staff and firms’ compliance timeA cohort of small seafood exporters | pilot; quantity to be set from need and capacity | Not yet costed (ledger C-A30-PILOT) | one-off revenue; price year not stated; One year of operation after the SPS agreement | Not yet established |
Digital integration, support staff and firms’ compliance time
A cohort of small seafood exporters
Not yet costed (ledger C-A30-PILOT)
one-off revenue; price year not stated; One year of operation after the SPS agreement; Not yet established
10.Who pays, and what is missing
- Programme envelope (a possible route, not an award)
- None identified
- Allocation committed to this change
- None
- Remaining gap
- Not costed; no funding route identified.
- Proposed financing
- Check existing DBT export-support allocations first; none identified in this review.
- Responsible payer
- central government, employers
- Budget displaced
- Other export-support services if funded from existing DBT budgets.
11.First milestone and time to a useful result
A published map of the small seafood exporter journey after the SPS agreement, marking each step as removed, remaining or duplicated (Owner: Department for Business and Trade with HMRC and Defra. Proposed by UK Facts, not an official deadline.)
Time to first useful result: The map within six months of the agreement’s final text; pilot results a year after it starts.
What could delay it: The SPS agreement is delayed Systems cannot share data without new procurement
12.How we would know
- Baseline
- Steps, time and cost per consignment for the pilot cohort before changes, measured by time-use diaries.
- Comparison
- Similar small seafood exporters not in the pilot.
- Leading indicator
- Compliance time and cost per consignment.
- Follow-up
- Exporter participation and consignments after one year.
- Continue if
- Pilot firms’ time and cost per consignment fall and they keep exporting relative to the comparison group.
- Adapt if
- Time falls but participation does not: the binding cost lies elsewhere (customs or market access).
- Stop if
- Pilot firms do not export more than the comparison group after a year.
- Thresholds
- Not yet set: Set from the baseline diaries and the pilot’s power calculation.
What is not yet known, and how to find out
- Pilot cost (cost)Next step: DBT to scope system changes with HMRC and Defra and price support staff.Scope: One cohort, one year · Data or quotes needed: System change quotes; support staffing · Who can estimate it: Department for Business and Trade
- Compliance time and cost per consignment (data)Next step: Collect time-use diaries from a sample of small exporters before changes.
- Whether lower friction brings small exporters back (effect)Next step: The comparison-group pilot.Defensible route: bounded pilot
Sources last checked 4 October 2026 · Owner: Evidence editor (James Harris) · Next check: HMRC UK overseas trade in goods statistics: August 2026 (15 October 2026) or the first trigger: Text, ratification or entry into force of the UK–EU sanitary and phytosanitary agreement.
What it would take
The order things have to happen in
First, the prerequisite
Conclude SPS negotiations and publish scope and exceptions
Owner: UK government (Defra, Cabinet Office) and European Commission
No date: the timing depends on the steps before it.
Then, the decision
Pass implementing legislation (an anticipated European Partnership Bill)
Owner: Parliament
No date: the timing depends on the steps before it.
Then, delivery
Operate the agreement; pilot support for a cohort of small exporters
Owner: Defra, FSA and port health authorities; Department for Business and Trade
Summer 2027 (FSA planning assumption, not an agreed date) — source
Finally, the measured outcome
Certificates, border delays and exporter numbers against comparable trade
Owner: Defra; HMRC trade statistics; ONS
No date: the timing depends on the steps before it.
Who pays, and what is still missing
Cost, committed funding and the remaining gap for the same scope and years. A programme envelope is not an award to a project; a proposal is not committed money. None of these costs has been established yet, so no total is shown.
Cost and funding ledger
Public administration, business compliance and transition for an SPS agreement
A29 · administration · not costed
- Amount
- Not yet costed
- Who pays
- central government, employers
- Committed
- None identified
- Proposed, not committed
- FSA SPS programme funding from HM Treasury, 2026–27 (amount not published)
- Gap
- Not established
Digital integration, support staff and firms’ compliance time for an SME pilot
A30 · administration · not costed
- Amount
- Not yet costed
- Who pays
- central government, employers
- Committed
- None identified
- Proposed, not committed
- —
- Gap
- Not established
“Not yet costed” means no defensible cost has been found — not that the action is free. Lifetime benefits, benefit-cost ratios and forecast savings are never shown here as money available to spend.
Effects on record, with evidence ratings (2 records)
What the evidence says each action changes
| Action | Outcome and area | Effect | Compared with | Evidence |
|---|---|---|---|---|
| Reduce food-trade friction through a clearly scoped agreement | Cost and time of agri-food trade with the EU Trade and EU relations | Direction plausible; size not established | — | plausible spillover; limited confidence; Great Britain and EUSavings per consignment are government statements, not evaluated trade effects; the agreement is not yet concluded. |
| Reduce food-trade friction through a clearly scoped agreement | UK freedom to set its own food and plant rules Trade and EU relations · harm | Size not established | — | plausible spillover; moderate confidence; United KingdomWhether this is a cost is a value judgement; the trade-off is real. |
How we would know
The outcome measures to watch. A baseline is where we start, not a target; where there is no official target we say so.
Goods exports to the EU, volume change since 2019
% change · United Kingdom
- Baseline
- Not published
- Latest
- −14%
- 2025
Target: none — no official trade target.
Source: Office for National Statistics, UK trade time series (MRET), chained volume measures (CDID JIM8). Next release: monthly UK trade release (check the release calendar).
Goods exports to the rest of the world, volume change since 2019
% change · United Kingdom
- Baseline
- Not published
- Latest
- −8%
- 2025
Target: none — a comparison series, not a target.
Source: Office for National Statistics, UK trade time series (MRET), chained volume measures (CDID JIN3). Next release: monthly UK trade release (check the release calendar).
Measured results
What each option would be judged on, and the latest value of the measures already on this page. A measure moving is not proof that an option caused it.
Cut EU trade friction with a scoped food-and-farm deal
Judged on: Border time/cost, trade and consumer prices, with external shocks separated.
Data source: not yet named; baseline: not yet established.
- Goods exports to the EU, volume change since 2019Latest: −14% (2025). Baseline: not published. United Kingdom.
National plan: Growth and prosperity list
Where the ideas come from
Research, counter-evidence and methods (9 sources; 2 claims held back)
- Agreements reached between the UK and the EU (Trade and Cooperation Agreement, December 2020) — UK Government, date not stated.Treaty; United Kingdom and EU. Summary or abstract only, 2026-10-04.
- UK–EU Summit key documentation (Common Understanding, 19 May 2025; Joint Statement, 17 December 2025) — UK Government, 2025-05-19.Intergovernmental statement; United Kingdom and European Union. Relevant passages checked, 2026-10-04. Limits: An agreement to negotiate, not an operating treaty.
- UK trade time series (MRET), chained volume measures — Office for National Statistics, 11 September 2026.Official statistics; United Kingdom. Relevant passages checked, 2026-10-04.
- UK trade in the wake of Brexit (CEP Discussion Paper 1847) — LSE Centre for Economic Performance (Rebecca Freeman, Kalina Manova, Thomas Prayer, Thomas Sampson), 2022-04.Peer-reviewed working paper (difference-in-differences against rest-of-world trade); United Kingdom. Relevant passages checked, 2026-10-04.
- UK–EU Summit package explainer (19 May 2025) — UK Government, 2025-05-19.Government explainer; United Kingdom. Full text checked, 2026-10-04. Limits: Government statements of administrative savings, not an evaluation of trade effects.
- An update to the Board on the Food Standards Agency’s SPS programme: September 2026 — Food Standards Agency, 2026-09-15.Board paper; United Kingdom. Relevant passages checked, 2026-10-04.
- UK-EU Regulatory Divergence Tracker Q1 2026 (sixteenth edition) — UK in a Changing Europe (Joel Reland), 2026-04.Legal and policy tracking of regulatory developments; United Kingdom and European Union. Relevant passages checked, 2026-10-04. Limits: Tracks rules, not trade outcomes. A snapshot at the end of March 2026: later status is taken from the Food Standards Agency board update of September 2026.
- UK trade time series (MRET): goods exports to the United States (J9C5) and to all countries (BOKG) — Office for National Statistics, 2026-09-11.Official statistics; United Kingdom. Relevant passages checked, 2026-10-04. Limits: Current prices including precious metals: a fall can be price as well as volume. Stored as trade-goods-exports-us-cp and trade-goods-exports-total-cp (scripts/state-of-nation/ingest-trade-partners.py).
- US trade tariffs (Research Briefing CBP-10240) — House of Commons Library (Jozepa I, Webb D), 2026-04-14.Parliamentary research briefing; United Kingdom and United States. Relevant passages checked (The Library site returned HTTP 403 to scripted access; read from the Internet Archive copy of 22 May 2026 (web.archive.org/web/20260522130955/…). Archived copy, labelled as such.), 2026-10-04. Limits: Status at April 2026. The section 122 tariff period has since run out and the current rate on UK goods is not confirmed here (held).
Counter-evidence and criticism
- Reduce food-trade friction through a clearly scoped agreement: Dynamic alignment means taking EU rules the UK does not vote on, limiting divergence in areas such as gene editing; enforcement obligations follow; gains differ sharply by sector and firm size. (UK in a Changing Europe)
- Make the remaining border process usable for small exporters: Process support cannot remove legal barriers; firms that stopped exporting may not return; subsidised support can pay for what would have happened anyway. (LSE Centre for Economic Performance)
Claims held back
- The US tariff rate on most UK goods in October 2026 — The latest source read (Commons Library, April 2026, archived copy) describes a 10% tariff under a 150-day section 122 proclamation after the February 2026 Supreme Court ruling; what replaced it was not confirmed from a primary source. Needed: A US proclamation or a UK government statement on the current rate, or an updated Commons Library briefing.
- Expected trade or GDP gains from an SPS agreement — Only government statements of administrative savings were found; no independent estimate on current terms was checked. Needed: An independent impact assessment of the final agreement.
“Full text checked” means we read the report itself; “relevant passages” means the sections behind each figure; “summary or abstract only” means we could not read the full study, so no number from it is published here without another source.
Other options compared — not on the shortlist (4)
Other options compared
Options from earlier work on this page that are not on the shortlist. They remain valid choices; their evidence is shown as before.
- structuralStatus: announced
Linking UK and EU carbon markets
- Aims to:
- UK exporters exempted from the EU’s carbon border levy, and a larger, more stable carbon market.
- How:
- Linking the UK Emissions Trading Scheme with the EU’s means carbon prices converge, so the EU no longer charges its Carbon Border Adjustment Mechanism on UK goods.
- Who decides:
- DESNZ and the UK ETS Authority; the European Commission.
- Main constraint:
- Requires aligning cap and rules with the EU system.
- Evidence:
- Limited evidence — plausible mechanism, little direct evaluation
See the trade-offs and evidence
- What the evidence shows
- The government estimates around £7bn of UK trade would otherwise face the EU carbon levy, and that UK exporters could pay up to £800m by 2030. These are government estimates, not independent evaluations.
- Policy status
- Agreed to work towards at the May 2025 summit; negotiation continuing.
- Resources
- Negotiation and market regulation; no large public spending.
- Consent and decisions needed
- UK–EU agreement; Parliament for any legislation.
- Time
- Depends on negotiation; the EU levy’s definitive phase began in 2026.
- Cost and yield
- Avoided levy payments of up to £800m by 2030 (government estimate); higher carbon prices for some UK emitters if UK prices rise to EU levels.
- Trade-offs and who pays
- Avoids a border levy but ties UK carbon policy to EU decisions.
- How we would know it worked
- Leading indicator: Agreement signed and linked registries operating. Outcome: EU carbon levy payments by UK exporters. It would not be working if: Linking delayed past the levy’s full application, so exporters pay anyway.
- structuralStatus: announced
A youth experience scheme and Erasmus+ association
- Aims to:
- Young people from the UK and EU able to work, study or travel for a limited period in each other’s countries.
- How:
- A capped, time-limited visa route for under-30s, plus UK participation in the EU’s Erasmus+ education programme.
- Who decides:
- Home Office and DfE; the European Commission.
- Main constraint:
- Counts towards migration figures; the size of any cap is politically sensitive.
- Evidence:
- Not evaluated — a mechanism to test, not an evidenced fix
See the trade-offs and evidence
- What the evidence shows
- The EU and UK concluded terms for UK association to Erasmus+ from 2027 (December 2025). The youth scheme’s terms, caps and duration were still under negotiation; no published evaluation of its economic effect.
- Policy status
- Erasmus+ association terms concluded December 2025 for 2027; youth experience scheme in negotiation.
- Resources
- A financial contribution to Erasmus+; visa processing capacity.
- Consent and decisions needed
- UK–EU agreement; changes to UK immigration rules.
- Time
- Erasmus+ from 2027; youth scheme dependent on negotiation.
- Cost and yield
- Erasmus+ terms described as a “fair balance” of contributions and benefits; the figure is not stated in the joint statement.
- Trade-offs and who pays
- Wider opportunities for young people versus higher measured migration and a payment to an EU programme.
- How we would know it worked
- Leading indicator: Number of UK participants in Erasmus+ and visas issued under the scheme. Outcome: Two-way youth mobility compared with before 2021. It would not be working if: Take-up is a small fraction of the cap.
- structuralStatus: external option
Mutual recognition of professional qualifications and services access
- Aims to:
- UK professionals and service firms able to work in EU countries with less duplicated authorisation.
- How:
- Agreements recognising qualifications (architects, engineers, auditors and others) and easing short business visits.
- Who decides:
- Department for Business and Trade; professional regulators; the European Commission and member states.
- Main constraint:
- Each profession and member state differs; the EU has been reluctant to grant broad recognition outside the single market.
- Evidence:
- Not evaluated — a mechanism to test, not an evidenced fix
See the trade-offs and evidence
- What the evidence shows
- The Trade and Cooperation Agreement allows recognition arrangements profession by profession; the 2025 Common Understanding lists qualifications and business mobility among areas for further work. No evaluation of the trade effect on this site.
- Resources
- Regulator time to negotiate profession-by-profession arrangements.
- Consent and decisions needed
- UK–EU agreement under the Trade and Cooperation Agreement’s procedures.
- Time
- Years, profession by profession.
- Cost and yield
- No reliable estimate.
- Trade-offs and who pays
- May require reciprocal recognition of EU qualifications in the UK.
- How we would know it worked
- Leading indicator: Number of recognition arrangements agreed. Outcome: Services exports to the EU (current prices) relative to non-EU. It would not be working if: Arrangements agreed but services exports to the EU lag other markets.
- structuralStatus: external option
Rejoining a customs union or the single market
- Aims to:
- Removing tariffs and rules-of-origin checks (customs union; customs declarations would remain, as in EU–Turkey trade), or most goods and services barriers (single market).
- How:
- A common external tariff ends rules-of-origin checks; single-market membership also removes regulatory checks and restores free movement of people.
- Who decides:
- UK government and Parliament; the EU and all member states.
- Main constraint:
- A customs union ends an independent tariff and trade policy, including the new FTAs; single-market membership requires free movement and accepting EU rules without a vote.
- Evidence:
- Moderate evidence — evaluated, with limits on scope or transfer
See the trade-offs and evidence
- What the evidence shows
- Studies of the existing trade deal find large costs from the frictions these options would remove — for example a 25% relative fall in imports from the EU — but there is no official estimate of the gain from re-entry.
- Policy status
- Ruled out by the current UK government.
- Resources
- Treaty negotiation; for the single market, a budget contribution.
- Consent and decisions needed
- A major treaty requiring political consent in the UK and agreement by all EU members.
- Time
- Years to negotiate.
- Cost and yield
- No official costing.
- Trade-offs and who pays
- Most of the trade friction removed, most of the policy autonomy given up — the central trade-off of the whole debate.
- How we would know it worked
- Leading indicator: Rules-of-origin requirements and regulatory checks on UK–EU trade. Outcome: UK–EU goods trade volumes relative to non-EU. It would not be working if: Trade does not recover relative to other partners after barriers are removed.
| Option | Resources | Time | Evidence | Outcome to watch |
|---|---|---|---|---|
| Linking UK and EU carbon markets | Negotiation and market regulation; no large public spending. | Depends on negotiation; the EU levy’s definitive phase began in 2026. | limited | EU carbon levy payments by UK exporters. |
| A youth experience scheme and Erasmus+ association | A financial contribution to Erasmus+; visa processing capacity. | Erasmus+ from 2027; youth scheme dependent on negotiation. | not evaluated | Two-way youth mobility compared with before 2021. |
| Mutual recognition of professional qualifications and services access | Regulator time to negotiate profession-by-profession arrangements. | Years, profession by profession. | not evaluated | Services exports to the EU (current prices) relative to non-EU. |
| Rejoining a customs union or the single market | Treaty negotiation; for the single market, a budget contribution. | Years to negotiate. | moderate | UK–EU goods trade volumes relative to non-EU. |
Plan reviewed 2026-10-04. How we judge evidence.
How this connects
- What is observed, and what is modelled relative to remaining?
The OBR’s 4% is a long-run assumption about a path the UK did not take; observed GDP since 2016 cannot confirm or refute it.
Do not attribute all post-2016 economic change to Brexit.
- Where does migration stand now?
Ending free movement changed who comes; the national migration picture, routes and asylum are on the Immigration page.
- Why has UK growth been slow?
Weak investment and productivity predate 2016. The growth domain looks at the wider causes, of which trade frictions are one.
An association across years is not a measure of Brexit’s share.
- How was the referendum covered?
A content analysis of press coverage during the 2016 campaign.
Coverage is not persuasion; the study measures what was published, not how votes changed.
Also in this section
- How Brexit happened — 1973 to 2026, including the 2016 result.
- What was promised — campaign claims from both sides, checked.
- Where Britain gained — the new powers and how they have been used.
- Who paid for the campaigns — reported referendum spending.
Sources and methods (8)
- ONS, UK trade time series (MRET), chained volume measures, CDIDs JIM8, JIN3, JIM7, JIN2 (goods excluding precious metals); IKBE, IKBF (services) (released 11 September 2026) — goods and services trade volumes (BREXIT-02, BREXIT-03)
- ONS, Long-term international migration, provisional: year ending December 2025, Table 1 (released 21 May 2026) — net migration by nationality (BREXIT-04)
- ONS, Business investment, chained volume measure (NPEL), CDID NPEL, quarterly national accounts — business investment (BREXIT-05)
- Office for Budget Responsibility, Brexit analysis (released page last updated 20 July 2026) — long-run productivity and trade-intensity assumptions (modelled)
- Bloom, Bunn, Mizen, Smietanka, Thwaites and Abrahams, “The Economic Impact of Brexit”, NBER Working Paper 34459 (released November 2025, revised June 2026) — academic estimate of effects on GDP, investment, employment and productivity (modelled)
- Freeman, Manova, Prayer and Sampson, “UK trade in the wake of Brexit”, CEP Discussion Paper 1847 (LSE) (released April 2022) — academic estimate of the trade deal’s effect on UK–EU trade (modelled)
- UK Government, UK–EU Summit key documentation (Common Understanding, 19 May 2025; Joint Statement, 17 December 2025) — 2025 summit commitments and the December 2025 joint statement
- UK Government, Agreements reached between the UK and the EU (Trade and Cooperation Agreement, December 2020) — Trade and Cooperation Agreement text
Method notes
- Three kinds of evidence are kept separate: dated legal changes, observed official statistics, and modelled estimates relative to remaining in the EU. Modelled estimates are never drawn as observed lines.
- Trade is measured in volumes (chained volume measures), which remove price changes. Goods exclude precious metals. Indices use 2019, the last full year before both the pandemic and the end of the transition period, as the base.
- Migration uses ONS’s provisional long-term migration estimates, revised in every release; the 2016 values are ONS’s current back series, not the figures published at the time.
- The OBR and NBER estimates measure different things (long-run productivity versus GDP, investment and employment by 2025) and use different methods; they are presented side by side, not averaged.