Monarchy · United Kingdom · 2025–26
The Sovereign Grant was £132m in 2025–26. The full public cost is not published.
The audited Sovereign Grant was £132.1m in 2025–26 and is set at £137.9m for 2026–27, the final year of Buckingham Palace reservicing funding. Royal security costs are not published, and several other public costs are disclosed only in part, so the grant cannot establish the total.
Editorial purpose (not a recommendation): Show which public costs of the monarchy are audited, which are disclosed only in part and which are not published, without taking a side on the constitutional question.
Evidence last reviewed 3 October 2026
Overview
The short version
Three audited figures
£132.1m
Sovereign Grant (audited)
UK2025/26Outturn
Not the same as: The total public cost of the monarchy. Security, ceremonial and departmental costs sit outside it.
£67.5m
Spent on occupied royal palaces
UK2025/26Outturn
Not the same as: Money paid to the Royal Family. This is building preservation and protection — over half the Grant.
2,273
Official engagements by working royals
UK and overseas2025/26Administrative count
Not the same as: A measure of value. It counts activity, not what that activity achieved.
What it means
Anyone quoting a single annual cost for the monarchy — in either direction — is filling in gaps the accounts leave open.
The evidence
The evidence, path by path
What is audited: the Sovereign Grant
The Grant rises to £137.9m in 2026/27, the final scheduled tranche for the Buckingham Palace reservicing programme. It pays for official duties, staff, travel and the occupied palaces.
Known, partial, and not disclosed
Published and audited
- Sovereign Grant, 2025/26£132.1m
- Of which occupied royal palaces£67.5m
- Sovereign Grant, 2026/27£137.9m
- Crown Estate profit to Treasury, 2025/26£487m
Known but partial
- Royal Household Pension Scheme, 2024/25£5m
- Lord-lieutenants, Cabinet Office, 2023/24£1.5m
- 2023 Coronation, DCMS£50.3m
- Coronation policing, Home Office£21.7m
- Queen Elizabeth II state funeral, 2022£161.7m
Not disclosed
- Royal security and policing — withheld because a breakdown could compromise protection arrangements
- Departmental support for honours, ceremonial occasions and state visits
- Military support for ceremonial duties
- Local authority costs for royal visits
- The value of soft power, diplomacy and trade introductions
There is deliberately no total here. One-off event costs — coronations, funerals — must not be added to a recurring annual figure, and security, a recurring cost of unknown size, is not published at all. A single 'true cost of the monarchy' cannot be calculated from what is disclosed. Campaign-group estimates fill those gaps with assumptions; they belong in a debate, not in a ledger of audited figures.
What remains unknown
These costs are real but not published as figures, so they appear here as named gaps rather than as zero or as an estimate:
- Royal security and policing, withheld because a breakdown could compromise protection.
- Departmental support for honours, ceremonial occasions and state visits.
- Military support for ceremonial duties, and local authority costs of royal visits.
- Any measured value of soft power, diplomacy or trade introductions.
The Crown Estate is not a cheque from the King
This is the most common error in the monarchy’s favour. The Crown Estate returned £487m of profit to the Treasury in 2025/26. It is often presented as the King handing over £487m and receiving £132m back.
The Crown Estate is a statutory public corporation. Its assets are attached to the Crown as an institution, not owned by the King personally, and he neither manages nor controls it. The Sovereign Grant is calculated as a percentage of its profit from two years earlier — a funding formula, not a dividend.
- 1The Crown Estate operates independently, under its own board.
- 2Its profit goes to the Treasury.
- 3The Sovereign Grant is set as a percentage of that profit, lagged by two years.
- 4The Grant funds official duties and the occupied palaces.
So do not:compare £132.1m with £487m as though they were the same financial year; call Crown Estate profit “money the King gives the government”; assume the Crown Estate would cease to exist under a republic; or describe the Grant as a dividend the monarch legally owns.
Tax: liability and voluntary payment are different things
The King and the Prince of Wales are not legally liable for income tax, capital gains tax or inheritance tax where the relevant statutes do not bind the Crown. A non-statutory memorandum provides for voluntary payments, and the King does pay income tax on private income. Transfers from one sovereign to the next are exempt from inheritance tax.
Two claims that are not equivalent.“They pay tax” is true. “They are taxed exactly like everyone else” is not. Other members of the Royal Family are generally liable under normal rules.
Does tourism pay for the monarchy?
What is known, plainly: 2.7 million people visited the Royal Collection Trust in 2025/26, generating £61.0m in access income; Windsor Castle drew 1.25 million visits and the Buckingham Palace Summer Opening 555,024. Royal branding is used throughout UK tourism marketing. That is real, measured activity — nobody disputes it.
“The Royal Family brings in more through tourism than the monarchy costs”
UnverifiableWhat is known: Royal Collection Trust welcomed 2.7 million visitors in 2025/26, with access income of £61.0m. Windsor Castle recorded over 1.25 million visits in 2025 and the Buckingham Palace Summer Opening 555,024. Royal associations are used in tourism marketing.
What is not known: How many visits to Britain would not happen without a working monarchy; how much of that spending would simply go to other attractions; whether demand would change if the palaces, ceremonies and collections remained open under a different constitutional arrangement. The full public cost is also undisclosed, so neither side of the comparison is complete.
What would change this verdict: A credible counterfactual estimate of tourism caused by retaining a working monarchy, plus a full public cost including security. Neither exists.
One number would settle this. It doesn’t exist.
The old £500 million figure attributed a quarter of culture-and-heritage visitor spending to the monarchy, because roughly a quarter of the relevant attractions had royal connections — an association, not a measurement of cause; VisitBritain itself said it showed nothing about a republic. The reverse claim — that the monarchy costs more than it brings in — fails for the identical reason, not a different one. Neither side has produced the one number that would actually settle it: what tourism demand would look like without a working monarchy.
That is the finding, not an evasion of one: the tourism argument is undemonstrated on both sides, and no published research closes that gap. Until one does, treat any total on either side as invented.
Constitutional role: what power actually remains
The Crown retains substantial formal powers. Almost all are exercised by ministers, or by the King on advice he is constitutionally bound to accept — and responsibility then rests with ministers accountable to Parliament.
Appointing the Prime Minister
In law
The King formally appoints the Prime Minister.
In practice
Convention requires whoever can command the confidence of the Commons. Real discretion arises only in an unclear result.
Appointing and dismissing ministers
In law
Formally done by the King.
In practice
On the Prime Minister’s advice.
Royal Assent
In law
Required before a bill becomes an Act.
In practice
Parliament describes it as a formality. It was last refused in 1708.
Dissolving Parliament
In law
A prerogative revived by the Dissolution and Calling of Parliament Act 2022.
In practice
Exercised on the Prime Minister’s request. Parliament dissolves automatically after five years if not sooner.
Foreign affairs, treaties, armed forces
In law
Many powers remain Crown prerogatives.
In practice
Exercised by ministers, who are accountable to Parliament for them.
King’s or Prince’s Consent
In law
Required during passage of bills affecting Crown or Duchy interests.
In practice
Allows Parliament to debate the bill. Distinct from Royal Assent, and not refused in modern times.
Reserve powers
In law
Residual personal powers may exist in an exceptional constitutional crisis.
In practice
Narrow, convention-bound and rarely tested. Theoretical extremes are not ordinary governing power.
Claim checks
“The monarchy cost £132.1 million in 2025/26”
Missing contextWhat is known: That is the Sovereign Grant. It is an audited figure and it is correct as far as it goes.
What is not known: Security, departmental, devolved and local costs sit outside the Grant and are not all published. The total is higher, by an amount nobody outside government can state.
“The King gave the Treasury £487 million from his estate”
MisleadingWhat is known: The Crown Estate returned £487m to the Treasury in 2025/26. It is a statutory corporation whose assets are attached to the Crown as an institution.
What is not known: Nothing here is uncertain — the claim simply misdescribes ownership. The King neither owns the Crown Estate privately nor manages it, and the Grant is a lagged formula, not a refund.
“The King has no power”
MisleadingWhat is known: Real formal and residual powers remain, including appointing the Prime Minister and granting Royal Assent. In ordinary circumstances they are exercised on binding advice, by ministers accountable to Parliament.
What is not known: How reserve powers would operate in a genuine constitutional crisis. They are narrow and rarely tested, which is precisely why confident claims in either direction are unsafe.
Shareable visual summary
Visual summary
Image currentEvery figure printed in the image matches today’s record, and its primary sources have been checked.
The Sovereign Grant was £132m in 2025–26. The full public cost is not published.
The audited Sovereign Grant was £132.1m in 2025–26 and is set at £137.9m for 2026–27, the final year of Buckingham Palace reservicing funding. Royal security costs are not published, and several other public costs are disclosed only in part, so the grant cannot establish the total. £67.5m of the 2025–26 grant went on the occupied royal palaces; that is inside the grant, not on top.
- £132.1mSovereign Grant, 2025–26
- £67.5mof which: occupied palaces
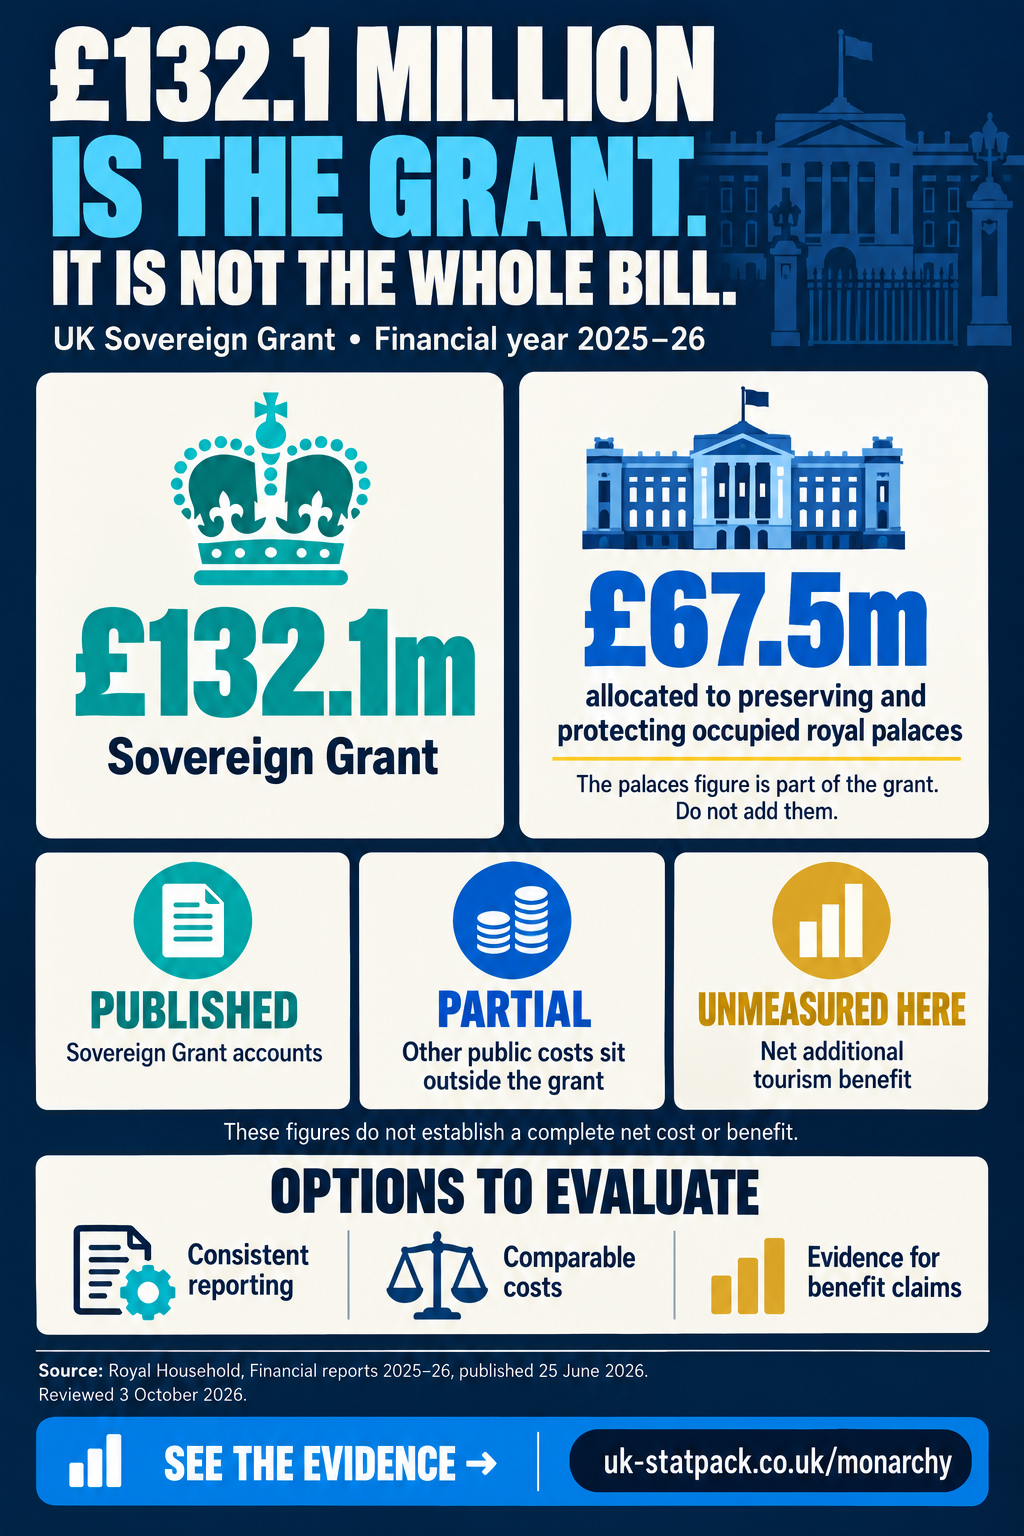
Text and data version
The Sovereign Grant was £132m in 2025–26. The full public cost is not published. The audited Sovereign Grant was £132.1m in 2025–26 and is set at £137.9m for 2026–27, the final year of Buckingham Palace reservicing funding. Royal security costs are not published, and several other public costs are disclosed only in part, so the grant cannot establish the total. £67.5m of the 2025–26 grant went on the occupied royal palaces; that is inside the grant, not on top.
| Measure | Value | Period | Geography | Type | Source |
|---|---|---|---|---|---|
| Sovereign Grant | £132.1m | 2025–26 | United Kingdom | administrative count | Royal Household, Sovereign Grant and Sovereign Grant Reserve Annual Report and Accounts 2025–26 |
| Sovereign Grant allocated to the occupied royal palaces (Reservicing and property maintenance) | £67.5m | 2025–26 | United Kingdom | administrative count | Royal Household, Sovereign Grant and Sovereign Grant Reserve Annual Report and Accounts 2025–26 |
Image description: Monarchy infographic: the 2025–26 Sovereign Grant was £132.1m, of which £67.5m went on the occupied royal palaces; it is not the whole cost.
All visual summaries, their source records and their publication state are listed on Shareable visuals.
Go deeper
What is audited?The Sovereign Grant: £132.1m in 2025–26, over half of it on the occupied palaces.What the Grant pays for, and what it is not.Read the chapter → What is audited? What else is disclosed?Pensions, lord-lieutenants and one-off events such as the coronation and state funeral.Kept apart from the annual Grant.Read the chapter → What else is disclosed? What remains unknown?Royal security costs are not published, so their size relative to the Grant is unknown.Why no full total can be calculated.Read the chapter → What remains unknown? Crown Estate and taxCrown Estate profit is not the King’s money; the Grant is a lagged formula.Ownership, the funding formula and voluntary tax.Read the chapter → Crown Estate and tax Does tourism pay for it?Undemonstrated on both sides: no counterfactual study exists.What a valid comparison would need.Read the chapter → Does tourism pay for it? Constitutional role and choicesFormal powers remain, exercised on ministers’ advice.Law versus practice, power by power.Read the chapter → Constitutional role and choices
Evidence → choices → outcomes
What the evidence can tell us
A complete, auditable account of what the monarchy costs the public, so funding and constitutional choices can be debated on evidence.
How we assessed these options
What would it take to improve this?
What would move the needle?
The outcome we want: A complete, auditable account of what the monarchy costs the public, so funding and constitutional choices can be debated on evidence.
The main constraint: Security costs are withheld on protection grounds and other costs sit in departmental, police and council accounts, so no full total exists; changing what is reported or how the Grant is set needs decisions by HM Treasury, the Royal Trustees and Parliament, and the constitutional question itself is a value choice.
Constraint type: evidence, public consent, legislation.
The position today
Which quadrant a point sits in is our analytical judgement, not a statistical category. Each point says whether it is a measured fact, our synthesis or a risk.
What we can build on Strengths
One part of the cost is set by a published formula and audited: the Sovereign Grant was £132.1m in 2025–26, 12% of Crown Estate income from two years earlier.
Measured factConfidence: High· 2025–26· United Kingdom
Source: HM Treasury, Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant 2025–26 (Report section; Annex A step 1); UCL Constitution Unit, The British Monarchy: FAQs (FAQ “How is the monarchy financed?”)
What government has committed to
Legislation: The Sovereign Grant Act 2011 sets the Grant by formula from Crown Estate profits two years earlier, audited by the Comptroller and Auditor General.
- Who and when:
- Earlier UK government (before July 2024), 18 October 2011.
- Since 20 July 2026:
- Changed by the Burnham government. The Burnham government’s Sovereign Grant Bill (Commons stages 14 September 2026; now in the Lords) resets the Grant to £99.9m for 2027-28 and the percentage to 20.5%; the NAO audit stays. Source: UK Parliament, Sovereign Grant Bill (bill 4280) (Bill stages (introduced 1 September 2026)).
- Source:
- HM Treasury (Royal Trustees), Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant Review 2026 (Paragraphs 5.2 and A.3)
Checked 4 October 2026. A commitment is not delivery.
Options (3)
Test the royal grant against an explicit public purpose
Sets out what the audited Grant is meant to fund, so the formula can be judged against need.
Who: HM Treasury; Royal Trustees · Evidence: Expert or audit recommendation · Status: Announced proposal
Source: HM Treasury (Royal Trustees), Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant Review 2026 (Paragraphs 1.12–1.13)
Publish a fuller, auditable monarchy cost statement
Places the audited Grant beside the costs that sit elsewhere.
Who: HM Treasury; Royal Household · Evidence: Untested proposal · Status: External proposal
Source: House of Commons Library, Finances of the Monarchy (CBP-9807) (Summary; section 8.1)
Widen the audit to value for money
The NAO can already examine value for money; a regular report would extend the audited part of the cost.
Who: National Audit Office; Parliament · Evidence: Expert or audit recommendation · Status: External proposal
Source: House of Commons, Sovereign Grant Bill, Committee of the whole House, 14 September 2026 (Hansard) (Minister on NAO audit)
The formula is reviewed every five years by the Royal Trustees; the 2026 review, published on 26 June 2026, recommended resetting the Grant to £99.9m from 2027–28 and the reference percentage to 20.5%.
Measured factConfidence: High· Review reported 26 June 2026· United Kingdom
Source: HM Treasury (Royal Trustees), Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant Review 2026 (Summary); House of Commons Library, Finances of the Monarchy (CBP-9807) (Summary); HM Treasury, Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant 2025–26 (Annex B, final paragraph)
What government has committed to
Policy: The Royal Trustees concluded the 2026 review on 26 June 2026: the Grant resets to £99.9m from 2027-28, the reference percentage is 20.5% for 2027-28 to 2031-32, and the next review is planned for 2031.
- Who and when:
- Starmer government (to July 2026), 26 June 2026.
- Since 20 July 2026:
- Kept by the Burnham government. The Burnham government is legislating the review’s conclusions in the Sovereign Grant Bill; the page’s “current review began in 2026” is now out of date (the review concluded in June 2026). Source: HM Treasury (deposited paper), Exchequer Secretary’s letter on the Sovereign Grant Bill, 11 September 2026 (DEP2026-0573) (Letter text).
- Source:
- HM Treasury (Royal Trustees), Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant Review 2026 (Paragraphs 1.12–1.13 and 6.5)
Checked 4 October 2026. A commitment is not delivery.
Options (2)
ShortlistedTest the royal grant against an explicit public purpose
Gives each five-yearly review a stated remit to test the formula against.
Who: HM Treasury; Royal Trustees · Evidence: Expert or audit recommendation · Status: Announced proposal
Source: HM Treasury (Royal Trustees), Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant Review 2026 (Paragraphs 1.12–1.13)
Require an NAO report and a Commons vote before any future rise in the percentage
Adds independent scrutiny between reviews.
Who: Parliament · Evidence: Untested proposal · Status: External proposal
Source: House of Commons, Sovereign Grant Bill, Committee of the whole House, 14 September 2026 (Hansard) (Amendment 1 (not pressed))
What is holding us back Weaknesses
Royal security costs are not published: Treasury guidance says no breakdown is available because disclosure could compromise protection.
Measured factConfidence: High· Guidance of August 2023, still in force June 2026· United Kingdom
Source: House of Commons Library, Finances of the Monarchy (CBP-9807) (Section 8.1, printed pp.75–76)
What government has committed to
No commitment found. No commitment to publish royal security costs: HM Treasury guidance says no breakdown is available because disclosure could compromise protection, and nothing on disclosure was found in the Sovereign Grant Bill debates or the 2026 review.
Searched: gov.uk search; Hansard and written statements since 20 July 2026; Sovereign Grant Bill debates of 1 and 14 September 2026; 4 Oct 2026
Checked 4 October 2026. A commitment is not delivery.
Options (2)
ShortlistedPublish a fuller, auditable monarchy cost statement
Reports security as a single audited total where a breakdown would be unsafe.
Who: HM Treasury; Home Office; Royal Household · Evidence: Untested proposal · Status: External proposal
Source: House of Commons Library, Finances of the Monarchy (CBP-9807) (Section 8.1)
Audit security costs with closed reporting to Parliament
An NAO audit reported to a committee in private tests the cost without publishing operational detail.
Who: National Audit Office; Parliament · Evidence: Untested proposal · Status: External proposal
Other costs sit in separate accounts: £5.1m for Royal Household pensions from the Consolidated Fund and £1.5m for Lord-Lieutenants from the Cabinet Office, plus event policing and council costs that are not reported together.
Measured factConfidence: High· 2023–24· United Kingdom
Source: House of Commons Library, Finances of the Monarchy (CBP-9807) (Section 8.1, printed p.75)
What government has committed to
No commitment found. No commitment to publish a consolidated statement of monarchy costs. The Exchequer Secretary’s letter on the Sovereign Grant Bill promises a framework that is “proportionate, transparent and subject to appropriate parliamentary oversight”, not a cost statement.
Searched: gov.uk search; Sovereign Grant Bill debates and deposited letter (11 Sep 2026); 4 Oct 2026
Checked 4 October 2026. A commitment is not delivery.
Options (2)
ShortlistedPublish a fuller, auditable monarchy cost statement
Brings pensions, Lord-Lieutenants, policing and council costs into one reconciled table.
Who: HM Treasury; Royal Household · Evidence: Untested proposal · Status: External proposal
Source: House of Commons Library, Finances of the Monarchy (CBP-9807) (Summary; section 8.1)
Widen the audit to value for money
An NAO review of the costs outside the Grant would show what they buy.
Who: National Audit Office · Evidence: Untested proposal · Status: External proposal
What could improve things Opportunities
The Sovereign Grant Bill, introduced on 1 September 2026 and passed by the Commons on 14 September, resets the Grant lower after the Buckingham Palace reservicing; its passage and the next review period are a natural point to set an explicit remit and publish a reconciled cost statement.
Depends on: The Bill completes its Lords stages (scheduled for 14 October 2026), and the government agrees what security information can be reported safely as an aggregate.
Our synthesisConfidence: Moderate
Source: UK Parliament, Sovereign Grant Bill (bill 4280) (Stages (1st reading 1 September 2026; Commons stages 14 September 2026)); HM Treasury (Royal Trustees), Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant Review 2026 (Summary); House of Commons Library, Finances of the Monarchy (CBP-9807) (Summary); HM Treasury, Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant 2025–26 (Report section, final paragraph)
What government has committed to
Legislation: The Sovereign Grant Bill sets the 2027-28 Grant at £99.9m and the percentage at 20.5%, and adds a trigger for a reset if the reserve falls below 10% or rises above 50% of spending, plus an emergency in-year increase power.
- Who and when:
- Burnham government (from 20 July 2026), 1 September 2026.
- Since 20 July 2026:
- Made by the current government. Announced in the Starmer government’s King’s Speech (May 2026); introduced by the Burnham government. No remit or cost statement was added in the Commons.
- Source:
- UK Parliament, Sovereign Grant Bill (bill 4280) (Bill stages and long title)
Checked 4 October 2026. A commitment is not delivery.
Options (3)
ShortlistedTest the royal grant against an explicit public purpose
The Treasury says the £99.9m reflects a “granular assessment” of expected activities; publishing that remit would let later resets be tested against it.
Who: HM Treasury; Royal Trustees · Evidence: Expert or audit recommendation · Status: Announced proposal
Source: HM Treasury (deposited paper), Exchequer Secretary’s letter on the Sovereign Grant Bill, 11 September 2026 (DEP2026-0573) (Letter text on the £99.9m assessment)
Publish a fuller, auditable monarchy cost statement
Uses the Bill as the point to reconcile all costs.
Who: HM Treasury · Evidence: Untested proposal · Status: External proposal
Source: House of Commons Library, Finances of the Monarchy (CBP-9807) (Summary)
Require an NAO report and a Commons vote before any future rise
Adds scrutiny to the new reset powers.
Who: Parliament · Evidence: Untested proposal · Status: External proposal
Source: House of Commons, Sovereign Grant Bill, Committee of the whole House, 14 September 2026 (Hansard) (Amendment 1 (not pressed))
What could make it worse Threats
Unverifiable totals distort the debate in both directions: outside estimates of security costs range from several million to a hundred million pounds a year, and the Commons Library calls tourism and trade benefits highly uncertain.
Risk, not a certaintyConfidence: Moderate
Source: House of Commons Library, Finances of the Monarchy (CBP-9807) (Sections 8.1 and 8.2)
What government has committed to
No commitment found. No commitment to publish security costs or an official estimate of the monarchy’s tourism and trade benefits was found.
Searched: gov.uk search; Hansard and written statements since 20 July 2026; Sovereign Grant Bill debates; 4 Oct 2026
Checked 4 October 2026. A commitment is not delivery.
Options (2)
ShortlistedPublish a fuller, auditable monarchy cost statement
An audited security total would narrow the range of outside estimates.
Who: HM Treasury; Home Office · Evidence: Untested proposal · Status: External proposal
Source: House of Commons Library, Finances of the Monarchy (CBP-9807) (Section 8.1)
Widen the audit to value for money
Independent audit of costs reduces reliance on unverifiable claims on either side.
Who: National Audit Office · Evidence: Untested proposal · Status: External proposal
A profit-linked formula can raise the Grant for reasons unrelated to need: it rose to £137.9m for 2026–27, ahead of the planned reset.
Risk, not a certaintyConfidence: Moderate
Source: House of Commons Library, Finances of the Monarchy (CBP-9807) (Summary)
What government has committed to
Legislation: The Grant falls from £137.9m to £99.9m in 2027-28 and is expected to stay flat to 2031-32, a real-terms fall each year; the formula stays profit-linked at 20.5%.
- Who and when:
- Starmer government (to July 2026), 26 June 2026.
- Since 20 July 2026:
- Kept by the Burnham government. The reset needs Royal Assent; the 2026-27 figure stands. Source: UK Parliament, Sovereign Grant Bill (bill 4280) (Commons stages completed 14 September 2026).
- Source:
- HM Treasury (Royal Trustees), Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant Review 2026 (Paragraphs 1.11–1.12)
Checked 4 October 2026. A commitment is not delivery.
Options (2)
ShortlistedTest the royal grant against an explicit public purpose
A stated remit separates rises caused by Crown Estate profits from changes in need.
Who: HM Treasury; Royal Trustees · Evidence: Expert or audit recommendation · Status: Announced proposal
Source: HM Treasury (Royal Trustees), Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant Review 2026 (Paragraphs 1.11–1.13)
Use the reserve-band trigger to correct over-funding between reviews
Clause 3 lets the Treasury reset the Grant by regulations if the reserve goes outside 10–50% of spending.
Who: HM Treasury; Royal Trustees · Evidence: Untested proposal · Status: Announced proposal
Source: UK Parliament, Sovereign Grant Bill (bill 4280) (Clause 3 (as described in the Commons debate))
The actions worth examining
These actions concern transparency, accountability and informed choice — not a spending programme, and not a view on which party or system is right.
Action 1A27Policy status: external proposal
Publish a fuller, auditable monarchy cost statement
Reconcile all public spending linked to the monarchy into one annual taxonomy — known, overlapping and undisclosed — publishing security only as an aggregate if a breakdown is unsafe.
The thread: issue, evidence, action
- Who decides:
- HM Treasury, with the Home Office and police (security), the Royal Household and Parliament (UK)
- Evidence:
- Untested proposal. A transparency proposal; no evaluation applies. The facts on what is and is not disclosed are well documented.
- Expected effect:
- Direction plausible; size not established.
- Cost and funding
Not yet costed
Funding: Not yet costed / funding not identified
Why it is shortlisted here: The page’s central gap: the full public cost cannot be established from what is published.
What it takes
The problem
The audited Sovereign Grant is only part of the public cost: security and costs met by departments, police and councils are not reported together, so the full cost cannot be established.
Who is affected, and where
Taxpayers and Parliament across the UK. Territory: UK. Some costs fall to devolved bodies (for example Historic Environment Scotland for Holyroodhouse); a statement would need their figures.
Policy status
Proposed by researchers or others, not government policy. No consolidated statement exists. Treasury guidance states no breakdown of security costs is available because disclosure could compromise protection. The statement is a UK Facts proposal building on the Commons Library’s assembly of public figures.
The evidence
- What the research found:
- The Sovereign Grant was £132.1m in 2025–26 and £137.9m in 2026–27. The Commons Library lists other public costs (pensions, Lord-Lieutenants, event policing) and notes general security costs are not discussed publicly, with outside estimates ranging from several million to a hundred million pounds a year.
- Evaluated on:
- Public costs associated with the monarchy; United Kingdom, 2025–26 and 2026–27
- Our recommendation (separate from the research):
- Publish a reconciled taxonomy of known, overlapping and undisclosed costs each year, naming what is withheld and why.
- Strongest counter-evidence:
- Security disclosure could put people at risk; some costs (such as state events) serve wider public purposes and would exist under other arrangements; a statement proves neither value nor misconduct.
Cost and funding
Cost completeness: Not yet costed. Funding: Not yet costed / funding not identified.
- Reporting and audit work for a reconciled cost statement (administration; paid by central government): Not yet costed. Staff time in HM Treasury, the Home Office, police and councils; possibly NAO time. No saving is established.
- Who pays:
- HM Treasury and the bodies that hold the figures (staff time); possibly NAO audit time.
- Financing proposed:
- Existing departmental budgets. Staff time has an opportunity cost; it is not free.
- Gap remaining:
- Unknown: reporting and audit effort has not been costed.
What delivery needs
- Skills:
- Public-sector accountants.
- Operational capacity:
- Data from departments, police and councils.
- Infrastructure:
- None.
- Permissions:
- Royal Household cooperation.
- Law:
- No new law for a voluntary statement.
- Public consent:
- Agreement on what security information can be aggregated safely.
First step and stages
First step: Publish a reconciled taxonomy of known, overlapping and undisclosed cost categories. (owner: HM Treasury)
- Agree categories and data owners — HM Treasury (proposed stage, not an official timetable)
- Publish alongside the Sovereign Grant accounts — HM Treasury; Royal Household (proposed stage, not an official timetable)
- Audit scope reviewed — Parliament; NAO (proposed stage, not an official timetable)
Depends on: Home Office judgement on safe aggregate security reporting
Trade-offs
- Who gains and who loses:
- Benefits are better public information; costs are administrative.
- What else the money or effort could do:
- Treasury and audit time not spent on other scrutiny.
- Strongest counterargument:
- The Grant is already audited and small relative to public spending; further reporting adds cost with little decision value.
- Risks:
- Security exposure; spurious precision from adding incompatible categories.
How we would judge it
- Baseline:
- Sovereign Grant £132.1m (2025–26); security costs not published.
- Leading indicator:
- Publication of a reconciled statement.
- Outcome:
- Fewer undisclosed categories each year; audit findings.
- Continue, adapt or stop:
- Review if the statement omits the same categories that are unknown now.
Earlier option on this page
This card replaces the option “An annual statement of all public costs” (proposed). Its evidence: No such statement exists; the House of Commons Library briefing assembles what is public and notes what is not. House of Commons Library, Finances of the Monarchy
Sources
- House of Commons Library, Finances of the Monarchy (CBP-9807), Summary; section 8.1 (2026-06-05; relevant passages checked)
- HM Treasury, Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant 2025–26, Report section (2025; full text checked)
- UCL Constitution Unit, The British Monarchy: FAQs, FAQ “How is the monarchy financed?” (2025-11 (live explainer); full text checked)
- House of Commons Library, Finances of the Monarchy (CBP-9807), Section 8.1 (Treasury guidance on security) (2026-06-05; relevant passages checked)
Source published June 2026 (Commons Library); 2025 (Royal Trustees); evidence reviewed 2026-10-04. Reconsider if: The Sovereign Grant Bill is published; A tribunal or government decision on security disclosure.
Action 2A28Policy status: announced proposal
Test the royal grant against an explicit public purpose
Compare the current formula with a needs-based settlement against a stated remit, with maintenance, staffing and transition costs, and let Parliament decide on that evidence.
The thread: issue, evidence, action
- Issue Threat: A profit-linked formula can raise the Grant for reasons unrelated to need: it rose to £137.9m for 2026–27, ahead of the planned reset. Also: opportunity, strength
- Evidence Sovereign Grant
- Action A28, this action
- Who decides:
- The Royal Trustees (Prime Minister, Chancellor, Keeper of the Privy Purse) and Parliament (UK)
- Evidence:
- Expert or audit recommendation. An institutional policy choice: official reports describe the formula; no evaluation compares it with a needs-based settlement.
- Expected effect:
- Direction plausible; size not established.
- Cost and funding
Not yet costed
Funding: Not yet costed / funding not identified
Why it is shortlisted here: The formula is under review and new legislation is planned, so the remit question is live.
What it takes
The problem
The Sovereign Grant follows Crown Estate profits with a lag, so it can rise sharply for reasons unrelated to need — as offshore wind income showed.
Who is affected, and where
Taxpayers and Parliament across the UK. Territory: UK. The Sovereign Grant Act 2011 is UK legislation; Crown Estate Scotland is separate.
Policy status
Announced by government, not yet in place. The Royal Trustees’ five-yearly review reported on 26 June 2026: the Grant resets to £99.9m from 2027–28 with a reference percentage of 20.5%. The Sovereign Grant Bill to enact this was introduced on 1 September 2026, passed all its Commons stages on 14 September and is in the Lords; it is not yet law. A needs-based comparison against an explicit remit is a UK Facts proposal.
The evidence
- What the research found:
- The 2025–26 Grant of £132.1m was 12% of 2023–24 Crown Estate income (£1,100.7m); the 2023 review cut the percentage from 25% to 12%. The government intends to reduce the Grant from 2027–28 once £100.3m of remaining reservicing funding has been provided.
- Evaluated on:
- The Sovereign Grant, 2012–13 to 2026–27; United Kingdom
- Our recommendation (separate from the research):
- Map the legal formula and the announced Bill first; then publish a needs-based comparison with a stated remit and transition costs.
- Strongest counter-evidence:
- A formula gives stability and keeps decisions at arm’s length from ministers; constitutional preferences are value choices; claimed tourism benefits and costs are both highly uncertain.
Cost and funding
Cost completeness: Not yet costed. Funding: Not yet costed / funding not identified.
- Review and transition costs of an alternative Grant settlement (administration; paid by central government): Not yet costed. Maintenance and staffing implications of each option are not published. No tourism dividend or automatic saving is assumed.
- Who pays:
- Taxpayers through the Grant; the review itself uses Treasury and Royal Household staff time.
- Financing proposed:
- Not a financing source. A lower Grant saves money only if spending actually falls without moving to another public body.
- Gap remaining:
- Unknown: maintenance and transition implications of alternatives are not published.
What delivery needs
- Skills:
- Estate and finance expertise.
- Operational capacity:
- Independent review capacity.
- Infrastructure:
- Estate condition data.
- Permissions:
- Royal Household cooperation.
- Law:
- Amending the Sovereign Grant Act 2011.
- Public consent:
- Parliamentary support; public opinion is divided.
First step and stages
First step: Publish the current formula, the announced reset and the estate’s maintenance needs side by side. (owner: HM Treasury (Royal Trustees))
- Complete the 2026 review (begun in 2026) with published reasoning — Royal Trustees
- Parliament considers the Sovereign Grant Bill — Parliament (proposed stage, not an official timetable)
- Publish a transition and audit the outcome — HM Treasury; NAO (proposed stage, not an official timetable)
Depends on: A27: a fuller cost statement; The Sovereign Grant Bill
Trade-offs
- Who gains and who loses:
- Small effects on public finances either way; mainly a question of accountability and constitutional preference.
- What else the money or effort could do:
- Parliamentary time for legislation.
- Strongest counterargument:
- Linking the Grant to need invites annual political bargaining over the head of state’s funding.
- Risks:
- Deferred estate maintenance if the Grant falls too far; cost shifting to departments.
How we would judge it
- Baseline:
- Sovereign Grant £132.1m in 2025–26; £137.9m in 2026–27.
- Leading indicator:
- Published review reasoning and Bill provisions.
- Outcome:
- Audited public cost, estate condition and performance against the stated remit.
- Continue, adapt or stop:
- Revisit if the Grant moves with property income regardless of need after the reset.
Earlier option on this page
This card replaces the option “Review the Sovereign Grant formula” (operating: Periodic reviews under the Sovereign Grant Act 2011. The 2026 review reported on 26 June 2026 (Grant reset to £99.9m from 2027–28; reference percentage 20.5%), and the Sovereign Grant Bill giving effect to it was introduced on 1 September 2026.). Its evidence: The Grant is set as a percentage of Crown Estate profit two years earlier and reviewed periodically by the Royal Trustees; no evaluation compares this with a needs-based approach. HM Treasury, Report of the Royal Trustees on the Sovereign Grant 2025–26
Sources
- HM Treasury, Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant 2025–26, Report section; Annex A step 1; Annex B (2025; full text checked)
- House of Commons Library, Finances of the Monarchy (CBP-9807), Summary (2026-06-05; relevant passages checked)
- UCL Constitution Unit, The British Monarchy: FAQs, FAQ “How is the monarchy financed?” (2025-11 (live explainer); full text checked)
- House of Commons Library, Finances of the Monarchy (CBP-9807), Section 8.2 (2026-06-05; relevant passages checked)
Source published 2025 (Royal Trustees); June 2026 (Commons Library); evidence reviewed 2026-10-04. Reconsider if: Publication of the Sovereign Grant Bill; The 2026 Royal Trustees review report.
Decision brief
The leading option set out as a decision someone could take: who decides, who benefits, the best evidence, cost and funding, and the main trade-off. The full research record is one click away.
Decision briefStatutory/accountability reformReviewed 2026-10-04
Publish one statement of what the monarchy costs the public, then compare grant rules on it
The thread: issue, evidence, action
- Decision required
- HM Treasury publishes, beside the annual Sovereign Grant report, a reconciled statement of every public cost linked to the monarchy — audited, known but held elsewhere, and undisclosed — and the Royal Trustees publish the grant-rule options for the forthcoming Sovereign Grant Bill on that same cost basis.
- Who and where
- UK taxpayers and Parliament. Applies in: UK.
- Accountable body
- HM Treasury (Royal Trustees: the Prime Minister, the Chancellor and the Keeper of the Privy Purse); Parliament through the Bill
- Intervention
- Reconcile every public cost into one dated statement and cost each grant rule on the same expected-cost basis.
- Best evidence, and where it applies
- The Commons Library shows the audited Sovereign Grant is only part of the public cost and that security costs are not published; the Netherlands already presents related spending across ministries in one budget annex.Studied in: Public spending linked to the monarchy (Public figures to 2026–27).How closely the comparison transfers to this decision: Netherlands — high.
- Extra cost of this change
- Capital: none identified in the brief.Recurring: Reporting and audit work for the reconciled statement — Not yet costed.One-off or mixed: Costing alternative grant rules — Not yet costed.
- Funding
- Mainly a legal or regulatory change: administration costs still need a budget.Committed to this change: none.Possible source, not an award: none identified.Unfunded: Reporting and audit effort not costed.
- Savings and wider benefits
- Not yet specified: no cashable saving or avoided cost has been costed for this change. Expected outcomes are listed one by one in the research appendix and are never added together or counted as money available.
- First 90-day step
- HM Treasury publishes the cost taxonomy (audited / known elsewhere / undisclosed) and the grant-rule comparison before the Sovereign Grant Bill’s committee stageThe proposed first milestone; a 90-day date is not yet specified. Owner: HM Treasury. Proposed by UK Facts, not an official deadline.
- Twelve-month milestone
- Not yet specified.Time to a first useful result: Before Parliament votes on the Bill; the first full statement with the next Sovereign Grant report.
- Outcome, and when to scale or stop
- Measure: Publication of the taxonomy and the options comparison.Scale if: Each year’s statement covers more categories on a consistent basis and the NAO can audit it.Stop if: Not a stop decision: if the statement keeps omitting the same categories, Parliament should ask why.
- Main trade-off
- A fuller statement costs staff time and can never be complete while security stays undisclosed; without it, debate swings between the Grant alone and unverifiable outside estimates.
- Source and review date
- Finances of the Monarchy (CBP-9807) (5 June 2026); Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant Review 2026 (June 2026). Reviewed 2026-10-04.
An editorial proposal by UK Facts for discussion, not government policy. Records: A27, A28 · costs C-A27-STATEMENT, C-A28-REVIEW
Research appendix: study design, effect sizes and limits, alternatives, full costing, international comparisons and how we would know
1.The change, in plain words
Publish one statement of what the monarchy costs the public, then compare grant rules on it
2.The decision requested
- Decision
- Commit, during the passage of the Sovereign Grant Bill, to (1) an annual reconciled public-cost statement in three columns — audited, known but held by other bodies, undisclosed — and (2) a published comparison of the 20.5% formula with at least two alternatives (a fixed needs-based settlement and an indexed amount) costed on the Trustees’ own expected-cost figures.
- Accountable institution
- HM Treasury (Royal Trustees: the Prime Minister, the Chancellor and the Keeper of the Privy Purse); Parliament through the Bill
- Geography
- UK
- Powers
- The statement needs no legislation; the Treasury can publish it under existing authority. Changing the Grant rule needs the Sovereign Grant Bill the government has committed to introduce.
- Delivery partners
- Royal Household (Keeper of the Privy Purse); Home Office and police (security aggregate); Departments and councils that meet related costs; National Audit Office; House of Commons Public Accounts Committee
3.Who it is for, and what changes beyond today
- Target population
- UK taxpayers and Parliament.
- Eligibility
- All public spending linked to the monarchy: the Sovereign Grant; costs met by departments (for example state visits and royal travel not covered by the Grant); police and council costs of events; pensions and Lord-Lieutenants; security (aggregate only, if safe).
- Scale
- One annual statement and one options comparison before the Bill’s committee stage.
- Baseline
- Sovereign Grant £132.1m in 2025–26 and £137.9m in 2026–27. The 2026 review changed the reference percentage from 12% to 20.5% of Crown Estate revenue account profit, and the government will legislate for a Grant of £99.9m from 2027–28, flat to 2031–32. Security costs are not published; outside estimates range from several million to a hundred million pounds a year.
Source: HM Treasury (Royal Trustees), Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant Review 2026 (Paragraphs 1.12 and 6.5); House of Commons Library, Finances of the Monarchy (CBP-9807) (Summary; section 8.1)
- Change beyond existing law or funding
- Today the Grant is audited and reported annually and the Trustees set the formula from expected costs, but other public costs are reported (if at all) by each body separately and no alternative grant rule is published. The change adds the reconciled statement and the published options comparison; it does not change the amount.
4.How it would work
Do: Reconcile every public cost into one dated statement and cost each grant rule on the same expected-cost basis Changing: so that Parliament votes on the Bill knowing the full known cost, the undisclosed categories and what each rule would pay
Fewer undisclosed cost categories each year
Hypothesis to test
An accountability output; security is expected to remain undisclosed or aggregate only.
Grant settlements that track the Household’s stated needs rather than Crown Estate windfalls
Hypothesis to test
The 2023–2026 offshore-wind income showed the formula can move for reasons unrelated to need; no evaluation compares rules.
Outcomes are kept separate and never added into one impact figure.
5.Best evidence
Finances of the Monarchy (CBP-9807)
- Author or institution:
- House of Commons Library (David Torrance, Lorna Booth)
- Published:
- 5 June 2026
- Evaluation period:
- Public figures to 2026–27
- Design:
- Parliamentary research briefing assembling official figures
- Sample or population:
- Public spending linked to the monarchy
- Effect and uncertainty:
- Lists costs beyond the Grant (pensions, Lord-Lieutenants, event policing); general security costs are not published and outside estimates range from several million to a hundred million pounds a year.
- Limits:
- Assembles figures; does not reconcile them into one total, and cannot cost security.
Where: Summary; section 8.1. Affiliation is provenance, not proof of quality.
Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant Review 2026
- Author or institution:
- Royal Trustees (HM Treasury)
- Published:
- June 2026
- Evaluation period:
- Review of 2023–24 to 2025–26; expected costs 2026–27 to 2031–32
- Design:
- Statutory five-yearly review
- Sample or population:
- The Sovereign Grant and the occupied royal palaces
- Effect and uncertainty:
- Reference percentage set at 20.5% so that the Grant (£99.9m from 2027–28) meets expected costs; continuing at 12% would leave funding “significantly lower than the Household’s needs”.
- Limits:
- Considers one rule (the formula) at different percentages; alternatives are not published.
Where: Chapter 4; paragraphs 6.3–6.6. Affiliation is provenance, not proof of quality.
6.Alternatives, counter-evidence and who loses
- Closest feasible alternative
- Pass the Bill as proposed and rely on the existing Sovereign Grant report and the Commons Library’s periodic assembly of other costs.
- Strongest counter-evidence
- Security disclosure could put people at risk; some costs (state events, visits) serve wider public purposes and would exist under any head of state; a statement proves neither value for money nor misconduct.
Source: House of Commons Library, Finances of the Monarchy (CBP-9807) (Summary)
- Distributional effects
- Small effects on public finances either way; the main effect is on what Parliament and the public can know.
- Main downside
- Adding incompatible categories can create spurious precision; the statement must show categories separately and never imply a single complete total while security is undisclosed.
| Option | Who is reached | Evidence | Likely outcome and timing | Cost and funding | Main trade-off |
|---|---|---|---|---|---|
| The proposalReconciled cost statement + published grant-rule comparison before the Bill | Taxpayers and Parliament | Commons Library assembly of costs; Dutch budget annex | Before the Bill’s committee stage; annually after | Staff time, not costed | Never complete while security is undisclosed |
| Current policyCurrent policy: Grant reset to £99.9m at 20.5% by the Bill; other costs reported separately | Taxpayers and Parliament | Royal Trustees 2026 review | Lower Grant from 2027–28; next review 2031 | Grant set by formula | Full cost and alternative rules not visible |
| AlternativeFixed needs-based settlement voted by Parliament every five years | Taxpayers and Parliament | Untested in the UK since 2011 | From the next review | Would need the Trustees’ cost plan | More political involvement in royal funding |
The options compared, including current policy
The proposal
Reconciled cost statement + published grant-rule comparison before the Bill
- Who is reached
- Taxpayers and Parliament
- Evidence
- Commons Library assembly of costs; Dutch budget annex
- Likely outcome and timing
- Before the Bill’s committee stage; annually after
- Cost and funding
- Staff time, not costed
- Main trade-off
- Never complete while security is undisclosed
Current policy
Current policy: Grant reset to £99.9m at 20.5% by the Bill; other costs reported separately
- Who is reached
- Taxpayers and Parliament
- Evidence
- Royal Trustees 2026 review
- Likely outcome and timing
- Lower Grant from 2027–28; next review 2031
- Cost and funding
- Grant set by formula
- Main trade-off
- Full cost and alternative rules not visible
Alternative
Fixed needs-based settlement voted by Parliament every five years
- Who is reached
- Taxpayers and Parliament
- Evidence
- Untested in the UK since 2011
- Likely outcome and timing
- From the next review
- Cost and funding
- Would need the Trustees’ cost plan
- Main trade-off
- More political involvement in royal funding
7.What other countries or the devolved nations show
Country lesson · Netherlands, Consolidated from the 2010 budget; current example the 2026 budget
Putting the cost of the monarchy in one budget chapter in the Netherlands
Evidence: Expert or audit recommendationClose match to the UK decision
- What was changed
- The King’s budget chapter brings together the constitutional allowances, the Royal Household’s functional costs and costs recharged from other ministries, and an annex lists related spending that stays on other ministries’ budgets (palaces, state visits, security), so the full set can be read in one place.
- Study design and population
- Budget presentation reform following a government steering-group review; no evaluation of its effects. Dutch Parliament and the public
- Measured outcome there
- Administrative result, not an evaluated effect: in 2026 the chapter totals €60.8m in three articles (allowances €12.571m; functional costs €39.806m; recharged costs €8.415m), with other ministries’ related spending listed in an annex. Security is deliberately not attributed.
- Cost status
- The cost of producing the statement is not published; it uses existing budget processes.
- What failed or remains uncertain
- Security — likely the largest uncosted item — is still not attributed, so the statement is not a full cost. Whether consolidation changed public trust or spending was not evaluated.
- Why the UK differs
- The UK Sovereign Grant is set by formula from Crown Estate profits and audited separately; the Royal Household also has private income (the Duchy of Lancaster). Departmental and police costs are spread across UK, devolved and local budgets. Euro totals are not comparable with UK figures.
- First change required here
- HM Treasury publishes an annual annex beside the Sovereign Grant report listing every public cost linked to the monarchy, by budget holder, with security stated as “not attributed” if a figure is unsafe.
Not a UK forecast: the effect above was measured in that place and population. Source: Government of the Netherlands (Ministry of General Affairs), via rijksfinancien.nl, Memorie van toelichting, begroting I De Koning 2026 (explanatory memorandum to the 2026 budget chapter “The King”) (Tables 3, 5, 8 and the extra-accounting annex); Government of the Netherlands, via rijksfinancien.nl, Memorie van toelichting, begroting I De Koningin 2010 (explanatory memorandum to the 2010 budget chapter) (Budget structure). Reviewed 2026-10-04.
8.What delivery needs first
- data — Each department, police force and council that meets a related cost must report it on a common basis. (Requirement; owner: HM Treasury)
- law — A change to the Grant rule needs the Sovereign Grant Bill; the statement does not. (Genuine veto: nothing proceeds without it; owner: Parliament)
- dependency — The Home Office and police decide whether any security aggregate is safe to publish. (Genuine veto: nothing proceeds without it; owner: Home Office)
9.What it would cost
How the cost is built up: Treasury, departmental, police and council staff time to report + NAO audit time + Treasury time to cost alternative rules. No saving is assumed.
| Component | Unit and quantity | Unit cost or amount | Type, price year, period | Status |
|---|---|---|---|---|
| Reporting and audit work for the reconciled statementAll public spending linked to the monarchy | staff time per year; quantity to be set from need and capacity | Not yet costed (ledger C-A27-STATEMENT) | recurring; price year not stated; Annual | Not yet established |
| Costing alternative grant rulesThe Sovereign Grant and the occupied royal palaces | one options analysis; quantity to be set from need and capacity | Not yet costed (ledger C-A28-REVIEW) | one-off revenue; price year not stated; Before the Bill’s committee stage | Not yet established |
Reporting and audit work for the reconciled statement
All public spending linked to the monarchy
Not yet costed (ledger C-A27-STATEMENT)
recurring; price year not stated; Annual; Not yet established
Costing alternative grant rules
The Sovereign Grant and the occupied royal palaces
Not yet costed (ledger C-A28-REVIEW)
one-off revenue; price year not stated; Before the Bill’s committee stage; Not yet established
10.Who pays, and what is missing
- Programme envelope (a possible route, not an award)
- None identified
- Allocation committed to this change
- None
- Remaining gap
- Reporting and audit effort not costed.
- Proposed financing
- Existing departmental administration budgets.
- Responsible payer
- central government
- Budget displaced
- Staff time in HM Treasury and the reporting bodies.
11.First milestone and time to a useful result
HM Treasury publishes the cost taxonomy (audited / known elsewhere / undisclosed) and the grant-rule comparison before the Sovereign Grant Bill’s committee stage (Owner: HM Treasury. Proposed by UK Facts, not an official deadline.)
Time to first useful result: Before Parliament votes on the Bill; the first full statement with the next Sovereign Grant report.
What could delay it: The Bill timetable moves Bodies holding related costs report on different bases Security advice rules out even an aggregate
12.How we would know
- Baseline
- Sovereign Grant £137.9m (2026–27) audited; other costs reported separately or not at all; security undisclosed.
- Comparison
- The categories left unknown in the first statement.
- Leading indicator
- Publication of the taxonomy and the options comparison.
- Follow-up
- Each annual Sovereign Grant report; the next review in 2031.
- Continue if
- Each year’s statement covers more categories on a consistent basis and the NAO can audit it.
- Adapt if
- Bodies cannot report on a common basis — then publish their figures separately with the reason.
- Stop if
- Not a stop decision: if the statement keeps omitting the same categories, Parliament should ask why.
- Thresholds
- Not yet set: An accountability publication; no numerical threshold is justified.
What is not yet known, and how to find out
- What the statement and audit would cost each year (cost)Next step: HM Treasury to scope the data request to departments, police and councils and ask the NAO for audit days.Scope: All linked public costs, annually · Data or quotes needed: Staff time estimates from each reporting body · Who can estimate it: HM Treasury with the NAO
- What alternative grant rules would pay over 2027–32 (cost)Next step: Cost each rule on the Trustees’ Chapter 4 expected-cost figures.Scope: Sovereign Grant 2027–28 to 2031–32 · Data or quotes needed: Expected costs and Crown Estate profit projections · Who can estimate it: HM Treasury (Royal Trustees)
- Whether any security aggregate can be published safely (legal)Next step: Home Office to advise; if not, the statement records the category as “not attributed”, as the Netherlands does.
Sources last checked 4 October 2026 · Owner: Evidence editor (James Harris) · Next check: the first trigger: Sovereign Grant annual report and accounts.
What it would take
The order things have to happen in
First, the prerequisite
Five-yearly review of the Grant percentage
Owner: Royal Trustees
Commenced 2026 — source
Then, the decision
Sovereign Grant Bill: reset after the reservicing and a mechanism for future reductions
Owner: HM Treasury; Parliament
Session 2026–27 (government intention) — source
Then, delivery
Publish a reconciled statement of known, overlapping and undisclosed costs
Owner: HM Treasury, with the Home Office and Royal Household
No date: the timing depends on the steps before it.
Finally, the measured outcome
Fewer undisclosed categories; audited cost against the stated remit
Owner: Parliament; NAO
No date: the timing depends on the steps before it.
Who pays, and what is still missing
Cost, committed funding and the remaining gap for the same scope and years. A programme envelope is not an award to a project; a proposal is not committed money. None of these costs has been established yet, so no total is shown.
Cost and funding ledger
Reporting and audit work for a reconciled cost statement
A27 · administration · not costed
- Amount
- Not yet costed
- Who pays
- central government
- Committed
- None identified
- Proposed, not committed
- —
- Gap
- Not established
Review and transition costs of an alternative Grant settlement
A28 · administration · not costed
- Amount
- Not yet costed
- Who pays
- central government
- Committed
- None identified
- Proposed, not committed
- —
- Gap
- Not established
“Not yet costed” means no defensible cost has been found — not that the action is free. Lifetime benefits, benefit-cost ratios and forecast savings are never shown here as money available to spend.
What the evidence says each action changes
No effect has been established for these actions yet: direction plausible; size not established.
How we would know
The outcome measures to watch. A baseline is where we start, not a target; where there is no official target we say so.
Sovereign Grant
£m, cash · United Kingdom
- Baseline
- Not published
- Latest
- £132.1m
- 2025–26
Target: none — no target; already set at £137.9m for 2026–27, and the government intends to lower it once reservicing funding ends.
Source: HM Treasury, Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant 2025–26 (Report section, fourth paragraph). Next release: Royal Trustees report and Sovereign Grant accounts each year (check the release calendar).
Royal security cost published
£m · United Kingdom
- Baseline
- Not published
- Latest
- Not published
- as at June 2026
Target: none — no commitment to publish.
Source: House of Commons Library, Finances of the Monarchy (CBP-9807) (Section 8.1). Next release: no scheduled publication (check the release calendar).
Where the ideas come from
Research, counter-evidence and methods (5 sources; 2 claims held back)
- Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant 2025–26 — HM Treasury, 2025.Statutory report; United Kingdom. Full text checked, 2026-10-04.
- The British Monarchy: FAQs — UCL Constitution Unit, 2025-11 (live explainer).Constitutional explainer. Full text checked (read from an Internet Archive copy), 2026-10-04. Limits: Does not discuss security costs or tourism, so it is not cited for either. Its financial figures predate the 2025–26 Grant; current amounts come from the Royal Trustees’ report and the Commons Library.
- Sovereign Grant Act 2011: Report of the Royal Trustees on the Sovereign Grant Review 2026 — HM Treasury (Royal Trustees), 2026-06.Statutory review report; United Kingdom. Full text checked, 2026-10-04.
- Finances of the Monarchy (CBP-9807) — House of Commons Library (David Torrance, Lorna Booth), 2026-06-05.Parliamentary research briefing; United Kingdom. Relevant passages checked (read from an Internet Archive copy), 2026-10-04.
- Sovereign Grant Bill (bill 4280) — UK Parliament, 2026-09-01.Bill before Parliament (Burnham government). Full text checked, 2026-10-04. Limits: Introduced 1 September 2026 by HM Treasury; all Commons stages 14 September 2026; in the Lords (second reading stage at 4 October 2026). Sets the 2027-28 Grant at £99.9m and the reference percentage at 20.5%; clause 3 reserve-band trigger for a reset.
Counter-evidence and criticism
- Publish a fuller, auditable monarchy cost statement: Security disclosure could put people at risk; some costs (such as state events) serve wider public purposes and would exist under other arrangements; a statement proves neither value nor misconduct. (House of Commons Library)
- Test the royal grant against an explicit public purpose: A formula gives stability and keeps decisions at arm’s length from ministers; constitutional preferences are value choices; claimed tourism benefits and costs are both highly uncertain. (House of Commons Library)
Claims held back
- Undisclosed security costs and speculative tourism arguments (brief threat, cited to S20) — The UCL FAQ does not discuss security or tourism. Needed: Re-sourced to the Commons Library briefing (sections 8.1–8.2); no estimate of either is published here.
- A total public cost of the monarchy — Security and some other costs are undisclosed, so any total would be invented. Needed: An official reconciled statement (action A27).
“Full text checked” means we read the report itself; “relevant passages” means the sections behind each figure; “summary or abstract only” means we could not read the full study, so no number from it is published here without another source.
Other options compared — not on the shortlist (1)
Other options compared
Options from earlier work on this page that are not on the shortlist. They remain valid choices; their evidence is shown as before.
- structuralStatus: proposed
Wider audit scope
- Aims to:
- Independent assurance over spending outside the Grant.
- How:
- Extend National Audit Office access to related costs and to the Royal Household’s use of public funds beyond the Grant accounts.
- Who decides:
- Parliament; National Audit Office.
- Main constraint:
- Legal basis for access.
- Evidence:
- Not evaluated — a mechanism to test, not an evidenced fix
See the trade-offs and evidence
- What the evidence shows
- The Grant accounts are audited; related costs elsewhere are covered only within each body’s own accounts.
- Resources
- NAO time.
- Consent and decisions needed
- Parliamentary support needed.
- Time
- One to two years.
- Cost and yield
- Small.
- Trade-offs and who pays
- Limited direct effect on spending.
- How we would know it worked
- Leading indicator: Audit reports published. Outcome: Clearer value-for-money evidence. It would not be working if: Reports cannot obtain the needed information.
| Option | Resources | Time | Evidence | Outcome to watch |
|---|---|---|---|---|
| Wider audit scope | NAO time. | One to two years. | not evaluated | Clearer value-for-money evidence. |
Plan reviewed 2026-10-04. How we judge evidence.
How this connects
- How big is £132m in the public finances?
The Grant is a very small share of public spending; scale matters for the debate.
- What is known and unknown, at a glance?
A one-page scale check of the disclosed and undisclosed costs.
- Who decides the Grant?
Ministers, as Royal Trustees, and Parliament set the framework.