1996
£48,693
Mean purchase price
- Mean mortgage
- £43,867
- Mean loan-to-value
- 90.11%
Deposit illustration
£4,816
Using this price and 9.89% cash; not the observed average deposit.
Housing · England · 2025
Buying is out of reach for many. High rents and too few suitable, affordable homes leave families with limited choices — and some without a settled home.
Priority: Increase access to affordable, secure, suitable homes; compare supply, social housing and prevention. What would change it →
Evidence last reviewed 8 October 2026
Overview
The price of buying
7.6times earnings
House price ÷ full-time annual pay. 3.5× in 1997; this is not a mortgage lending limit.
England · 2025
Official statistic · ONS, Housing affordability in England and Wales: 2025, dataset Table 1c
The cost of renting
36.3%
Mean private rent ÷ median gross renter-household income. 41.6% in London.
England · 2023–24
Official statistic · ONS, Private rental affordability, England, Wales and Northern Ireland: 2024, dataset Table 3
Children without a settled home
177,530children
In council-arranged temporary accommodation; 135,580 households in total. Provisional.
England · March 2026
Provisional · MHCLG, Statutory homelessness: England time series, Table TA1
The evidence
01 · Buying
A lower house-price ratio does not necessarily mean an affordable monthly payment. Start with the price, then follow the money needed to buy.
How many years of pay does a typical home cost?
England · median house price ÷ median full-time annual earnings. The early earnings basis differs in 1997–98.
1996–2026 displayed window · observations only. Shading marks years outside the displayed record.
Source: ONS, Housing affordability in England and Wales: 2025, dataset Table 1c (released 26 March 2026). Chart HOUSE-01.
| Year | Ratio |
|---|---|
| 1997 | 3.54 |
| 1998 | 3.67 |
| 1999 | 3.96 |
| 2000 | 4.19 |
| 2001 | 4.50 |
| 2002 | 5.12 |
| 2003 | 5.93 |
| 2004 | 6.60 |
| 2005 | 6.79 |
| 2006 | 6.95 |
| 2007 | 7.15 |
| 2008 | 6.97 |
| 2009 | 6.40 |
| 2010 | 6.85 |
| 2011 | 6.80 |
| 2012 | 6.77 |
| 2013 | 6.76 |
| 2014 | 7.09 |
| 2015 | 7.54 |
| 2016 | 7.72 |
| 2017 | 7.91 |
| 2018 | 8.04 |
| 2019 | 7.88 |
| 2020 | 7.86 |
| 2021 | 9.06 |
| 2022 | 8.56 |
| 2023 | 8.45 |
| 2024 | 7.84 |
| 2025 | 7.63 |
How much did first-time buyers borrow against income?
UK · loan-to-income ratio for completed first-time buyer mortgages. Two sources; not one continuous series.
1996–2026 displayed window · observations only. Shading marks years outside the displayed record.
Archive source: Table 517 (XLS). Survey changes in 2003 and 2005; sources overlap in 2006–10.
Source: ONS, First-time buyer mortgage sales by local authority: UK, 2b, United Kingdom. Chart HOUSE-FTB.
| Year | Archived Table 517 | ONS/FCA Table 2b |
|---|---|---|
| 1996 | 2.42 | — |
| 1997 | 2.43 | — |
| 1998 | 2.41 | — |
| 1999 | 2.44 | — |
| 2000 | 2.46 | — |
| 2001 | 2.52 | — |
| 2002 | 2.679 | — |
| 2003 | 2.96 | — |
| 2004 | 3.36 | — |
| 2005 | 3.39 | — |
| 2006 | 3.2 | 3.25 |
| 2007 | 3.35 | 3.39 |
| 2008 | 3.247 | 3.28 |
| 2009 | 3.017 | 3.11 |
| 2010 | 3.073 | 3.23 |
| 2011 | — | 3.21 |
| 2012 | — | 3.27 |
| 2013 | — | 3.34 |
| 2014 | — | 3.43 |
| 2015 | — | 3.44 |
| 2016 | — | 3.56 |
| 2017 | — | 3.62 |
| 2018 | — | 3.66 |
| 2019 | — | 3.67 |
| 2020 | — | 3.71 |
| 2021 | — | 3.75 |
| 2022 | — | 3.79 |
| 2023 | — | 3.47 |
| 2024 | — | 3.47 |
| 2025 | — | 3.62 |
The next hurdle: cash up front
UK first-time buyers · nominal pounds. The archive gives means; the current release gives medians. The different measures provide context, not a precise growth rate.
1996
£48,693
Mean purchase price
Deposit illustration
£4,816
Using this price and 9.89% cash; not the observed average deposit.
2025
£240,000
Median purchase price
Deposit illustration
£34,512
Using this price and 14.38% cash; not the observed average deposit.
Deposits were not fixed at 10%. The median first-time buyer LTV was 90% in 2007. Some products went further: Northern Rock’s Together combined a mortgage with an unsecured loan, allowing total borrowing up to 125% of the property value.
Successful UK mortgage buyers only, not all homes or people unable to buy. Archive: Table 513 (price and advance) and Table 517 (case-level LTV). Current: ONS/FCA tables 2a, 3b and 3c. Means and medians are not interchangeable. The cash illustration applies each period’s published LTV to its price, assumes valuation equals price, and excludes fees and taxes. Separate medians must not be subtracted to claim a median deposit.
High-LTV products were not the typical loan and do not, on their own, explain the financial crisis. Northern Rock also depended on wholesale funding that dried up.
Commons Library: Northern RockSeparate savings illustration: Under the same two-earner saving rule, a 10% deposit takes 21 months in 1997 and 46 in 2025: 25 extra months (+116%). A fictional family and an illustrative calculation using ONS data.
The saving model, assumptions and illustrated story →What does the size of your deposit change?
UK · quoted two-year fixed rates, 1996–Sept 2026. LTV is the share of the property price borrowed.
1996–2026 displayed window · observations only. Shading marks years outside the displayed record.
Source: Bank of England, quoted household interest rates, IUMBV34 (75%), IUMB482 (90%), IUM2WTL (95%). Chart HOUSE-LTV.
| Month | 75% LTV (%) | 90% LTV (%) | 95% LTV (%) |
|---|---|---|---|
| Jan 1996 | 6.7 | Not available | 6.7 |
| Feb 1996 | 6.65 | Not available | 6.65 |
| Mar 1996 | 6.49 | Not available | 6.49 |
| Apr 1996 | 6.62 | Not available | 6.62 |
| May 1996 | 7.01 | Not available | 7.01 |
| Jun 1996 | 7.06 | Not available | 7.06 |
| Jul 1996 | 7.12 | Not available | 7.12 |
| Aug 1996 | 7.09 | Not available | 7.09 |
| Sept 1996 | 7.06 | Not available | 7.06 |
| Oct 1996 | 6.96 | Not available | 6.96 |
| Nov 1996 | 6.94 | Not available | 6.94 |
| Dec 1996 | 7.24 | Not available | 7.27 |
| Jan 1997 | 7.29 | Not available | 7.35 |
| Feb 1997 | 7.35 | Not available | 7.41 |
| Mar 1997 | 7.11 | Not available | 7.18 |
| Apr 1997 | 7.24 | Not available | 7.3 |
| May 1997 | 7.15 | Not available | 7.2 |
| Jun 1997 | 7.14 | Not available | 7.19 |
| Jul 1997 | 7.2 | Not available | 7.23 |
| Aug 1997 | 7.17 | Not available | 7.19 |
| Sept 1997 | 7.06 | Not available | 7.09 |
| Oct 1997 | 7.07 | Not available | 7.1 |
| Nov 1997 | 7.04 | Not available | 7.06 |
| Dec 1997 | 7.13 | Not available | 7.33 |
| Jan 1998 | 7.13 | Not available | 7.33 |
| Feb 1998 | 7.08 | Not available | 7.32 |
| Mar 1998 | 7.02 | Not available | 7.26 |
| Apr 1998 | 7.14 | Not available | 7.28 |
| May 1998 | 7.12 | Not available | 7.35 |
| Jun 1998 | 6.94 | Not available | 7.24 |
| Jul 1998 | 7.08 | Not available | 7.35 |
| Aug 1998 | 7.33 | Not available | 7.55 |
| Sept 1998 | 7.27 | Not available | 7.49 |
| Oct 1998 | 6.91 | Not available | 7.01 |
| Nov 1998 | 6.66 | Not available | 6.82 |
| Dec 1998 | 6.42 | Not available | 6.54 |
| Jan 1999 | 5.9 | Not available | 5.97 |
| Feb 1999 | 5.78 | Not available | 5.88 |
| Mar 1999 | 5.64 | Not available | 5.95 |
| Apr 1999 | 5.71 | Not available | 5.89 |
| May 1999 | 5.72 | Not available | 5.96 |
| Jun 1999 | 5.89 | Not available | 6 |
| Jul 1999 | 6 | Not available | 6.17 |
| Aug 1999 | 6.19 | Not available | 6.36 |
| Sept 1999 | 6.22 | Not available | 6.45 |
| Oct 1999 | 6.5 | Not available | 6.79 |
| Nov 1999 | 6.6 | Not available | 6.77 |
| Dec 1999 | 6.52 | Not available | 6.84 |
| Jan 2000 | 6.78 | Not available | 6.9 |
| Feb 2000 | 6.79 | Not available | 6.97 |
| Mar 2000 | 6.45 | Not available | 6.68 |
| Apr 2000 | 6.31 | Not available | 6.64 |
| May 2000 | 6.39 | Not available | 6.52 |
| Jun 2000 | 6.46 | Not available | 6.65 |
| Jul 2000 | 6.37 | Not available | 6.59 |
| Aug 2000 | 6.35 | Not available | 6.58 |
| Sept 2000 | 6.31 | Not available | 6.6 |
| Oct 2000 | 6.05 | Not available | 6.45 |
| Nov 2000 | 6.06 | Not available | 6.29 |
| Dec 2000 | 6.03 | Not available | 6.22 |
| Jan 2001 | 5.78 | Not available | 6 |
| Feb 2001 | 5.7 | Not available | 5.85 |
| Mar 2001 | 5.68 | Not available | 5.82 |
| Apr 2001 | 5.63 | Not available | 5.76 |
| May 2001 | 5.65 | Not available | 5.71 |
| Jun 2001 | 5.72 | Not available | 5.82 |
| Jul 2001 | 5.92 | Not available | 6.16 |
| Aug 2001 | 5.58 | Not available | 6 |
| Sept 2001 | 5.39 | Not available | 5.59 |
| Oct 2001 | 5.06 | Not available | 5.53 |
| Nov 2001 | 4.84 | Not available | 5.31 |
| Dec 2001 | 4.98 | Not available | 5.21 |
| Jan 2002 | 5.06 | Not available | 5.34 |
| Feb 2002 | 5.14 | Not available | 5.47 |
| Mar 2002 | 5.22 | Not available | 5.47 |
| Apr 2002 | 5.35 | Not available | 5.62 |
| May 2002 | 5.43 | Not available | 5.67 |
| Jun 2002 | 5.41 | Not available | 5.65 |
| Jul 2002 | 5.3 | Not available | 5.55 |
| Aug 2002 | 4.59 | Not available | 4.92 |
| Sept 2002 | 4.5 | Not available | 4.72 |
| Oct 2002 | 4.43 | Not available | 4.69 |
| Nov 2002 | 4.45 | Not available | 4.68 |
| Dec 2002 | 4.62 | Not available | 4.86 |
| Jan 2003 | 4.5 | Not available | 4.69 |
| Feb 2003 | 4.14 | Not available | 4.36 |
| Mar 2003 | 4.06 | Not available | 4.2 |
| Apr 2003 | 4.06 | Not available | 4.31 |
| May 2003 | 3.91 | Not available | 4.18 |
| Jun 2003 | 3.85 | Not available | 4.04 |
| Jul 2003 | 3.87 | Not available | 4.08 |
| Aug 2003 | 4.32 | Not available | 4.63 |
| Sept 2003 | 4.56 | Not available | 4.86 |
| Oct 2003 | 4.98 | Not available | 5.21 |
| Nov 2003 | 5.1 | Not available | 5.34 |
| Dec 2003 | 5.05 | Not available | 5.32 |
| Jan 2004 | 4.95 | Not available | 5.19 |
| Feb 2004 | 4.89 | Not available | 5.12 |
| Mar 2004 | 4.9 | Not available | 5.17 |
| Apr 2004 | 5.11 | Not available | 5.37 |
| May 2004 | 5.18 | Not available | 5.33 |
| Jun 2004 | 5.52 | Not available | 5.76 |
| Jul 2004 | 5.53 | Not available | 5.69 |
| Aug 2004 | 5.47 | Not available | 5.66 |
| Sept 2004 | 5.33 | Not available | 5.63 |
| Oct 2004 | 5.29 | Not available | 5.6 |
| Nov 2004 | 5.06 | Not available | 5.42 |
| Dec 2004 | 5.07 | Not available | 5.31 |
| Jan 2005 | 4.99 | Not available | 5.3 |
| Feb 2005 | 5.07 | Not available | 5.31 |
| Mar 2005 | 5.2 | Not available | 5.48 |
| Apr 2005 | 5.16 | Not available | 5.43 |
| May 2005 | 4.91 | Not available | 5.27 |
| Jun 2005 | 4.77 | Not available | 5.01 |
| Jul 2005 | 4.59 | Not available | 4.76 |
| Aug 2005 | 4.56 | Not available | 4.75 |
| Sept 2005 | 4.52 | Not available | 4.74 |
| Oct 2005 | 4.54 | Not available | 4.78 |
| Nov 2005 | 4.74 | Not available | 4.98 |
| Dec 2005 | 4.74 | Not available | 5.04 |
| Jan 2006 | 4.62 | Not available | 4.96 |
| Feb 2006 | 4.71 | Not available | 5.01 |
| Mar 2006 | 4.72 | Not available | 5.04 |
| Apr 2006 | 4.77 | Not available | 5.03 |
| May 2006 | 5 | Not available | 5.23 |
| Jun 2006 | 5 | Not available | 5.31 |
| Jul 2006 | 5.01 | Not available | 5.39 |
| Aug 2006 | 5.1 | Not available | 5.42 |
| Sept 2006 | 5.1 | Not available | 5.44 |
| Oct 2006 | 4.99 | Not available | 5.39 |
| Nov 2006 | 5.2 | Not available | 5.51 |
| Dec 2006 | 5.15 | Not available | 5.44 |
| Jan 2007 | 5.32 | Not available | 5.68 |
| Feb 2007 | 5.46 | Not available | 5.82 |
| Mar 2007 | 5.55 | Not available | 5.88 |
| Apr 2007 | 5.62 | Not available | 5.86 |
| May 2007 | 5.7 | Not available | 6.05 |
| Jun 2007 | 5.98 | Not available | 6.26 |
| Jul 2007 | 6.07 | Not available | 6.33 |
| Aug 2007 | 6.11 | Not available | 6.54 |
| Sept 2007 | 6.05 | Not available | 6.32 |
| Oct 2007 | 6.11 | Not available | 6.44 |
| Nov 2007 | 6.09 | Not available | 6.47 |
| Dec 2007 | 6.06 | Not available | 6.54 |
| Jan 2008 | 5.97 | Not available | 6.41 |
| Feb 2008 | 5.74 | Not available | 6.52 |
| Mar 2008 | 5.8 | Not available | 6.59 |
| Apr 2008 | 6.06 | Not available | 6.91 |
| May 2008 | 6.26 | 6.44 | Not available |
| Jun 2008 | 6.6 | 6.67 | Not available |
| Jul 2008 | 6.35 | 6.94 | Not available |
| Aug 2008 | 6.08 | 6.8 | Not available |
| Sept 2008 | 5.96 | 6.56 | Not available |
| Oct 2008 | 5.83 | 6.41 | Not available |
| Nov 2008 | 5.1 | 6.58 | Not available |
| Dec 2008 | 4.77 | 6.69 | Not available |
| Jan 2009 | 4.35 | 6.13 | Not available |
| Feb 2009 | 4.35 | 5.97 | Not available |
| Mar 2009 | 3.98 | Not available | Not available |
| Apr 2009 | 4.02 | Not available | Not available |
| May 2009 | 3.98 | Not available | Not available |
| Jun 2009 | 4.45 | 6.47 | Not available |
| Jul 2009 | 4.42 | 6.47 | Not available |
| Aug 2009 | 4.43 | 6.44 | Not available |
| Sept 2009 | 4.47 | 6.42 | Not available |
| Oct 2009 | 4.32 | 6.55 | Not available |
| Nov 2009 | 4.1 | 6.62 | Not available |
| Dec 2009 | 4.05 | 6.64 | Not available |
| Jan 2010 | 3.97 | 6.61 | Not available |
| Feb 2010 | 3.88 | 6.62 | Not available |
| Mar 2010 | 3.92 | 6.61 | Not available |
| Apr 2010 | 3.82 | 6.65 | Not available |
| May 2010 | 3.78 | 6.63 | Not available |
| Jun 2010 | 3.67 | 6.6 | Not available |
| Jul 2010 | 3.77 | 6.52 | Not available |
| Aug 2010 | 3.74 | 6.35 | Not available |
| Sept 2010 | 3.8 | 6.27 | Not available |
| Oct 2010 | 3.68 | 6.14 | Not available |
| Nov 2010 | 3.53 | 6.16 | Not available |
| Dec 2010 | 3.5 | 6.15 | Not available |
| Jan 2011 | 3.7 | 6.18 | Not available |
| Feb 2011 | 3.7 | 5.92 | Not available |
| Mar 2011 | 3.68 | 5.91 | Not available |
| Apr 2011 | 3.66 | 5.98 | Not available |
| May 2011 | 3.51 | 5.93 | Not available |
| Jun 2011 | 3.36 | 5.77 | Not available |
| Jul 2011 | 3.14 | 5.75 | Not available |
| Aug 2011 | 3 | 5.5 | Not available |
| Sept 2011 | 2.92 | 5.27 | Not available |
| Oct 2011 | 3.04 | 5.31 | Not available |
| Nov 2011 | 3.14 | 5.37 | Not available |
| Dec 2011 | 3.22 | 5.45 | Not available |
| Jan 2012 | 3.27 | 5.53 | Not available |
| Feb 2012 | 3.37 | 5.6 | Not available |
| Mar 2012 | 3.44 | 5.76 | Not available |
| Apr 2012 | 3.66 | 5.79 | Not available |
| May 2012 | 3.68 | 6.07 | Not available |
| Jun 2012 | 3.74 | 5.7 | Not available |
| Jul 2012 | 3.67 | 5.83 | Not available |
| Aug 2012 | 3.69 | 5.93 | Not available |
| Sept 2012 | 3.67 | 5.85 | Not available |
| Oct 2012 | 3.49 | 5.64 | Not available |
| Nov 2012 | 3.43 | 5.64 | Not available |
| Dec 2012 | 3.35 | 5.39 | Not available |
| Jan 2013 | 3.11 | 4.86 | Not available |
| Feb 2013 | 2.92 | 4.73 | Not available |
| Mar 2013 | 2.9 | 4.67 | Not available |
| Apr 2013 | 2.87 | 4.67 | Not available |
| May 2013 | 2.69 | 4.61 | Not available |
| Jun 2013 | 2.63 | 4.59 | Not available |
| Jul 2013 | 2.62 | 4.58 | Not available |
| Aug 2013 | 2.58 | 4.52 | Not available |
| Sept 2013 | 2.54 | 4.56 | Not available |
| Oct 2013 | 2.48 | 4.42 | 5.1 |
| Nov 2013 | 2.44 | 4.41 | 5.04 |
| Dec 2013 | 2.4 | 4.36 | 5.08 |
| Jan 2014 | 2.37 | 4.34 | 5.05 |
| Feb 2014 | 2.38 | 4.39 | 5.05 |
| Mar 2014 | 2.37 | 4.38 | 5.06 |
| Apr 2014 | 2.54 | 4.48 | 5.14 |
| May 2014 | 2.56 | 4.49 | 5.2 |
| Jun 2014 | 2.6 | 4.5 | 5.32 |
| Jul 2014 | 2.54 | 4.47 | 5.33 |
| Aug 2014 | 2.54 | 4.34 | 5.28 |
| Sept 2014 | 2.46 | 4.23 | 5.28 |
| Oct 2014 | 2.21 | 3.98 | 5.2 |
| Nov 2014 | 2.17 | 3.84 | 5.27 |
| Dec 2014 | 2.08 | 3.89 | 5.27 |
| Jan 2015 | 2.01 | 3.71 | 4.74 |
| Feb 2015 | 1.96 | 3.77 | 4.67 |
| Mar 2015 | 1.99 | 3.74 | 4.72 |
| Apr 2015 | 1.95 | 3.53 | 4.58 |
| May 2015 | 1.9 | 3.53 | 4.57 |
| Jun 2015 | 1.83 | 3.34 | 4.39 |
| Jul 2015 | 1.87 | 3.26 | 4.32 |
| Aug 2015 | 1.95 | 3.15 | 4.36 |
| Sept 2015 | 1.91 | 3.03 | 4.22 |
| Oct 2015 | 1.87 | 2.89 | 4.22 |
| Nov 2015 | 1.92 | 2.88 | 4.13 |
| Dec 2015 | 1.9 | 2.87 | 4.06 |
| Jan 2016 | 1.93 | 2.85 | 3.95 |
| Feb 2016 | 1.95 | 2.88 | 3.99 |
| Mar 2016 | 1.9 | 2.87 | 3.92 |
| Apr 2016 | 1.84 | 2.71 | 3.92 |
| May 2016 | 1.91 | 2.75 | 3.93 |
| Jun 2016 | 1.75 | 2.64 | 3.88 |
| Jul 2016 | 1.72 | 2.57 | 3.85 |
| Aug 2016 | 1.69 | 2.55 | 3.88 |
| Sept 2016 | 1.59 | 2.42 | 3.84 |
| Oct 2016 | 1.52 | 2.42 | 3.73 |
| Nov 2016 | 1.43 | 2.49 | 3.66 |
| Dec 2016 | 1.45 | 2.53 | 3.62 |
| Jan 2017 | 1.45 | 2.5 | 3.62 |
| Feb 2017 | 1.42 | 2.45 | 3.8 |
| Mar 2017 | 1.37 | 2.48 | 3.99 |
| Apr 2017 | 1.35 | 2.43 | 4.04 |
| May 2017 | 1.49 | 2.5 | 4.19 |
| Jun 2017 | 1.48 | 2.5 | 4.2 |
| Jul 2017 | 1.41 | 2.37 | 4.07 |
| Aug 2017 | 1.43 | 2.33 | 4.02 |
| Sept 2017 | 1.4 | 2.31 | 4.01 |
| Oct 2017 | 1.55 | 2.36 | 4.02 |
| Nov 2017 | 1.61 | 2.36 | 3.97 |
| Dec 2017 | 1.57 | 2.21 | 3.89 |
| Jan 2018 | 1.54 | 2.17 | 3.82 |
| Feb 2018 | 1.49 | 2.21 | 3.82 |
| Mar 2018 | 1.53 | 2.2 | 3.77 |
| Apr 2018 | 1.72 | 2.36 | 3.9 |
| May 2018 | 1.74 | 2.34 | 3.95 |
| Jun 2018 | 1.74 | 2.37 | 3.95 |
| Jul 2018 | 1.75 | 2.3 | 3.78 |
| Aug 2018 | 1.75 | 2.28 | 3.61 |
| Sept 2018 | 1.71 | 2.12 | 3.38 |
| Oct 2018 | 1.8 | 2.27 | 3.33 |
| Nov 2018 | 1.75 | 2.28 | 3.23 |
| Dec 2018 | 1.73 | 2.24 | 3.18 |
| Jan 2019 | 1.72 | 2.23 | 3.04 |
| Feb 2019 | 1.7 | 2.17 | 2.99 |
| Mar 2019 | 1.7 | 2.17 | 2.97 |
| Apr 2019 | 1.66 | 2.15 | 2.92 |
| May 2019 | 1.65 | 2.19 | 2.93 |
| Jun 2019 | 1.64 | 2.18 | 2.95 |
| Jul 2019 | 1.61 | 2.15 | 2.96 |
| Aug 2019 | 1.59 | 2.1 | 2.96 |
| Sept 2019 | 1.55 | 2.09 | 2.99 |
| Oct 2019 | 1.47 | 2.07 | 2.99 |
| Nov 2019 | 1.41 | 2.08 | 2.99 |
| Dec 2019 | 1.42 | 2.07 | 3 |
| Jan 2020 | 1.41 | 2.05 | 3.02 |
| Feb 2020 | 1.4 | 1.97 | 3.02 |
| Mar 2020 | 1.4 | 1.94 | 3.02 |
| Apr 2020 | 1.38 | 1.89 | 3.07 |
| May 2020 | 1.42 | 1.96 | 3.17 |
| Jun 2020 | 1.41 | 2.19 | 2.72 |
| Jul 2020 | 1.45 | 2.5 | 2.58 |
| Aug 2020 | 1.6 | 2.78 | 3.78 |
| Sept 2020 | 1.75 | 3.29 | 3.95 |
| Oct 2020 | 1.94 | 3.52 | 4.13 |
| Nov 2020 | 1.92 | 3.72 | 4.2 |
| Dec 2020 | 1.86 | 3.75 | 4.2 |
| Jan 2021 | 1.75 | 3.63 | 4.16 |
| Feb 2021 | 1.61 | 3.49 | 4.1 |
| Mar 2021 | 1.56 | 3.38 | 4.16 |
| Apr 2021 | 1.49 | 3.38 | 4.01 |
| May 2021 | 1.47 | 3.31 | 3.88 |
| Jun 2021 | 1.39 | 3.09 | 3.74 |
| Jul 2021 | 1.29 | 2.79 | 3.53 |
| Aug 2021 | 1.23 | 2.48 | 3.43 |
| Sept 2021 | 1.2 | 2.16 | 3.22 |
| Oct 2021 | 1.29 | 2.04 | 2.98 |
| Nov 2021 | 1.53 | 2.02 | 2.91 |
| Dec 2021 | 1.57 | 1.95 | 2.77 |
| Jan 2022 | 1.64 | 1.95 | 2.73 |
| Feb 2022 | 1.78 | 2.03 | 2.72 |
| Mar 2022 | 2.14 | 2.38 | 2.8 |
| Apr 2022 | 2.35 | 2.58 | 2.95 |
| May 2022 | 2.63 | 2.85 | 3.2 |
| Jun 2022 | 2.87 | 3.15 | 3.48 |
| Jul 2022 | 3.48 | 3.69 | 3.96 |
| Aug 2022 | 3.6 | 3.93 | 4.14 |
| Sept 2022 | 4.17 | 4.48 | 4.67 |
| Oct 2022 | 5.99 | 6.2 | 6.42 |
| Nov 2022 | 5.98 | 6.28 | 6.59 |
| Dec 2022 | 5.43 | 6 | 6.3 |
| Jan 2023 | 5.14 | 5.66 | 6.02 |
| Feb 2023 | 4.79 | 5.35 | 5.86 |
| Mar 2023 | 4.74 | 5.23 | 5.77 |
| Apr 2023 | 4.6 | 5.07 | 5.65 |
| May 2023 | 4.72 | 5.08 | 5.67 |
| Jun 2023 | 5.49 | 5.75 | 6.28 |
| Jul 2023 | 6.22 | 6.49 | 6.88 |
| Aug 2023 | 6.18 | 6.57 | 6.93 |
| Sept 2023 | 5.91 | 6.37 | 6.75 |
| Oct 2023 | 5.6 | 6.06 | 6.6 |
| Nov 2023 | 5.28 | 5.81 | 6.38 |
| Dec 2023 | 5.03 | 5.69 | 6.18 |
| Jan 2024 | 4.71 | 5.44 | 5.87 |
| Feb 2024 | 4.76 | 5.26 | 5.73 |
| Mar 2024 | 4.96 | 5.39 | 5.83 |
| Apr 2024 | 4.98 | 5.47 | 5.87 |
| May 2024 | 5.19 | 5.66 | 6.04 |
| Jun 2024 | 5.16 | 5.65 | 6.07 |
| Jul 2024 | 4.99 | 5.61 | 5.97 |
| Aug 2024 | 4.8 | 5.54 | 5.9 |
| Sept 2024 | 4.58 | 5.4 | 5.76 |
| Oct 2024 | 4.4 | 5.3 | 5.61 |
| Nov 2024 | 4.53 | 5.41 | 5.69 |
| Dec 2024 | 4.6 | 5.37 | 5.7 |
| Jan 2025 | 4.63 | 5.35 | 5.69 |
| Feb 2025 | 4.65 | 5.26 | 5.64 |
| Mar 2025 | 4.54 | 5.09 | 5.44 |
| Apr 2025 | 4.42 | 4.96 | 5.29 |
| May 2025 | 4.18 | 4.82 | 5.1 |
| Jun 2025 | 4.28 | 4.8 | 5.1 |
| Jul 2025 | 4.21 | 4.62 | 5.05 |
| Aug 2025 | 4.1 | 4.55 | 5 |
| Sept 2025 | 4.19 | 4.58 | 5.03 |
| Oct 2025 | 4.2 | 4.57 | 5 |
| Nov 2025 | 4.06 | 4.49 | 4.91 |
| Dec 2025 | 3.97 | 4.42 | 4.83 |
| Jan 2026 | 3.93 | 4.36 | 4.8 |
| Feb 2026 | 3.97 | 4.34 | 4.82 |
| Mar 2026 | 4.45 | 4.79 | 5.23 |
| Apr 2026 | 5.14 | 5.46 | 5.8 |
| May 2026 | 4.91 | 5.31 | 5.63 |
| Jun 2026 | 4.8 | 5.18 | 5.54 |
| Jul 2026 | 4.79 | 5.07 | 5.48 |
| Aug 2026 | 4.92 | 5.16 | 5.52 |
| Sept 2026 | 5.13 | 5.37 | 5.7 |
Scroll the table sideways to see every column.
02 · Availability
Credit can help someone compete for a home. It cannot by itself create one. Supply, location and tenure determine the choices available.
Net additions include conversions and changes of use, less demolitions. Latest year provisional. This is not the number currently for sale.
Live Table 118, England total, 2000–01 onwards. Includes Census adjustments; the component collection begins in 2006–07. Earlier figures are less reliable. Financial years are plotted at their starting year.
MHCLG · Live Table 118 (ODS)| Year | Net homes | Status |
|---|---|---|
| 2000–01 | 132,000 | Published estimate |
| 2001–02 | 146,704 | Published estimate |
| 2002–03 | 159,875 | Published estimate |
| 2003–04 | 170,969 | Published estimate |
| 2004–05 | 185,553 | Published estimate |
| 2005–06 | 202,653 | Published estimate |
| 2006–07 | 214,936 | Published estimate |
| 2007–08 | 223,534 | Published estimate |
| 2008–09 | 182,767 | Published estimate |
| 2009–10 | 144,870 | Published estimate |
| 2010–11 | 137,394 | Published estimate |
| 2011–12 | 140,785 | Published estimate |
| 2012–13 | 130,611 | Published estimate |
| 2013–14 | 142,494 | Published estimate |
| 2014–15 | 176,582 | Published estimate |
| 2015–16 | 195,534 | Published estimate |
| 2016–17 | 223,234 | Published estimate |
| 2017–18 | 228,170 | Published estimate |
| 2018–19 | 247,766 | Published estimate |
| 2019–20 | 248,591 | Published estimate |
| 2020–21 | 217,754 | Published estimate |
| 2021–22 | 234,462 | Published estimate |
| 2022–23 | 234,292 | Published estimate |
| 2023–24 | 221,409 | Published estimate |
| 2024–25 | 208,600 | Provisional |
177,530 children were in council-arranged temporary accommodation in March 2026. The household trend below counts their families, not additional people.
Households placed in temporary accommodation by councils under homelessness duties, at the end of each quarter. It does not count people sleeping rough, sofa-surfing, or not known to a council. The Homelessness Reduction Act 2017 (in force April 2018) changed the duties under which people are placed.
Source dataset →| Period | households | Status |
|---|---|---|
| Mar 1998 | 47,520 | Outturn |
| Jun 1998 | 49,390 | Outturn |
| Sep 1998 | 52,510 | Outturn |
| Dec 1998 | 53,790 | Outturn |
| Mar 1999 | 56,580 | Outturn |
| Jun 1999 | 58,430 | Outturn |
| Sep 1999 | 61,450 | Outturn |
| Dec 1999 | 62,180 | Outturn |
| Mar 2000 | 65,170 | Outturn |
| Jun 2000 | 67,520 | Outturn |
| Sep 2000 | 71,860 | Outturn |
| Dec 2000 | 73,080 | Outturn |
| Mar 2001 | 75,200 | Outturn |
| Jun 2001 | 75,920 | Outturn |
| Sep 2001 | 77,800 | Outturn |
| Dec 2001 | 77,510 | Outturn |
| Mar 2002 | 80,200 | Outturn |
| Jun 2002 | 81,660 | Outturn |
| Sep 2002 | 85,010 | Outturn |
| Dec 2002 | 85,140 | Outturn |
| Mar 2003 | 89,040 | Outturn |
| Jun 2003 | 91,870 | Outturn |
| Sep 2003 | 94,440 | Outturn |
| Dec 2003 | 94,610 | Outturn |
| Mar 2004 | 97,680 | Outturn |
| Jun 2004 | 99,530 | Outturn |
| Sep 2004 | 101,300 | Outturn |
| Dec 2004 | 101,030 | Outturn |
| Mar 2005 | 101,070 | Outturn |
| Jun 2005 | 100,970 | Outturn |
| Sep 2005 | 101,020 | Outturn |
| Dec 2005 | 98,730 | Outturn |
| Mar 2006 | 96,370 | Outturn |
| Jun 2006 | 93,910 | Outturn |
| Sep 2006 | 93,090 | Outturn |
| Dec 2006 | 89,510 | Outturn |
| Mar 2007 | 87,120 | Outturn |
| Jun 2007 | 84,900 | Outturn |
| Sep 2007 | 82,750 | Outturn |
| Dec 2007 | 79,500 | Outturn |
| Mar 2008 | 77,510 | Outturn |
| Jun 2008 | 74,690 | Outturn |
| Sep 2008 | 72,130 | Outturn |
| Dec 2008 | 67,480 | Outturn |
| Mar 2009 | 64,000 | Outturn |
| Jun 2009 | 60,230 | Outturn |
| Sep 2009 | 56,920 | Outturn |
| Dec 2009 | 53,370 | Outturn |
| Mar 2010 | 51,310 | Outturn |
| Jun 2010 | 50,400 | Outturn |
| Sep 2010 | 49,680 | Outturn |
| Dec 2010 | 48,010 | Outturn |
| Mar 2011 | 48,240 | Outturn |
| Jun 2011 | 48,330 | Outturn |
| Sep 2011 | 49,100 | Outturn |
| Dec 2011 | 48,920 | Outturn |
| Mar 2012 | 50,430 | Outturn |
| Jun 2012 | 51,630 | Outturn |
| Sep 2012 | 52,960 | Outturn |
| Dec 2012 | 53,140 | Outturn |
| Mar 2013 | 55,320 | Outturn |
| Jun 2013 | 55,840 | Outturn |
| Sep 2013 | 57,410 | Outturn |
| Dec 2013 | 56,940 | Outturn |
| Mar 2014 | 58,410 | Outturn |
| Jun 2014 | 59,570 | Outturn |
| Sep 2014 | 60,900 | Outturn |
| Dec 2014 | 61,930 | Outturn |
| Mar 2015 | 64,710 | Outturn |
| Jun 2015 | 66,980 | Outturn |
| Sep 2015 | 68,560 | Outturn |
| Dec 2015 | 69,140 | Outturn |
| Mar 2016 | 71,670 | Outturn |
| Jun 2016 | 73,050 | Outturn |
| Sep 2016 | 74,750 | Outturn |
| Dec 2016 | 75,740 | Outturn |
| Mar 2017 | 77,220 | Outturn |
| Jun 2017 | 78,540 | Outturn |
| Sep 2017 | 79,830 | Outturn |
| Dec 2017 | 79,720 | Outturn |
| Mar 2018 | 80,720 | Outturn |
| Jun 2018 | 82,390 | Outturn |
| Sep 2018 | 83,430 | Outturn |
| Dec 2018 | 83,540 | Outturn |
| Mar 2019 | 85,040 | Outturn |
| Jun 2019 | 86,240 | Outturn |
| Sep 2019 | 87,390 | Outturn |
| Dec 2019 | 88,310 | Outturn |
| Mar 2020 | 92,190 | Outturn |
| Jun 2020 | 98,260 | Outturn |
| Sep 2020 | 94,610 | Outturn |
| Dec 2020 | 95,100 | Outturn |
| Mar 2021 | 95,290 | Outturn |
| Jun 2021 | 95,850 | Outturn |
| Sep 2021 | 95,560 | Outturn |
| Dec 2021 | 96,280 | Outturn |
| Mar 2022 | 95,000 | Outturn |
| Jun 2022 | 95,690 | Outturn |
| Sep 2022 | 98,840 | Outturn |
| Dec 2022 | 100,510 | Outturn |
| Mar 2023 | 104,540 | Outturn |
| Jun 2023 | 105,840 | Outturn |
| Sep 2023 | 108,920 | Outturn |
| Dec 2023 | 112,610 | Outturn |
| Mar 2024 | 117,350 | Outturn |
| Jun 2024 | 123,030 | Outturn |
| Sep 2024 | 125,970 | Outturn |
| Dec 2024 | 127,820 | Outturn |
| Mar 2025 | 130,890 | Outturn |
| Jun 2025 | 132,340 | Outturn |
| Sep 2025 | 134,700 | Outturn |
| Dec 2025 | 134,140 | Outturn |
| Mar 2026 | 135,580 | Outturn |
03 · Private renting
Rent is an ongoing household cost. The size of the rented sector shows how many people rely on it; it does not tell us whether a suitable home is available locally.
Mean private rent (all tenancies, new and existing) as a share of the median GROSS monthly income of private-renting households (Family Resources Survey). Not take-home pay, and not an individual worker. ONS treats 30% or less as affordable. Regional estimates rest on survey samples and can move a lot year to year. ONS warns these estimates are not directly comparable with earlier editions of the release (method changed in 2024).
Source dataset →| Period | % | Status |
|---|---|---|
| 2015-16 | 39.4 | Outturn |
| 2016-17 | 39.2 | Outturn |
| 2017-18 | 39 | Outturn |
| 2018-19 | 37 | Outturn |
| 2019-20 | 35.4 | Outturn |
| 2020-21 | 38 | Outturn |
| 2021-22 | 35.7 | Outturn |
| 2022-23 | 33.1 | Outturn |
| 2023-24 | 36.3 | Outturn |
English Housing Survey and its predecessors. Before 2008 figures come from the Labour Force Survey and earlier household surveys; years with no survey are left blank, not filled. Source changes: 1980–1991 DoE estimates; 1992–2008 Labour Force Survey; 2008-09 onward English Housing Survey.
Source dataset →| Period | % | Status |
|---|---|---|
| 1996 | 10.1 | Outturn |
| 1997 | 10.5 | Outturn |
| 1998 | 10.3 | Outturn |
| 1999 | 9.9 | Outturn |
| 2000 | 10 | Outturn |
| 2001 | 10.1 | Outturn |
| 2002 | 10.3 | Outturn |
| 2003 | 10.8 | Outturn |
| 2004 | 11 | Outturn |
| 2005 | 11.7 | Outturn |
| 2006 | 12.2 | Outturn |
| 2007 | 12.7 | Outturn |
| 2008 | 13.9 | Outturn |
| 2008-09 | 14.2 | Outturn |
| 2009-10 | 15.6 | Outturn |
| 2010-11 | 16.5 | Outturn |
| 2011-12 | 17.4 | Outturn |
| 2012-13 | 18 | Outturn |
| 2013-14 | 19.4 | Outturn |
| 2014-15 | 19 | Outturn |
| 2015-16 | 19.9 | Outturn |
| 2016-17 | 20.3 | Outturn |
| 2017-18 | 19.5 | Outturn |
| 2018-19 | 19.3 | Outturn |
| 2019-20 | 18.7 | Outturn |
| 2020-21 | 18.5 | Outturn |
| 2021-22 | 19.1 | Outturn |
| 2022-23 | 18.8 | Outturn |
| 2023-24 | 18.8 | Outturn |
| 2024-25 | 18.9 | Outturn |
The 2024 dwelling survey estimated 11% of private rented homes were vacant. Empty does not necessarily mean available or suitable to let.
Vacancy definition and source →The same regions, two measures: purchase price ÷ individual annual pay; rent ÷ gross household income. The rent chart is not a comparison with monthly mortgage payments.
Buying affordability
English regions · 2025 versus 2007
Source: ONS, Housing affordability in England and Wales: 2025, dataset Table 1c (released 26 March 2026). Chart HOUSE-04.
| Region | 2025 | 2007 |
|---|---|---|
| London | 10.61 | 7.94 |
| South East | 9.58 | 8.40 |
| East of England | 9.02 | 7.77 |
| South West | 8.33 | 8.29 |
| East Midlands | 7.02 | 6.43 |
| West Midlands | 6.80 | 6.48 |
| Yorkshire and The Humber | 6.03 | 6.04 |
| North West | 5.92 | 5.83 |
| North East | 5.00 | 5.79 |
Rental affordability
English regions · 2023–24 versus 2015–16
Source: ONS, Private rental affordability, England, Wales and Northern Ireland: 2024, dataset Table 3. Chart HOUSE-02.
| Area | 2023–24 | 2015–16 |
|---|---|---|
| London | 41.6% | 52.0% |
| England | 36.3% | 39.4% |
| South West | 31.4% | 32.1% |
| South East | 29.6% | 33.2% |
| West Midlands | 29.2% | 27.2% |
| East of England | 28.9% | 33.1% |
| North West | 28.1% | 30.2% |
| Yorkshire and The Humber | 27.4% | 26.3% |
| Wales | 25.9% | 31.5% |
| East Midlands | 24.4% | 25.0% |
| North East | 19.8% | 28.0% |
Delivery and safety · England; Housing Benefit changes also concern Scotland and Wales
Supported housing is more than a bed. Residents may need help to live independently; weak oversight can leave them paying for support they do not receive.
The June 2026 government response sets out licensing and support standards. These are implementation proposals, not evidence that poor provision has already been eliminated. Councils need inspection capacity and safe alternatives when provision closes.
Process illustration; no effect sizes implied. MHCLG and DWP: Supported Housing regulation: government response · 2026-06-19 · Introduction; licensing; exemptions; next steps.
05 · Age and condition
New supply is only part of the task. Older buildings, damp and unsafe homes need sustained repairs and investment.
England · homes built before 1919 · 2016–17 → 2024
32 in every 100 homes in 2024.
3 percentage points lower than 2016–17.
20 in every 100 homes in 2024.
1 percentage point lower than 2016–17.
6 in every 100 homes in 2024.
1 percentage point lower than 2016–17.
Age alone does not mean poor condition. These snapshots show the changing mix of homes in each tenure, not the same homes followed over time.
Rounded survey shares; differences are descriptive, not tests of statistical significance. The earlier ONS release labels the period financial year ending 2017; its England analysis reports 35% private, 21% owner occupied and 7% social rented. The latest EHS dwelling survey is 2024 (32%, 20%, 6%). No annual path between snapshots is inferred. Each square is one percentage point of the 2024 stock.
ONS · UK private rented sector, England, Figure 38 and accompanying textEnglish Housing Survey · Figure 1.8, Annex Table 1.6One period, one scale: 2006–2024. Conditions improved overall, but damp has risen again in recent years.
34.9% → 15.4%
2006 → 2024 · -19.5 percentage points
4 million homes in 2024
9.8% → 5.5%
2006 → 2024 · -4.3 percentage points
1.4 million homes in 2024
Teal solid: non-decent · rust dashed: damp. Hollow dots: modelled 2020–21 estimates. Categories overlap; do not add the totals.
The current non-decent definition starts in 2006, so both chart comparisons start there. The full damp record below begins in 1996, with gaps before 2003. We retain it without using a different headline baseline. Energy-efficiency assessment methods also changed over the record. Survey estimates of dwellings. Categories overlap and must not be added. The charts use published percentages; headline dwelling counts are rounded. Pandemic estimates for 2020–21 were modelled, with a different survey basis.
English Housing Survey · Annex 1.4 and 1.9| Year | Non-decent (%) | Damp (%) | Basis |
|---|---|---|---|
| 1996 | Not comparable | 12.8 | Survey |
| 2001 | Not comparable | 9.6 | Survey |
| 2003 | Not comparable | 10.6 | Survey |
| 2004 | Not comparable | 10.4 | Survey |
| 2005 | Not comparable | 10.1 | Survey |
| 2006 | 34.9 | 9.8 | Survey |
| 2007 | 34.7 | 8.6 | Survey |
| 2008 | 33.1 | 7.8 | Survey |
| 2009 | 30.1 | 8.1 | Survey |
| 2010 | 26.5 | 6.5 | Survey |
| 2011 | 23.6 | 4.6 | Survey |
| 2012 | 21.8 | 4.3 | Survey |
| 2013 | 20.6 | 4.3 | Survey |
| 2014 | 19.8 | 4.3 | Survey |
| 2015 | 19.4 | 4.4 | Survey |
| 2016 | 19.9 | 4.2 | Survey |
| 2017 | 18.8 | 3.7 | Survey |
| 2018 | 17.8 | 3.3 | Survey |
| 2019 | 17 | 3.4 | Survey |
| 2020 | 15 | 4 | Modelled |
| 2021 | 14.3 | 3.8 | Modelled |
| 2022 | 14.7 | 4.1 | Survey |
| 2023 | 15 | 5.2 | Survey |
| 2024 | 15.4 | 5.5 | Survey |
Building safety also matters: unsafe-cladding remediation and other housing weaknesses →
06 · What would move the needle?
Build supply, keep rents affordable and widen access to credit responsibly. Each option shows its evidence and what still needs to be assessed.
All six priorities are in the UK National Action PlanTwo have existing assessments. The other four retain their delivery, proposal or announcement status.Existing assessed action
Connect sites to infrastructure, secure builders and finance, and measure completed homes rather than permissions.
Match homes to local need; test infrastructure costs, build-out rates and environmental constraints.
Track: Net additional homes and time from permission to completion.
Primary sourceExisting assessmentGovernment announcement · details pending
Your First Home proposes a 20% government equity loan and an expected 2.5% deposit for eligible new-build purchases in England.
Budget details must settle cost, eligibility and timing. Assess additional homes, price effects, resale terms and taxpayer risk; an equity loan is debt, not a grant.
The NAO found that the earlier Help to Buy scheme supported ownership and supply, but also helped some who could already buy and exposed buyers and taxpayers to market risk. That is evidence to test the new scheme against, not a forecast of its effects. NAO evaluation.
Track: Additional first-time buyers and homes, total borrower cost and public exposure.
Primary sourcePolicy option · not yet appraised
Assess rent-payment history and sustainable income more effectively so creditworthy applicants can qualify.
Keep verified affordability, rate-stress checks, responsible-lending rules and system-wide limits on high loan-to-income lending. Test arrears and negative-equity risks. Later-life lending also needs suitable advice, balanced promotions and clear explanations of rolled-up interest and alternatives.
Track: Access alongside arrears, repossessions, advice complaints and the distribution of high-risk loans.
Primary sourceFCA: later-life lending safeguardsExisting assessed action
Combine suitable social housing with early tenancy support and homelessness prevention.
Check suitability, local services and whether buying or leasing homes adds capacity rather than displacing other households.
Track: Households and children in temporary accommodation; sustained settled tenancies.
Primary sourceExisting assessmentDelivery priority · additional appraisal needed
Join maintenance and energy improvements to enforcement of housing and building-safety standards.
Prioritise serious hazards and remediation; assess costs and avoid repairs budgets being crowded out by new construction.
Track: Damp, non-decent homes and completion of unsafe-cladding remediation.
Primary sourceReviewed 8 October 2026. The first-time buyer scheme is an announcement, not an open application service. The established national shortlists and their named reviews remain separately identified.
What would it take to improve this?
The outcome we want: More suitable, occupied homes in England that people can afford relative to their income.
The main constraint: Permissions and grant only become homes when sites have infrastructure, builders and finance — and the social-rent programme’s first allocations (25 August 2026) went to providers for supply in general, not to named schemes for households in temporary accommodation.
Constraint type: infrastructure, workforce, money, permissions.
What is funded now, and the changes assessed against it — the current baseline and the alternatives, before the position today and the actions.
Provisional single-reviewer assessments from the 6 October 2026 review; not approved business cases, and not government policy.
Homes built, not just permittedDelivery RAG: Red
Range if completed: 14.0–20.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))
Settled homes for families in temporary accommodationDelivery RAG: Amber
Range if completed: 19.0–22.0 out of 30 (equal weights; not yet assessed: incremental affordability (Co))
Prevent avoidable loss of rented homesDelivery RAG: Amber
Range if completed: 16.0–22.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))
Protect flood-defence maintenance and appraise schemes by riskDelivery RAG: Amber
Range if completed: 15.0–21.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))
Alternatives already on record: 34 options listed under the points in the position today (24 without an action record), and 2 earlier options under other options compared. They have not been scored in the review.
Which quadrant a point sits in is our analytical judgement, not a statistical category. Each point says whether it is a measured fact, our synthesis or a risk.
A ten-year, £39bn Social and Affordable Homes Programme aims for around 300,000 homes with at least 60% for social rent; the first £9.58bn went to 33 strategic partners outside London on 25 August 2026, with more than £16bn outside London and around £5bn in London still to allocate.
Measured factConfidence: High· 2026–27 to 2035–36· England
Source: MHCLG / Homes England / GLA, Social and Affordable Homes Programme 2026 to 2036 (collection; MHCLG policy statement; Homes England prospectus) (Collection introduction; policy statement “Introduction”); Ministry of Housing, Communities and Local Government, The Social and Affordable Homes Programme and the reinvigoration of council housebuilding (Sections “Investment to strategic partners” and “Investment through continuous market engagement”)
Options assessed against this point: Settled homes for families in temporary accommodation (Amber delivery RAG)
Funding: A £39bn Social and Affordable Homes Programme for 2026–2036 aims to deliver around 300,000 social and affordable homes, with a target that at least 60% are for Social Rent. On 25 August 2026 the Burnham government made the first allocations — £9.58bn to 33 Strategic Partners for 73,600 homes — and said the remaining funding outside London (more than £16bn) will prioritise Social Rent and council housebuilding.
Checked 4 October 2026. A commitment is not delivery.
Converts the £39bn envelope into named starts and completions at Social Rent, the tenure the programme is judged on.
Who: MHCLG and HM Treasury (priorities); Homes England and the GLA (allocation) · Evidence: Modelled scenario · Status: Funded programme
Source: Prime Minister’s Office and MHCLG, Historic council housebuilding comeback to help families into secure homes (Body and Notes to editors: £9.58bn to 33 Strategic Partners, 73,600 homes; "More than £16 billion remains to be allocated outside London"; "builds on the government's commitment to deliver 1.5 million homes this Parliament"; £46m Capacity to Build)
Publish how bids are prioritised, including value for money
Makes the trade-off between grant per home and number of homes visible, so the programme total can be checked against delivery.
Who: MHCLG; Homes England · Evidence: Expert or audit recommendation · Status: External proposal
Source: MHCLG (response to Housing, Communities and Local Government Committee), Housing conditions in temporary accommodation: government response to the HCLG Committee report (Recommendations 14 (TA subsidy), 17 (restore LHA to 30th percentile), 19 (SAHP prioritisation) and government responses paras 73-74, 81-82, 86-88)
Fund council capacity to bid and build
Lets councils bring forward schemes so council-led Social Rent homes form a larger share of the programme.
Who: MHCLG; Homes England; Local Government Association · Evidence: Untested proposal · Status: Funded programme
Source: Prime Minister’s Office and MHCLG, Historic council housebuilding comeback to help families into secure homes (Body and Notes to editors: £9.58bn to 33 Strategic Partners, 73,600 homes; "More than £16 billion remains to be allocated outside London"; "builds on the government's commitment to deliver 1.5 million homes this Parliament"; £46m Capacity to Build)
Devolve programme direction to established mayoral authorities
Mayors set strategic priorities for their area's share of grant, aiming to match homes to local need.
Who: MHCLG; Established Mayoral Strategic Authorities · Evidence: Untested proposal · Status: Announced proposal · Works through Hampshire: Mayors set strategic priorities for their area's share of grant, aiming to match homes to local need.
Source: Cabinet Office, Rewiring the State – Cabinet Statement (31 July 2026) (Text: share of local income tax for every mayor from 2028; white paper "this autumn"; "in spring 2028, a further wave of new mayors"; outcomes framework for "addressing inequalities"; "place-based data from the Office for National Statistics"; devolution of SAHP and warmer-homes investment)
The planning reforms are in force: the National Planning Policy Framework was revised in December 2024 and replaced by a new version on 17 August 2026, and the Planning and Infrastructure Act 2025 became law on 18 December 2025. Their effect on the number of homes built has not yet been observed.
Measured factConfidence: High· December 2024 to August 2026· England
Source: legislation.gov.uk, Planning and Infrastructure Act 2025 (c. 34) (Introductory text); MHCLG, National Planning Policy Framework (Introduction (this version replaces the Framework revised in December 2024))
Options assessed against this point: Homes built, not just permitted (Red delivery RAG)
Policy: The planning reforms are being taken further. A new National Planning Policy Framework was published on 17 August 2026 (updated 29 September 2026), replacing the December 2024 version; it keeps the standard method for housing need and adds a default "yes" for homes near well-connected stations. Mayors are to get call-in powers over large schemes (proposals announced 23 August 2026). The Planning and Infrastructure Act 2025 remains in law.
Checked 4 October 2026. A commitment is not delivery.
ShortlistedPublish the blocker, owner and infrastructure cost for priority sites
Shows which step stops permitted sites becoming homes, so the planning reforms translate into starts.
Who: MHCLG with local planning authorities · Evidence: Untested proposal · Status: Site-editorial action
Source: Office for Budget Responsibility, Economic and fiscal outlook, March 2025 (Paragraphs 1.10 and 3.37)
Use mayoral call-in and up-front permission for large schemes
Moves strategic decisions on 150+ home schemes to mayors and allows permission before an application, aiming to shorten time to start.
Who: MHCLG; mayors · Evidence: Untested proposal · Status: Announced proposal
Source: Prime Minister's Office / MHCLG, Mayors given powers to green light developments (Body: call-in thresholds (150+ homes, 15,000 sq m, 30m+); proposals "to be published next week"; mayoral say over Homes England funding)
Test whether the reforms are adding homes, against the OBR's judgement
Compares net additions and permissions with the OBR's 170,000 assumption so policy can be adjusted if the effect does not appear.
Who: OBR (Autumn EFO); MHCLG statistics · Evidence: Observational analysis · Status: Established
Source: Office for Budget Responsibility, Economic and fiscal outlook – March 2026 (Paragraph 2.38: net additions fall to 220,000 in 2026-27, rise to just over 305,000 by 2030-31; reforms' impact "has yet to meaningfully materialise in outturn"; cumulative UK net additions 2025-26 to 2029-30 of 1.3 million)
Move towards a rules-based zoning system
Replaces case-by-case permission with zoned rights, which proponents argue raises supply where demand is highest.
Who: MHCLG; Parliament · Evidence: Untested proposal · Status: External proposal
Source: Centre for Cities, A zoning system for England (Whole report (proposal))
Supported housing is more than a bed. Residents may need help to live independently; weak oversight can leave them paying for support they do not receive. The June 2026 government response sets out licensing and support standards. These are implementation proposals, not evidence that poor provision has already been eliminated. Councils need inspection capacity and safe alternatives when provision closes.
Risk, not a certaintyConfidence: Moderate· 2026-06-19· England; Housing Benefit changes also concern Scotland and Wales
Source: MHCLG and DWP, Supported Housing regulation: government response (Introduction; licensing; exemptions; next steps)
The FCA found misleading promotions and unsuitable advice in later-life mortgage sales, including inadequate consideration of alternatives and incentives that could favour sales. Its intervention led reviewed firms to change their processes. Rolling up interest can substantially increase lifetime-mortgage debt; suitability and clear total-cost explanations remain important.
Measured factConfidence: High· FCA review, September 2023· United Kingdom
Source: Financial Conduct Authority, Action needed to ensure good outcomes for later life mortgage borrowers (Summary of findings: financial promotions and suitability of advice)
Mean private rent was 36.3% of median gross renter-household income, and 41.6% in London. This is a ratio of averages, not every household’s rent burden; the England share has not risen steadily.
Measured factConfidence: High· 2023-24· England
Source: ONS, Private rental affordability, England, Wales and Northern Ireland: 2024 (Table 3)
Of 4,724 monitored residential buildings at least 11 metres high with unsafe cladding, 2,153 had not started remediation. This monitored portfolio is not a count of every unsafe home; coverage changes over time.
Measured factConfidence: High· August 2026· England
Source: MHCLG, MHCLG (Overview: remediation progress)
4 million dwellings (15%) did not meet the Decent Homes Standard; 1.4 million (5%) had damp. Existing-home condition needs attention alongside supply and affordability. The categories overlap.
Measured factConfidence: High· 2024· England
Source: MHCLG, English Housing Survey 2024–25: housing quality and energy efficiency (Key findings: non-decent dwellings and damp)
A typical home costs 7.6 times full-time annual earnings, against 3.5 in 1997 (the early earnings basis differs in 1997–98).
Measured factConfidence: High· 2025 (1997 reference)· England
Source: Office for National Statistics, Housing affordability in England and Wales: 2025 (Table 1c)
No commitment found. There is no official target for the house-price-to-earnings ratio. The related commitment is supply: 1.5 million homes in England this Parliament, re-stated under Burnham (see housing-w3), alongside ministers' stated aim to help more people into home ownership.
Searched: gov.uk search "affordability", "house prices", "home ownership" from 2026-07-20; MHCLG news 17 and 25 Aug 2026; Burnham tracker (no affordability pledge).
Checked 4 October 2026. A commitment is not delivery.
Turn permissions into completed homes where the ratio is highest
More completions in high-ratio areas add to supply where prices are furthest from earnings.
Who: MHCLG; local planning authorities · Evidence: Modelled scenario · Status: Site-editorial action
Source: Office for Budget Responsibility, Economic and fiscal outlook, March 2025 (Paragraphs 1.10 and 3.37)
Grow the construction workforce
More skilled workers let higher demand become more homes rather than higher build costs.
Who: DfE / Skills England; CITB; employers · Evidence: Observational analysis · Status: Established
Source: CITB, Construction Workforce Outlook 2026–2030 (Headline annual recruitment requirement)
Address housing costs directly as the driver of the generational divide
Treats housing cost as the main lever on cohesion and living standards rather than income alone.
Who: MHCLG; HM Treasury · Evidence: Untested proposal · Status: External proposal · Works through Inequality: Treats housing cost as the main lever on cohesion and living standards rather than income alone.
135,580 households, including 177,530 children, were in temporary accommodation.
Measured factConfidence: High· March 2026· England
Source: MHCLG, Statutory homelessness: England time series (Table TA1)
Options assessed against this point: Settled homes for families in temporary accommodation (Amber delivery RAG)
Policy: The National Plan to End Homelessness (December 2025) set a target to eliminate the use of B&Bs for families, except very short emergency use, by the end of this Parliament, with £950m for round 4 of the Local Authority Housing Fund to grow good-quality temporary accommodation. There is no target for the number of households in temporary accommodation. Under Burnham the government has announced Social Housing Bill amendments (28 September 2026) to let councils refer homeless households to housing associations, "helping to reduce reliance on temporary accommodation", and a duty to collaborate on prevention.
Checked 4 October 2026. A commitment is not delivery.
ShortlistedUse social-housing funding to reduce temporary accommodation
Links Social Rent awards to lettings for households in TA, reducing the stock of households waiting.
Who: MHCLG; Homes England and the GLA; councils · Evidence: Modelled scenario · Status: Funded programme
Source: Prime Minister’s Office and MHCLG, Historic council housebuilding comeback to help families into secure homes (Body and Notes to editors: £9.58bn to 33 Strategic Partners, 73,600 homes; "More than £16 billion remains to be allocated outside London"; "builds on the government's commitment to deliver 1.5 million homes this Parliament"; £46m Capacity to Build)
Let councils refer homeless households to housing associations (Social Housing Bill)
A statutory referral route moves TA households into existing social lettings faster.
Who: MHCLG; Parliament; councils and private registered providers · Evidence: Untested proposal · Status: Announced proposal
Source: MHCLG, Social Housing Bill to strengthen homelessness prevention and protect social housing stock (Body: referral powers to private registered providers; disposals notification (eight weeks); Duty to Collaborate; "previously committed £39 billion")
Restore Local Housing Allowance to the 30th percentile of local rents
Reduces the shortfall that pushes private renters into homelessness, the leading route into TA.
Who: DWP; HM Treasury · Evidence: Expert or audit recommendation · Status: External proposal · Works through Benefits: Reduces the shortfall that pushes private renters into homelessness, the leading route into TA.
Source: MHCLG (response to Housing, Communities and Local Government Committee), Housing conditions in temporary accommodation: government response to the HCLG Committee report (Recommendations 14 (TA subsidy), 17 (restore LHA to 30th percentile), 19 (SAHP prioritisation) and government responses paras 73-74, 81-82, 86-88)
Unfreeze the housing benefit subsidy councils receive for temporary accommodation
Reduces councils' net cost of TA and lets them lease better-quality homes, cutting B&B and nightly-paid use.
Who: DWP; MHCLG · Evidence: Expert or audit recommendation · Status: External proposal
Source: MHCLG (response to Housing, Communities and Local Government Committee), Housing conditions in temporary accommodation: government response to the HCLG Committee report (Recommendations 14 (TA subsidy), 17 (restore LHA to 30th percentile), 19 (SAHP prioritisation) and government responses paras 73-74, 81-82, 86-88)
Grow councils' own temporary accommodation stock (Local Authority Housing Fund round 4)
Council-owned TA replaces expensive nightly-paid and B&B placements.
Who: MHCLG; councils · Evidence: Observational analysis · Status: Funded programme
Source: MHCLG (cross-government), A National Plan to End Homelessness (Summary, "Immediate action on temporary accommodation": target to eliminate B&B use for families by end of Parliament; £950m LAHF round 4; halve long-term rough sleeping; £3.5bn over three years (section 7))
England added 208,600 homes, against about 300,000 a year implied by the government’s 1.5 million ambition.
Measured factConfidence: High· 2024–25· England
Source: MHCLG, Housing supply: net additional dwellings, England (Live Table 120); Centre for Cities, A zoning system for England (PDF pp.2–3)
Options assessed against this point: Homes built, not just permitted (Red delivery RAG)
Target: The government is committed to building 1.5 million homes in England this Parliament, a Plan for Change milestone set in December 2024. The Burnham government re-stated it on 5 and 25 August 2026.
Checked 4 October 2026. A commitment is not delivery.
ShortlistedTurn permissions into homes people can live in
Targets the stall between permission and start so net additions rise towards 300,000 a year.
Who: MHCLG with local planning authorities · Evidence: Untested proposal · Status: Site-editorial action
Source: Office for Budget Responsibility, Economic and fiscal outlook, March 2025 (Paragraphs 1.10 and 3.37)
Fund Social Rent through the programme as a counter-cyclical source of completions
Grant-funded homes continue when market sales slow, supporting total additions.
Who: MHCLG; Homes England · Evidence: Observational analysis · Status: Funded programme
Source: Prime Minister’s Office and MHCLG, Historic council housebuilding comeback to help families into secure homes (Body and Notes to editors: £9.58bn to 33 Strategic Partners, 73,600 homes; "More than £16 billion remains to be allocated outside London"; "builds on the government's commitment to deliver 1.5 million homes this Parliament"; £46m Capacity to Build)
Expand the construction workforce
Removes a capacity limit on how fast completions can rise.
Who: DfE / Skills England; CITB · Evidence: Observational analysis · Status: Established
Source: CITB, Construction Workforce Outlook 2026–2030 (Headline annual recruitment requirement)
Publish an annual check of progress against the 1.5 million milestone, alongside the OBR forecast
Makes the gap between ambition and forecast visible each year, so delivery shortfalls are corrected early.
Who: MHCLG; OBR · Evidence: Observational analysis · Status: Site-editorial action
Source: Office for Budget Responsibility, Economic and fiscal outlook – March 2026 (Paragraph 2.38: net additions fall to 220,000 in 2026-27, rise to just over 305,000 by 2030-31; reforms' impact "has yet to meaningfully materialise in outturn"; cumulative UK net additions 2025-26 to 2029-30 of 1.3 million)
Prevention works for just over half of households: of 35,130 prevention duties that ended in January–March 2026, 54.7% ended with a home secured for six months or more and 25% became homeless. The end of a private tenancy was the most common reason among the 39,200 households owed a duty (36.0%).
Measured factConfidence: High· January to March 2026· England
Source: Ministry of Housing, Communities and Local Government, Statutory homelessness in England: January to March 2026 (Main findings; sections 4 and 5)
Options assessed against this point: Prevent avoidable loss of rented homes (Amber delivery RAG)
Legislation: The 56-day prevention duty now covers section 8 notices (Renters’ Rights Act 2025, in force 1 May 2026, when section 21 was abolished for private assured tenancies), with new-burdens money in the Homelessness, Rough Sleeping and Domestic Abuse Grant (£885.0m in 2026–27).
Checked 7 October 2026. A commitment is not delivery.
Keeps tenancies going or secures another home before temporary accommodation is needed.
Who: Councils with MHCLG and the Ministry of Justice · Evidence: Experimental or quasi-experimental evaluation · Status: External proposal
Source: MHCLG (ICF and Bryson Purdon Social Research), Evaluation of the Homelessness Prevention Trailblazers (Section 5.2, Tables 5.2 and 5.5); Law & Society Review 35:419–434, The impact of legal counsel on outcomes for poor tenants in New York City’s Housing Court: results of a randomized experiment (Results tables)
Run the 56-day prevention duty with the homelessness grant as now
Councils help households threatened with homelessness before they lose their home.
Who: Councils with MHCLG · Evidence: Experimental or quasi-experimental evaluation · Status: Established
Source: MHCLG (ICF and Bryson Purdon Social Research), Evaluation of the Homelessness Prevention Trailblazers (Section 5.2); Ministry of Housing, Communities and Local Government, Allocations tables for all consolidated grants from 2026-27 to 2028-29 (final) (“Drop down” sheet, footnote 4)
Fund legal advice for families facing eviction (Legal Support Grant)
More advice capacity in places without legal aid providers.
Who: Ministry of Justice · Evidence: Untested proposal · Status: Funded programme
Source: Ministry of Justice, £16m legal lifeline for families facing eviction and hardship (Opening paragraphs)
Pairing deliverable sites with the new social-rent programme could turn grant into lettings for households in temporary accommodation.
Depends on: Named awards go to additional homes on sites whose infrastructure is funded, and councils can let them to homeless households.
Our synthesisConfidence: Moderate
Source: MHCLG / Homes England / GLA, Social and Affordable Homes Programme 2026 to 2036 (collection; MHCLG policy statement; Homes England prospectus) (Policy statement “Delivery routes”); Office for Budget Responsibility, Economic and fiscal outlook, March 2025 (Paragraph 3.37)
Options assessed against this point: Settled homes for families in temporary accommodation (Amber delivery RAG)
Policy: The government intends to prioritise Social Rent and council homes in the remaining Social and Affordable Homes Programme funding, and (28 September 2026) to give councils a power to refer homeless households to housing associations. No commitment links programme awards to temporary-accommodation outcomes.
Checked 4 October 2026. A commitment is not delivery.
ShortlistedUse social-housing funding to reduce temporary accommodation
Named awards for additional Social Rent homes on sites with funded infrastructure, let to TA households.
Who: MHCLG; Homes England; councils · Evidence: Modelled scenario · Status: Funded programme
Source: Prime Minister’s Office and MHCLG, Historic council housebuilding comeback to help families into secure homes (Body and Notes to editors: £9.58bn to 33 Strategic Partners, 73,600 homes; "More than £16 billion remains to be allocated outside London"; "builds on the government's commitment to deliver 1.5 million homes this Parliament"; £46m Capacity to Build)
Pair programme awards with deliverable, permitted sites
Directs grant to sites whose blockers are known and costed, so grant becomes lettings.
Who: MHCLG; local planning authorities · Evidence: Untested proposal · Status: Site-editorial action
Source: Office for Budget Responsibility, Economic and fiscal outlook, March 2025 (Paragraphs 1.10 and 3.37)
Use the Social Housing Bill referral power to let new Social Rent homes to TA households
Gives councils a legal route into housing-association lettings.
Who: MHCLG; councils; housing associations · Evidence: Untested proposal · Status: Announced proposal
Source: MHCLG, Social Housing Bill to strengthen homelessness prevention and protect social housing stock (Body: referral powers to private registered providers; disposals notification (eight weeks); Duty to Collaborate; "previously committed £39 billion")
The OBR estimated in March 2025 that the December 2024 changes to the National Planning Policy Framework would add about 170,000 homes over five years. The estimate was made before the Planning and Infrastructure Act 2025 and is not an estimate of that Act.
Depends on: Councils apply the revised framework and the permitted homes are built. The OBR calls its own judgement uncertain, and in March 2026 said the effect had “yet to meaningfully materialise in outturn”.
Modelled estimate, not an observed resultConfidence: Limited· March 2025 forecast, for 2025–26 to 2029–30· United Kingdom
Source: Office for Budget Responsibility, Economic and fiscal outlook, March 2025 (Paragraphs 1.10 and 3.37); Office for Budget Responsibility, The supply-side impact of planning reforms: land value uplift and construction sector productivity (Opening summary; the land-value-share and construction-productivity judgements); Office for Budget Responsibility, Economic and fiscal outlook – March 2026 (Paragraph 2.38)
Lower deposits and easier lending can widen access but leave borrowers with less equity and more exposure to income, rate and house-price shocks. Your First Home was announced in September 2026; its final terms, public cost and additional supply effects are not yet established. Responsible-lending safeguards remain essential.
Risk, not a certaintyConfidence: Moderate· 2026· United Kingdom; Your First Home is England only
Source: Bank of England, Financial Stability Report July 2026 (Household debt and mortgage lending safeguards); MHCLG, New first-time buyer scheme to be confirmed at Budget (Announcement and Budget details pending)
Build-cost inflation, shortages of materials and labour, stretched planning teams and delays with utilities can mean fewer completions than planned — as the NAO found for the last programme.
Risk, not a certaintyConfidence: Moderate
Source: National Audit Office, The Affordable Homes Programme since 2015 (Summary, paragraphs 14–15)
Options assessed against this point: Homes built, not just permitted (Red delivery RAG)
Funding: No commitment addresses build-cost and capacity risk directly. The government funds council capacity (£46m Capacity to Build, announced 25 August 2026), and the OBR will reassess the planning reforms in the Autumn 2026 EFO.
Checked 4 October 2026. A commitment is not delivery.
Publish programme delivery against forecast each year, as the NAO recommended for the last programme
Early warning when costs push completions below plan, as happened in 2021-26.
Who: MHCLG; Homes England · Evidence: Expert or audit recommendation · Status: External proposal
Source: National Audit Office, The Affordable Homes Programme since 2015 (Summary paragraphs 14-15)
Grow the construction workforce
Eases the labour constraint that raises costs and slows completions.
Who: DfE / Skills England; CITB; Home Office · Evidence: Observational analysis · Status: Established
Source: CITB, Construction Workforce Outlook 2026–2030 (Headline annual recruitment requirement)
Fund council capacity to develop and acquire homes
Reduces the risk that councils cannot turn grant into schemes.
Who: MHCLG; LGA; Homes England · Evidence: Untested proposal · Status: Funded programme
Source: Prime Minister’s Office and MHCLG, Historic council housebuilding comeback to help families into secure homes (Body and Notes to editors: £9.58bn to 33 Strategic Partners, 73,600 homes; "More than £16 billion remains to be allocated outside London"; "builds on the government's commitment to deliver 1.5 million homes this Parliament"; £46m Capacity to Build)
Sequence reforms that depend on the same people and infrastructure
Avoids several programmes competing for the same builders and utilities at once.
Who: HM Treasury; MHCLG · Evidence: Untested proposal · Status: Site-editorial action
Source: HM Treasury and NISTA, UK Infrastructure: A 10 Year Strategy (Paragraph 1.28; Annex paragraph 3)
About 6.3 million properties in England are in areas at risk of flooding from rivers, the sea or surface water; with climate change the Environment Agency projects around 8 million — 1 in 4 properties — by mid-century.
Risk, not a certaintyConfidence: Moderate· 2024 assessment; projection to mid-century· England
Source: Environment Agency, National assessment of flood and coastal erosion risk in England 2024 (Executive summary, printed p.3); Climate Change Committee, Progress in adapting to climate change – 2025 report to Parliament (Printed p.12)
Options assessed against this point: Protect flood-defence maintenance and appraise schemes by risk (Amber delivery RAG)
Funding: £7.9bn over ten years for flood defences, £4.2bn of it in 2026–27 to 2028–29, with a consultation on a simpler way to bid for the money (Spending Review 2025).
Checked 4 October 2026. A commitment is not delivery.
Money follows the homes most at risk and shortfalls show early, as the last programme’s did not.
Who: Defra and the Environment Agency · Evidence: Expert or audit recommendation · Status: Funded programme
Source: National Audit Office, Resilience to flooding (Summary, paragraphs 16 and 22); Department for Environment, Food & Rural Affairs and Environment Agency, Hundreds of thousands of homes and businesses to benefit from largest flood defence investment programme in history (Press release, paragraphs 1–4)
Fund adaptation at the scale the Climate Change Committee assesses as needed
More defences, drainage and property-level protection than the current settlement buys.
Who: HM Treasury and Defra · Evidence: Expert or audit recommendation · Status: External proposal
Source: Climate Change Committee, Progress in adapting to climate change – 2025 report to Parliament (Executive summary, printed p.10)
Managed retreat from the most exposed coastal frontages
Stops defending places where the cost rises faster than the value protected, with help to move.
Who: Defra, the Environment Agency and coastal councils · Evidence: Untested proposal · Status: External proposal
Price flood risk in home insurance rather than pooling it
Signals risk to buyers and builders, but can leave some homes uninsurable.
Who: HM Treasury, Defra and insurers · Evidence: Untested proposal · Status: External proposal
Our shortlist for this page. Research quality, policy status, cost and funding are judged separately; none of these is government policy unless its status says so.Our shortlist. None is government policy unless its status says so.
Action 1A01Policy status: site-editorial action
Name the blocker, owner and infrastructure cost for each priority site, then fund and sequence the connections that let building start.
The thread: issue, evidence, action
Assessment (draft, 6 October review)
A new scope of this action (A01v2): Homes built, not just permitted
Delivery RAG: RedGate: pending
Range if completed: 14.0–20.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))
National plan: Growth and prosperity list
Not yet costed
Funding: Not yet costed / funding not identifiedWhy it is shortlisted here: Permissions are not homes: this targets the step where the pipeline stalls.
Permissions and plans do not become occupied homes when sites are held up by missing infrastructure, viability, finance or builders.
Households who need a home in high-demand areas of England. Territory: England. Planning is devolved: Scotland, Wales and Northern Ireland run separate systems and would need their own decisions; not assessed here.
UK Facts proposal. Builds on reforms already in place: the National Planning Policy Framework published on 17 August 2026, which replaced the December 2024 version, and the Planning and Infrastructure Act 2025 (Royal Assent 18 December 2025). The site-by-site blocker list is a UK Facts proposal, not government policy.
Cost completeness: Not yet costed. Funding: Not yet costed / funding not identified.
First step: Publish the actual blocker, owner and infrastructure cost for a small set of priority sites. (owner: MHCLG with local planning authorities)
Depends on: Construction workforce; Utility connection capacity
This card replaces the option “Faster, more predictable planning decisions” (legislated: Revised National Planning Policy Framework (December 2024, the change the OBR estimate covers); Planning and Infrastructure Act 2025 received Royal Assent on 18 December 2025 (not covered by that estimate).). Its evidence: The OBR estimated in March 2025 that the December 2024 changes to the National Planning Policy Framework would add about 170,000 homes over five years — a conditional, modelled effect, not an observed one, made before the Planning and Infrastructure Act 2025 and not covering it. A high approval rate does not show planning is no constraint, because it excludes applications never made and says nothing about delays after approval. OBR, Economic and fiscal outlook, March 2025 (housing and planning reforms) · OBR, The supply-side impact of planning reforms (14 August 2025)
Source published March 2025 (OBR); 2025 (LSE); February 2025 (Centre for Cities); evidence reviewed 2026-10-04. Reconsider if: The OBR publishes a new estimate of the planning reforms; Net additions move decisively away from the 2024–25 level; The government publishes site-level infrastructure data.
Also on: Economy, Growth — one shared record, so its cost is counted once.
Action 2A02Policy status: funded programme
Steer named awards from the social and affordable homes programme to additional social-rent homes that councils can let to households in temporary accommodation.
The thread: issue, evidence, action
Assessment (draft, 6 October review)
This action: Settled homes for families in temporary accommodation
Delivery RAG: AmberGate: pending
Range if completed: 19.0–22.0 out of 30 (equal weights; not yet assessed: incremental affordability (Co))
National plan: Equality and opportunity list
£39bn in total, 2026–27 to 2035–36, price basis not stated by the source; 1 further cost line, some not yet costed
Funding: Programme funding exists; project allocation unconfirmedWhy it is shortlisted here: Temporary accommodation is the sharpest housing harm on this page, and a funded programme already exists to act on it.
Record numbers of households are in temporary accommodation while a new social-housing programme is being allocated: the first allocations (25 August 2026) fund supply in general, not homes for households in temporary accommodation.
Homeless households in temporary accommodation, and households on social-housing waiting lists, in England. Territory: England. Housing is devolved; Scotland, Wales and Northern Ireland have separate programmes, not assessed here.
A funded programme already exists. The Social and Affordable Homes Programme 2026–2036 (£39bn envelope) made its first allocations on 25 August 2026 (£9.58bn to 33 strategic partners outside London; more than £16bn outside London and around £5bn in London still to allocate), under the Burnham government; its aim is supply, especially social rent, with temporary accommodation a stated use only for limited acquisitions. The dedicated temporary-accommodation capital route is the separate Local Authority Housing Fund, not assessed here. Linking awards to temporary-accommodation outcomes is a UK Facts proposal.
Cost completeness: Published programme envelope; project costs still needed. Funding: Programme funding exists; project allocation unconfirmed.
First step: Link a named allocation to a tenure mix, timetable and the households it will serve. (owner: Homes England, GLA and councils)
Depends on: A01: deliverable sites; Construction capacity
This card replaces the option “Grant for social and affordable homes” (funded: Social and Affordable Homes Programme 2026–2036: up to £39bn over ten years.). Its evidence: The previous programme delivered homes but fewer than planned: the National Audit Office found in 2022 that the 2021 programme was expected to complete about 157,000 homes against a target of up to 180,000, as build costs rose. The new programme aims for about 300,000 homes over ten years, at least 60% for social rent. National Audit Office, The Affordable Homes Programme since 2015 (September 2022) · MHCLG, Social and Affordable Homes Programme 2026 to 2036
Source published November 2025 (programme documents); September 2022 (NAO); August 2026 (first allocations); evidence reviewed 2026-10-04. Reconsider if: Programme allocations are published; Temporary accommodation numbers change direction; A new NAO report on the programme.
Also on: Hampshire — one shared record, so its cost is counted once.
Action 3A54Policy status: funded programme
Allocating the 2026–29 programme against the 2024 national flood risk assessment, funding maintenance of existing defences first and publishing homes better protected each year makes money follow risk and shows shortfalls early, while there is still time to change course.
The thread: issue, evidence, action
Assessment (draft, 6 October review)
This action: Protect flood-defence maintenance and appraise schemes by risk
Delivery RAG: AmberGate: pending
Range if completed: 15.0–21.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))
National plan: Resilience and sustainability appraisal queue
£4.2bn in total, 2026–27 to 2028–29, price basis not stated by the source
Funding: Programme funding exists; project allocation unconfirmedWhy it is shortlisted here: Flood risk is the climate threat to homes with an official map and a funded programme; the decision is how that money follows the risk.
About 6.3 million properties in England are in areas at risk of flooding, around 8 million by mid-century; the last capital programme expected to better protect 40% fewer properties than first planned, and existing defences were not maintained to the level that gives best value.
Households and businesses in areas of England at risk of flooding from rivers, the sea and surface water, especially those at high risk. Territory: England. Flood risk management is devolved: Natural Resources Wales, the Scottish Environment Protection Agency and councils, and the Department for Infrastructure (Rivers) in Northern Ireland run their own programmes; not reviewed here.
A funded programme already exists. The Starmer government committed £7.9bn over ten years and £4.2bn for 2026–27 to 2028–29 (16 June 2025) and consulted on a simpler way to bid for flood-defence funding. Allocating against the 2024 risk assessment, protecting maintenance and publishing homes better protected against that map each year are a UK Facts proposal; whether the Burnham government has kept the settlement unchanged is not confirmed here.
Cost completeness: Published programme envelope; project costs still needed. Funding: Programme funding exists; project allocation unconfirmed.
First step: Defra and the Environment Agency publish how the 2026–29 programme is allocated against the 2024 risk assessment, the maintenance budget against the condition target, and a baseline of homes better protected. (owner: Defra and the Environment Agency)
Depends on: The outcome of the 2025 consultation on flood-defence funding rules; Construction capacity shared with housing and infrastructure
Source published 15 November 2023 (NAO); 17 December 2024 (risk assessment); 16 June 2025 (funding); evidence reviewed 2026-10-04. Reconsider if: The government response to the flood-funding consultation; The next Environment Agency national risk assessment update; A Burnham-government Budget or Spending Review changing the flood settlement.
Action 4A74Policy status: external proposal
Early legal and money advice, landlord negotiation and targeted help with arrears for renters served notice or in arrears keeps tenancies going or secures another home before households need temporary accommodation.
The thread: issue, evidence, action
Assessment (draft, 6 October review)
This action: Prevent avoidable loss of rented homes
Delivery RAG: AmberGate: pending
Range if completed: 16.0–22.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))
National plan: Related option, assessed separately
Not yet costed
Funding: Not yet costed / funding not identifiedWhy it is shortlisted here: The tenancy-loss prevention option (related to settled homes for families, NE3): the end of a private tenancy is the commonest route to a prevention duty and just over half of duties end with a secure home; early advice, tested against comparison councils, is the bounded change. It builds on the renters option card, which stays.
Builds on the option Support and security for private renters compared below.
Councils prevent homelessness for just over half of households owed a prevention duty, and the end of a private tenancy is the most common reason for being threatened with homelessness, while temporary accommodation is at a record level.
Private and social renters in England threatened with homelessness through a notice or rent arrears, in defined council areas, before a prevention duty would otherwise fail. Territory: England. Wales created the prevention duty model (Housing (Wales) Act 2014 s.66); Scotland has new prevention duties (Housing (Scotland) Act 2025 Part 5); Northern Ireland’s Housing Executive delivers homelessness services. Not assessed.
Proposed by researchers or others, not government policy. Funded baseline: the 56-day prevention duty (extended to section 8 notices from 1 May 2026), the Homelessness, Rough Sleeping and Domestic Abuse Grant (£885.0m in 2026–27), the Housing Loss Prevention Advice Service and a £16m Legal Support Grant (October 2026 to March 2029). Testing a defined early-advice offer against comparison areas is a UK Facts proposal, not government policy.
Cost completeness: Not yet costed. Funding: Not yet costed / funding not identified.
First step: MHCLG and five councils agree a defined early-advice offer for renters served notice or in arrears, with comparison councils, and report the share of prevention duties ending with a secure home. (owner: MHCLG with councils and the Ministry of Justice)
Depends on: Reason coding after the section 21 to section 8 change (first full quarter due 29 October 2026); Advice provider capacity
Source published 13 August 2026 (MHCLG); 25 March 2019 (Trailblazers evaluation); evidence reviewed 2026-10-07. Reconsider if: Statutory homelessness, April–June 2026 (29 October 2026); The 2025–26 annual release (26 November 2026).
One shared record per option — the same one the national plan reads. Delivery RAG, gate and list membership are separate judgements.
Provisional single-reviewer assessments from the 6 October 2026 review; not approved business cases, and not government policy.
A01v2Delivery RAG: RedGate: pending
A new scope of action A01 (A01v2); A01 itself is unchanged and nothing is inherited from it.
Provisional single-reviewer assessment; not an approved business case.
Permissions are not completions. Infrastructure, finance, build-out and tenure determine whether an additional permission becomes a useful home.
Codex — AI-assisted analytical follow-up · 8 October 2026. Proposed appraisal design; the attributed scores below are unchanged. No funding or delivery agreement is implied.
Read with the outcome evidence and sources in the full assessment. Monitoring proposals are not existing baseline measurements. A numerical benefit or cost score needs evidence for the defined increment, not just the scale of the problem.
Each criterion is scored 0 to 3 by the reviewer. “Not yet assessed” means unknown: it is never counted as zero.
Scale and severity (Sc)3 of 3 — Severe harm across a broad population
Reviewer’s reason: Provisional problem-importance judgement from linked site pages; not the scale of achievable benefit.
Increment beyond baseline (Ad)2 of 3 — Specific material change to existing delivery
Reviewer’s reason: Select sites; resolve land, planning, utilities, transport and viability; commission tenure mix and delivery agreements. A missing rating requires a defined marginal change.
Confidence in the proposed action (Ev)1 of 3 — Indirect, mixed, modelled or weak causal support
Reviewer’s reason: Housing constraints and modelled supply responses support the case; no evaluated national effect for this exact site-unblocking package.
Expected incremental benefit (Bn)Not yet assessed
Reviewer’s reason: Unknown unless a reasonably defined target-population benefit can be judged; no bonus merely for spanning domains.
Residual harms (Hm)1 of 3 — Material harm/unresolved mitigation
Reviewer’s reason: Binding construction/infrastructure constraints; environmental and displacement harms.
Incremental affordability (Co)Not yet assessed
Reviewer’s reason: Site-level land, infrastructure, finance, construction, affordable-housing subsidy and maintenance.
Delivery capacity (Ca)1 of 3 — Binding scarce resource
Reviewer’s reason: Select sites; resolve land, planning, utilities, transport and viability; commission tenure mix and delivery agreements.
Distribution (Fa)2 of 3 — Mixed or broadly neutral with safeguards
Reviewer’s reason: Provisional distribution judgement for the stated target; verify who pays, who gains and excluded groups.
Meaningful first outcome (Ti)2 of 3 — More than one and up to three years
Reviewer’s reason: First meaningful outcome, not announcement: Net additional completed and occupied homes, affordability and displacement.
Readiness (Rd)2 of 3 — Named commissioning/allocation/coordination step
Reviewer’s reason: Planning authorities, housing bodies, developers and utilities; devolved responsibility; Site-specific investment appraisal
Normalised as 10 × weighted sum ÷ sum of weights, on a 0–30 scale. Where a criterion is not yet assessed, the range is the lowest and highest result if it were later scored 0 or 3 — not a score, a confidence interval or a rank.
Funding gate: Not passed — the cost is not yet assessed or no allocation is committed for this scope. Ignoring cost in a weighting never removes the gate.
Delivery RAG shown: RedReview’s claim: Red. Best the recorded evidence allows: Red.
Review’s reason: Binding construction/infrastructure constraints; environmental and displacement harms.
Why it is not Green yet
Green needs verified scope, a verified owner with the powers, verified capacity, complete lifetime costs with credible funding, specified safeguards and monitoring with a metric, source and baseline. Amber means appraisal gaps remain; Red means a material delivery obstacle. Red does not mean unimportant.
Gate: Pending — appraisal incomplete (review label: “Pending: incomplete appraisal”).
Why: Scores incomplete; Funding gate not passed (cost unknown or no credible funding).
The gate is separate from national list membership: being listed does not make an option eligible, and an eligible option need not be listed.
Lifetime costing: Not established. Review: “Full incremental costing not established in reviewed material”.
Still to cost: Site-level land, infrastructure, finance, construction, affordable-housing subsidy and maintenance.
Funding status: not established in review.
Proposed owner: Planning authorities, housing bodies, developers and utilities; devolved responsibility (proposed, unverified).
Powers: needs a decision or allocation. Capacity: binding constraint.
Powers and capacity read from the review’s Rd and Ca anchors; no proposed owner has agreed to act (the review: “Proposed owners have not agreed to act”).
Not defined in the review.
Depends on: None recorded.
Safeguards
None specified yet.
Risks and residual harms: Binding construction/infrastructure constraints; environmental and displacement harms.
Metric: Net additional completed and occupied homes, affordability and displacement.
Data source: Not yet named. Baseline: Not yet established.
Measures already on the domain page
A page measure is not necessarily the review’s metric; linking the two is an editorial decision still to be made.
Outcome: Net additional completed and occupied homes, affordability and displacement.
Housing constraints and modelled supply responses support the case; no evaluated national effect for this exact site-unblocking package.
SWOT points it addresses
Assessment version: working-review-2026-10-06 (A01v2@working-review-2026-10-06).
Reviewer: Author of the review blueprint (single reviewer, not named in uk-facts-complete-plan.json). Reviewed: 6 October 2026.
Scored in the working review of 6 October 2026 on the shared ten-criterion scale (one reviewer); not independently calibrated.
First 90 days (review): Produce a signed scope and current-delivery baseline; Select sites; resolve land, planning, utilities, transport and viability; commission tenure mix and delivery agreements. Obtain incremental costs and an accountable decision before expansion.
Decision route: Site-specific investment appraisal
An editorial screening framework by one reviewer, not a formal appraisal or business case. Proposed owners have not agreed to act.
A02Delivery RAG: AmberGate: pending
Existing action A02, assessed at the same scope.
Provisional single-reviewer assessment; not an approved business case.
Temporary accommodation counts establish need, not which purchase, build or lease option provides best value. Supported housing may require continuing support.
Codex — AI-assisted analytical follow-up · 8 October 2026. Proposed appraisal design; the attributed scores below are unchanged. No funding or delivery agreement is implied.
Read with the outcome evidence and sources in the full assessment. Monitoring proposals are not existing baseline measurements. A numerical benefit or cost score needs evidence for the defined increment, not just the scale of the problem.
Each criterion is scored 0 to 3 by the reviewer. “Not yet assessed” means unknown: it is never counted as zero.
Scale and severity (Sc)3 of 3 — Severe harm across a broad population
Reviewer’s reason: Provisional problem-importance judgement from linked site pages; not the scale of achievable benefit.
Increment beyond baseline (Ad)2 of 3 — Specific material change to existing delivery
Reviewer’s reason: Define families and locations; compare acquisition, lease and new build; inspect standards; secure lettings and tenancy support. A missing rating requires a defined marginal change.
Confidence in the proposed action (Ev)1 of 3 — Indirect, mixed, modelled or weak causal support
Reviewer’s reason: US subsidy evidence supports housing stability but does not establish UK acquisition/build effects or local value for money.
Expected incremental benefit (Bn)3 of 3 — Large for the target population; no multi-domain bonus
Reviewer’s reason: Unknown unless a reasonably defined target-population benefit can be judged; no bonus merely for spanning domains.
Reason and score disagree — under review
Residual harms (Hm)2 of 3 — Manageable harm with specified safeguards
Reviewer’s reason: Competition with other buyers; displacement; unsuitable location/condition.
Incremental affordability (Co)Not yet assessed
Reviewer’s reason: Capital, finance, refurbishment, rent, maintenance, support and actual avoided temporary-accommodation costs.
Delivery capacity (Ca)1 of 3 — Binding scarce resource
Reviewer’s reason: Define families and locations; compare acquisition, lease and new build; inspect standards; secure lettings and tenancy support.
Distribution (Fa)3 of 3 — Benefits concentrated on disadvantaged people with assessed burdens
Reviewer’s reason: Provisional distribution judgement for the stated target; verify who pays, who gains and excluded groups.
Meaningful first outcome (Ti)2 of 3 — More than one and up to three years
Reviewer’s reason: First meaningful outcome, not announcement: Sustained settled housing, repeat homelessness and household wellbeing.
Readiness (Rd)2 of 3 — Named commissioning/allocation/coordination step
Reviewer’s reason: Councils and housing providers; relevant national housing bodies; Local buy/build/lease comparison
Normalised as 10 × weighted sum ÷ sum of weights, on a 0–30 scale. Where a criterion is not yet assessed, the range is the lowest and highest result if it were later scored 0 or 3 — not a score, a confidence interval or a rank.
Funding gate: Not passed — the cost is not yet assessed or no allocation is committed for this scope. Ignoring cost in a weighting never removes the gate.
Delivery RAG shown: AmberReview’s claim: Amber. Best the recorded evidence allows: Amber.
Review’s reason: Capital, finance, refurbishment, rent, maintenance, support and actual avoided temporary-accommodation costs.
Why it is not Green yet
Green needs verified scope, a verified owner with the powers, verified capacity, complete lifetime costs with credible funding, specified safeguards and monitoring with a metric, source and baseline. Amber means appraisal gaps remain; Red means a material delivery obstacle. Red does not mean unimportant.
Gate: Pending — appraisal incomplete (review label: “Pending: incomplete appraisal”).
Why: Scores incomplete; Funding gate not passed (cost unknown or no credible funding).
The gate is separate from national list membership: being listed does not make an option eligible, and an eligible option need not be listed.
Lifetime costing: Partial — some lines costed, no whole-life total. Review: “Full incremental costing not established in reviewed material”.
Still to cost: Capital, finance, refurbishment, rent, maintenance, support and actual avoided temporary-accommodation costs.
Funding status: programme route, not allocated.
Proposed owner: Councils and housing providers; relevant national housing bodies (proposed, unverified).
Powers: needs a decision or allocation. Capacity: binding constraint.
Powers and capacity read from the review’s Rd and Ca anchors; no proposed owner has agreed to act (the review: “Proposed owners have not agreed to act”).
Housing is devolved; Scotland, Wales and Northern Ireland have separate programmes, not assessed here.
Depends on: None recorded.
Safeguards
None specified yet.
Risks and residual harms: Competition with other buyers; displacement; unsuitable location/condition.
Metric: Sustained settled housing, repeat homelessness and household wellbeing.
Data source: Not yet named. Baseline: Not yet established.
Measures already on the domain page
A page measure is not necessarily the review’s metric; linking the two is an editorial decision still to be made.
Outcome: Sustained settled housing, repeat homelessness and household wellbeing.
US subsidy evidence supports housing stability but does not establish UK acquisition/build effects or local value for money.
Effect records for this action
SWOT points it addresses
Assessment version: working-review-2026-10-06 (A02@working-review-2026-10-06).
Reviewer: Author of the review blueprint (single reviewer, not named in uk-facts-complete-plan.json). Reviewed: 6 October 2026.
Scored in the working review of 6 October 2026 on the shared ten-criterion scale (one reviewer); not independently calibrated.
First 90 days (review): Produce a signed scope and current-delivery baseline; Define families and locations; compare acquisition, lease and new build; inspect standards; secure lettings and tenancy support. Obtain incremental costs and an accountable decision before expansion.
Decision route: Local buy/build/lease comparison
An earlier assessment exists on the 4 October 2026 selection table (nine H/M/L bands; superseded 7 October 2026). Its bands are kept, not converted into these scores.
An editorial screening framework by one reviewer, not a formal appraisal or business case. Proposed owners have not agreed to act.
A74Delivery RAG: AmberGate: pending
Existing action A74, assessed at the same scope.
Not stated in the review record; treated as a provisional single-reviewer assessment, not an approved business case.
Prevention-duty outcomes describe households served; they do not measure how many tenancies a new advice service would additionally save.
Codex — AI-assisted analytical follow-up · 8 October 2026. Proposed appraisal design; the attributed scores below are unchanged. No funding or delivery agreement is implied.
Read with the outcome evidence and sources in the full assessment. Monitoring proposals are not existing baseline measurements. A numerical benefit or cost score needs evidence for the defined increment, not just the scale of the problem.
Each criterion is scored 0 to 3 by the reviewer. “Not yet assessed” means unknown: it is never counted as zero.
Scale and severity (Sc)3 of 3 — Severe harm across a broad population
Increment beyond baseline (Ad)2 of 3 — Specific material change to existing delivery
Confidence in the proposed action (Ev)1 of 3 — Indirect, mixed, modelled or weak causal support
Expected incremental benefit (Bn)Not yet assessed
Residual harms (Hm)1 of 3 — Material harm/unresolved mitigation
Incremental affordability (Co)Not yet assessed
Delivery capacity (Ca)2 of 3 — Stretched but plausibly obtainable
Distribution (Fa)3 of 3 — Benefits concentrated on disadvantaged people with assessed burdens
Meaningful first outcome (Ti)2 of 3 — More than one and up to three years
Readiness (Rd)2 of 3 — Named commissioning/allocation/coordination step
Normalised as 10 × weighted sum ÷ sum of weights, on a 0–30 scale. Where a criterion is not yet assessed, the range is the lowest and highest result if it were later scored 0 or 3 — not a score, a confidence interval or a rank.
Funding gate: Not passed — the cost is not yet assessed or no allocation is committed for this scope. Ignoring cost in a weighting never removes the gate.
Delivery RAG shown: AmberReview’s claim: Amber. Best the recorded evidence allows: Amber.
Review’s reason: Define arrears/risk trigger, legal advice and assistance design; cost staff, grants and sustained tenancies. Assess additional prevention against existing duties. Proposed owners: councils, housing/advice providers and landlords.
Why it is not Green yet
Green needs verified scope, a verified owner with the powers, verified capacity, complete lifetime costs with credible funding, specified safeguards and monitoring with a metric, source and baseline. Amber means appraisal gaps remain; Red means a material delivery obstacle. Red does not mean unimportant.
Gate: Pending — appraisal incomplete (review label: “Pending baseline verification, incremental costing and funding; not a rollout approval”).
Why: Scores incomplete; Funding gate not passed (cost unknown or no credible funding).
The gate is separate from national list membership: being listed does not make an option eligible, and an eligible option need not be listed.
Lifetime costing: Not established. Review: “Not fully costed in this review”.
Still to cost: Define arrears/risk trigger, legal advice and assistance design; cost staff, grants and sustained tenancies. Assess additional prevention against existing duties. Proposed owners: councils, housing/advice providers and landlords.
Funding status: not identified.
Proposed owner: councils, housing/advice providers and landlords (proposed, unverified).
Powers: needs a decision or allocation. Capacity: unverified.
Powers and capacity read from the review’s Rd and Ca anchors; no proposed owner has agreed to act (the review: “Proposed owners have not agreed to act”).
Wales created the prevention duty model (Housing (Wales) Act 2014 s.66); Scotland has new prevention duties (Housing (Scotland) Act 2025 Part 5); Northern Ireland’s Housing Executive delivers homelessness services. Not assessed.
Depends on: None recorded.
Safeguards
None specified yet.
Metric: Define and baseline the outcome described in delivery requirements before approval.
Data source: Not yet named. Baseline: Not yet established.
Measures already on the domain page
A page measure is not necessarily the review’s metric; linking the two is an editorial decision still to be made.
Outcome: Define and baseline the outcome described in delivery requirements before approval.
UK prevention evaluations and tenancy-sustainment reviews offer relevant but limited transfer evidence. Do not import Housing First effects into general renter advice.
Sources: gov.uk (not yet in the source register)
Assessment version: working-review-2026-10-06 (A74@working-review-2026-10-06).
Reviewer: Author of the review blueprint (single reviewer, not named in uk-facts-complete-plan.json). Reviewed: 6 October 2026.
Scored in the working review of 6 October 2026 on the shared ten-criterion scale (one reviewer); not independently calibrated.
An editorial screening framework by one reviewer, not a formal appraisal or business case. Proposed owners have not agreed to act.
A54Delivery RAG: AmberGate: pending
Existing action A54, assessed at the same scope.
Provisional single-reviewer desk assessment, 6 October 2026.
Flood protection is a risk-management decision. A year without a flood is not evidence of effectiveness, and one historic funding gap is not today’s national bill.
Codex — AI-assisted analytical follow-up · 8 October 2026. Proposed appraisal design; the attributed scores below are unchanged. No funding or delivery agreement is implied.
Read with the outcome evidence and sources in the full assessment. Monitoring proposals are not existing baseline measurements. A numerical benefit or cost score needs evidence for the defined increment, not just the scale of the problem.
Each criterion is scored 0 to 3 by the reviewer. “Not yet assessed” means unknown: it is never counted as zero.
Scale and severity (Sc)3 of 3 — Severe harm across a broad population
Reviewer’s reason: Problem scale judged from the linked domain evidence; not a population estimate of those helped.
Increment beyond baseline (Ad)2 of 3 — Specific material change to existing delivery
Reviewer’s reason: Separate maintenance of existing protection from long-lead new defences and assess each against local exposure. This is a provisional marginal-change judgement, to confirm against commissioned delivery.
Confidence in the proposed action (Ev)1 of 3 — Indirect, mixed, modelled or weak causal support
Reviewer’s reason: Risk maps and audits justify attention; they are not experimental proof of a uniform policy effect.
Expected incremental benefit (Bn)Not yet assessed
Reviewer’s reason: Unknown: no sufficiently supported magnitude for this exact change.
Residual harms (Hm)2 of 3 — Manageable harm with specified safeguards
Reviewer’s reason: Residual risk, false assurance and displacement of water or spending to other places.
Incremental affordability (Co)Not yet assessed
Reviewer’s reason: Unknown: the proposed increment has not been costed and matched to an approved affordable allocation in this review. Existing programme envelopes are not that allocation.
Delivery capacity (Ca)1 of 3 — Binding scarce resource
Reviewer’s reason: Use engineering and risk appraisal; low trial evidence is not grounds to leave essential protection unmanaged.
Distribution (Fa)2 of 3 — Mixed or broadly neutral with safeguards
Reviewer’s reason: Distribution assessed against the target group and the burdens described here: Residual risk, false assurance and displacement of water or spending to other places.
Meaningful first outcome (Ti)2 of 3 — More than one and up to three years
Reviewer’s reason: Timing judgement concerns the first meaningful outcome in: Asset condition; modelled protection standard; observed flood harm when events occur. It does not imply all long-term benefits arrive then.
Readiness (Rd)2 of 3 — Named commissioning/allocation/coordination step
Reviewer’s reason: List safety/maintenance gaps, cost them and appraise new schemes using expected damage and distribution. Owner: Defra, Environment Agency and local partners in England.
Normalised as 10 × weighted sum ÷ sum of weights, on a 0–30 scale. Where a criterion is not yet assessed, the range is the lowest and highest result if it were later scored 0 or 3 — not a score, a confidence interval or a rank.
Funding gate: Not passed — the cost is not yet assessed or no allocation is committed for this scope. Ignoring cost in a weighting never removes the gate.
Delivery RAG shown: AmberReview’s claim: Amber. Best the recorded evidence allows: Amber.
Review’s reason: Incremental lifetime costs and funding not established. Use engineering and risk appraisal; low trial evidence is not grounds to leave essential protection unmanaged.
Why it is not Green yet
Green needs verified scope, a verified owner with the powers, verified capacity, complete lifetime costs with credible funding, specified safeguards and monitoring with a metric, source and baseline. Amber means appraisal gaps remain; Red means a material delivery obstacle. Red does not mean unimportant.
Gate: Pending — appraisal incomplete (review label: “Pending cost, funding, scope and capacity appraisal”).
Why: Scores incomplete; Funding gate not passed (cost unknown or no credible funding).
The gate is separate from national list membership: being listed does not make an option eligible, and an eligible option need not be listed.
Lifetime costing: Partial — some lines costed, no whole-life total.
Still to cost: Incremental lifetime costs and funding not established. Use engineering and risk appraisal; low trial evidence is not grounds to leave essential protection unmanaged.
Funding status: programme route, not allocated.
Proposed owner: Defra, Environment Agency and local partners in England. (proposed, unverified).
Powers: needs a decision or allocation. Capacity: binding constraint.
Powers and capacity read from the review’s Rd and Ca anchors; no proposed owner has agreed to act (the review: “Proposed owners have not agreed to act”).
Flood risk management is devolved: Natural Resources Wales, the Scottish Environment Protection Agency and councils, and the Department for Infrastructure (Rivers) in Northern Ireland run their own programmes; not reviewed here.
Depends on: Use engineering and risk appraisal; low trial evidence is not grounds to leave essential protection unmanaged.
Safeguards
Risks and residual harms: Residual risk, false assurance and displacement of water or spending to other places.
Metric: Asset condition; modelled protection standard; observed flood harm when events occur.
Data source: Not yet named. Baseline: Not yet established.
Measures already on the domain page
A page measure is not necessarily the review’s metric; linking the two is an editorial decision still to be made.
Outcome: Asset condition; modelled protection standard; observed flood harm when events occur.
Risk maps and audits justify attention; they are not experimental proof of a uniform policy effect.
SWOT points it addresses
Assessment version: working-review-2026-10-06 (A54@working-review-2026-10-06).
Reviewer: Author of the review blueprint (single reviewer, not named in uk-facts-complete-plan.json). Reviewed: 6 October 2026.
Carried from the earlier domain review (C record): must be calibrated jointly with the G/W/E/NG/NW/NE records before any combined comparison.
Decision route: List safety/maintenance gaps, cost them and appraise new schemes using expected damage and distribution.
An earlier assessment exists on the 4 October 2026 selection table (nine H/M/L bands; superseded 7 October 2026). Its bands are kept, not converted into these scores.
An editorial screening framework by one reviewer, not a formal appraisal or business case. Proposed owners have not agreed to act.
The leading option set out as a decision someone could take: who decides, who benefits, the best evidence, cost and funding, and the main trade-off. The full research record is one click away.
Decision briefExisting programmeReviewed 2026-10-04
The thread: issue, evidence, action
An editorial proposal by UK Facts for discussion, not government policy. Records: A02 · effects E-A02-TA, E-A02-CHILDREN-TA · costs C-SAHP-ENVELOPE, C-A02-SCHEME
1.The change, in plain words
Buy or build social-rent homes? Make the choice against the cost of temporary accommodation
2.The decision requested
3.Who it is for, and what changes beyond today
Source: MHCLG, Statutory homelessness: England time series (Table TA1); Ministry of Housing, Communities and Local Government, Local authority revenue expenditure and financing England: 2024 to 2025 individual local authority data – outturn (RO4 housing services) (ENGLAND row, temporary accommodation lines)
4.How it would work
Do: Supply settled social-rent homes, by whichever route is quicker and cheaper over the horizon, and let them to households in temporary accommodation. Changing: Each letting ends a temporary placement and its recurring cost.
Households leaving temporary accommodation into settled homes
Hypothesis to testEffect record E-A02-TA
The mechanism is direct, but whether new homes are additional locally and reach these households is unevaluated in the UK.
Stability of home and school for children
Hypothesis to testEffect record E-A02-CHILDREN-TA
The US trial found fewer school moves; untested here.
Total public cost of housing the group
Hypothesis to test
The US subsidy cost more than usual care; whether buying or building here costs less than temporary accommodation is what the comparison tests.
Outcomes are kept separate and never added into one impact figure.
5.Best evidence
Where: Summary pp.3–5, 9. Affiliation is provenance, not proof of quality.
The Affordable Homes Programme since 2015
Where: Summary, paragraph 14. Affiliation is provenance, not proof of quality.
6.Alternatives, counter-evidence and who loses
Source: National Audit Office, The Affordable Homes Programme since 2015 (Summary, paragraph 14)
| Option | Who is reached | Evidence | Likely outcome and timing | Cost and funding | Main trade-off |
|---|---|---|---|---|---|
| The proposalBuy, build or lease — chosen against temporary-accommodation cost | Named households in temporary accommodation | US RCT for the tenancy mechanism; no UK evaluation | Months (buy/lease) to years (build) | Programme envelope; scheme not costed | Competes with other buyers or for builders |
| Current policyCurrent policy: supply grant by bidding | Future social-rent tenants generally | NAO: delivery below plan | Homes over the decade; who is housed not tracked | £39bn envelope | No link to temporary accommodation |
| AlternativeLong leases of private homes | Households in temporary accommodation | Not evaluated here | Fast | Revenue cost | Adds no supply |
The options compared, including current policy
The proposal
Buy, build or lease — chosen against temporary-accommodation cost
Current policy
Current policy: supply grant by bidding
Alternative
Long leases of private homes
7.What other countries or the devolved nations show
Country lesson · 12 US communities, Enrolment 2010–2012; 3-year results 2016
Evidence: Experimental or quasi-experimental evaluationPartial match: some conditions differ
Not a UK forecast: the effect above was measured in that place and population. Source: US Department of Housing and Urban Development, Office of Policy Development and Research, Family Options Study: 3-Year Impacts of Housing and Services Interventions for Homeless Families (summary report) (Summary pp.3–5, 9). Reviewed 2026-10-04.
Country lesson · Five Canadian cities, 2009–2013
Evidence: Experimental or quasi-experimental evaluationWeak match: context only, not a model to copy
Not a UK forecast: the effect above was measured in that place and population. Source: Mental Health Commission of Canada, National At Home/Chez Soi Final Report (Executive summary pp.5–7; Chapter 4). Reviewed 2026-10-04.
8.What delivery needs first
9.What it would cost
How the cost is built up: For each route: purchase or build + repairs + financing + management + maintenance + voids + recurring support, less rent, over the declared horizon — set against the current temporary-accommodation pathway for the same households. Capital and recurring costs shown separately.
| Component | Unit and quantity | Unit cost or amount | Type, price year, period | Status |
|---|---|---|---|---|
| Social and Affordable Homes ProgrammeEngland | programme; quantity to be set from need and capacity | £39bn in total, 2026–27 to 2035–36, price basis not stated by the source (ledger C-SAHP-ENVELOPE) | capital; price year not stated; 2026–27 to 2035–36 | Current quoted costA possible route, not a confirmed budget for this package. |
| Purchase or build, repairs, financing, management, maintenance, voids and support for a named schemeOne authority’s scheme | per home; quantity to be set from need and capacity | Not yet costed (ledger C-A02-SCHEME) | mixed; price year not stated; Declared horizon | Not yet established |
| Whole-life comparison and evaluationOne authority | per comparison; quantity to be set from need and capacity | Not yet established | one-off revenue; price year not stated; Before the first award | Not yet established |
Social and Affordable Homes Programme
England
£39bn in total, 2026–27 to 2035–36, price basis not stated by the source (ledger C-SAHP-ENVELOPE)
capital; price year not stated; 2026–27 to 2035–36; Current quoted cost
A possible route, not a confirmed budget for this package.
Purchase or build, repairs, financing, management, maintenance, voids and support for a named scheme
One authority’s scheme
Not yet costed (ledger C-A02-SCHEME)
mixed; price year not stated; Declared horizon; Not yet established
Whole-life comparison and evaluation
One authority
Not yet established per comparison
one-off revenue; price year not stated; Before the first award; Not yet established
10.Who pays, and what is missing
11.First milestone and time to a useful result
First whole-life comparison published for a named authority; first award linked to temporary-accommodation lettings. (Owner: Council with Homes England or the GLA. Proposed by UK Facts, not an official deadline.)
Time to first useful result: Acquisition lettings within months of an award; new-build lettings in years.
What could delay it: Suitable homes are available at a price within grant rates. Build costs do not rise faster than grant.
12.How we would know
What is not yet known, and how to find out
Sources last checked 4 October 2026 · Owner: Evidence editor (James Harris) · Next check: MHCLG statutory homelessness in England: April to June 2026 (temporary accommodation) (29 October 2026, provisional) or the first trigger: Social and Affordable Homes Programme prospectus, bidding round or allocations.
First, the prerequisite
Publish the blocker, owner and infrastructure cost for priority sites
Owner: MHCLG with local planning authorities
No date: the timing depends on the steps before it.
Then, the decision
Award programme grant to named social-rent schemes
Owner: Homes England and the GLA
Bidding opened February 2026; first strategic-partner allocations 25 August 2026, most of the programme still to allocate — source
Then, delivery
Build or acquire, then let to households in temporary accommodation
Owner: Housing associations and councils
No date: the timing depends on the steps before it.
Finally, the measured outcome
Fewer households in temporary accommodation; more net additional homes
Owner: MHCLG statistics
No date: the timing depends on the steps before it.
Then, delivery
Early legal and money advice for renters served notice or in arrears, in named councils with comparisons
Owner: Councils with MHCLG and the Ministry of Justice
No date: the timing depends on the steps before it.
Cost, committed funding and the remaining gap for the same scope and years. A programme envelope is not an award to a project; a proposal is not committed money. No total is shown because these costs are on different bases or periods and cannot be added.
Cost and funding ledger
Social and Affordable Homes Programme 2026–2036 (programme envelope)
A02 · capital · published programme envelope
Grant, borrowing, rent, maintenance and infrastructure for a named scheme
A02 · capital · not costed
Planning staff, site infrastructure and financing for priority sites
A01 · capital · not costed
Flood and coastal erosion risk management programme 2026–27 to 2028–29 (programme envelope)
A54 · capital · published programme envelope
“Not yet costed” means no defensible cost has been found — not that the action is free. Lifetime benefits, benefit-cost ratios and forecast savings are never shown here as money available to spend.
| Action | Outcome and area | Effect | Compared with | Evidence |
|---|---|---|---|---|
| Turn permissions into homes people can live in | Net additional homes Housing | Direction plausible; size not established | — | modelled; limited confidence; EnglandThe OBR’s 170,000 extra homes by 2029–30 is its judgement of the 2024 planning reforms already in place, not of this site-by-site package, whose marginal effect has not been estimated. |
| Use social-housing funding to reduce temporary accommodation | Households leaving temporary accommodation Housing | Direction plausible; size not established | — | plausible spillover; limited confidence; EnglandWhether new social-rent homes are additional locally and reach households in temporary accommodation has not been evaluated. |
| Use social-housing funding to reduce temporary accommodation | Income after housing costs of households moving into a social-rent home Poverty and inequality | Direction plausible; size not established | — | plausible spillover; limited confidence; EnglandNo source we checked estimates how much poverty after housing costs falls when households move into new social-rent homes; rent levels, benefit offsets and who is housed all change the answer. |
| Use social-housing funding to reduce temporary accommodation | Stability of home and school for children leaving temporary accommodation Education and children | Direction plausible; size not established | — | plausible spillover; limited confidence; EnglandOur sources count the children affected but none evaluates the effect of rehousing on attendance, attainment or health, so this is a link to test, not a finding. |
The outcome measures to watch. A baseline is where we start, not a target; where there is no official target we say so.
properties · England
Target: none — no official target for properties at risk; the flood programme counts properties better protected.
Source: Environment Agency, National assessment of flood and coastal erosion risk in England 2024 (Executive summary, printed p.3). Next release: next national assessment update (no date published) (check the release calendar).
households · England
Target: none — there is no official target for temporary accommodation.
Source: MHCLG, Statutory homelessness: England time series (Table TA1). Next release: quarterly (check the release calendar).
homes a year · England
Official target: 1.5 million homes this Parliament (about 300,000 a year): a Plan for Change milestone set by the Starmer government and restated by the Burnham government on 25 August 2026.
Source: MHCLG, Housing supply: net additional dwellings, England (Live Table 120). Next release: annual; last released 20 November 2025 (check the release calendar).
times annual earnings · England
Target: none — affordability has no official target.
Source: Office for National Statistics, Housing affordability in England and Wales: 2025 (Table 1c). Next release: annual (March) (check the release calendar).
% of prevention duties ended · England
Target: none — no target for this measure; the national prevention target uses a different metric (44.3% prevented or relieved).
Source: Ministry of Housing, Communities and Local Government, Statutory homelessness in England: January to March 2026 (Sections 4 and 5). Next release: April–June 2026 due 29 October 2026 (provisional) (check the release calendar).
What each option would be judged on, and the latest value of the measures already on this page. A measure moving is not proof that an option caused it.
Homes built, not just permitted
Judged on: Net additional completed and occupied homes, affordability and displacement.
Data source: not yet named; baseline: not yet established.
National plan: Growth and prosperity list
Settled homes for families in temporary accommodation
Judged on: Sustained settled housing, repeat homelessness and household wellbeing.
Data source: not yet named; baseline: not yet established.
National plan: Equality and opportunity list
Prevent avoidable loss of rented homes
Judged on: Define and baseline the outcome described in delivery requirements before approval.
Data source: not yet named; baseline: not yet established.
National plan: Related option, assessed separately
Protect flood-defence maintenance and appraise schemes by risk
Judged on: Asset condition; modelled protection standard; observed flood harm when events occur.
Data source: not yet named; baseline: not yet established.
National plan: Resilience and sustainability appraisal queue
“Full text checked” means we read the report itself; “relevant passages” means the sections behind each figure; “summary or abstract only” means we could not read the full study, so no number from it is published here without another source.
Options from earlier work on this page that are not on the shortlist. They remain valid choices; their evidence is shown as before.
| Option | Resources | Time | Evidence | Outcome to watch |
|---|---|---|---|---|
| Construction workforce and skills | Training places, assessors and employer time; an ageing workforce to replace. | Several years before newly trained workers add capacity. | limited | Completions rise without a matching rise in build costs. |
| Support and security for private renters | Benefit spending for higher allowances; council enforcement officers. | Allowance changes act within a year; tenancy reforms take longer to show. | limited | Homelessness from the end of a private tenancy, and households in temporary accommodation. |
Plan reviewed 2026-10-07. How we judge evidence.
Every figure printed in the image matches today’s record, and its primary sources have been checked.
Homes still cost nearly eight years of full-time pay.
In England a median home cost 7.6× median gross full-time annual earnings in 2025, against 9.1× at the 2021 peak and 4.2× in 2000. A price-to-earnings ratio, not a deposit or mortgage measure. Three separate observations, not a continuous line.
A ratio of price to pay — not a mortgage payment or deposit measure. Local ratios vary far more widely.
Homes still cost nearly eight years of full-time pay. In England a median home cost 7.6× median gross full-time annual earnings in 2025, against 9.1× at the 2021 peak and 4.2× in 2000. A price-to-earnings ratio, not a deposit or mortgage measure. Three separate observations, not a continuous line.
| Measure | Value | Period | Geography | Type | Source |
|---|---|---|---|---|---|
| House price to workplace-based earnings ratio, England, 1997 | 3.5× | 1997 | England | observed count | Office for National Statistics, Housing affordability in England and Wales |
| House price to workplace-based earnings ratio, England, 2000 | 4.2× | 2000 | England | observed count | Office for National Statistics, Housing affordability in England and Wales |
| House price to workplace-based earnings ratio, England, 2021 | 9.1× | 2021 | England | observed count | Office for National Statistics, Housing affordability in England and Wales |
| House price to workplace-based earnings ratio, England, 2025 | 7.6× | 2025 | England | observed count | Office for National Statistics, Housing affordability in England and Wales |
Image description: Housing infographic: a typical home in England cost 7.6 times full-time annual pay in 2025, against 3.5 in 1997 and 9.1 in 2021.
A landscape card for sharing this finding. Post it with the page link — an uploaded image does not link back by itself.
All visual summaries, their source records and their publication state are listed on Shareable visuals.
Affordability depends on pay as well as prices; real pay has risen only a few per cent since 2007.
Property is most households’ main wealth, so rising prices widened the gap between owners and those who cannot build a deposit.
Ownership and wealth are measured by different surveys from the affordability ratio.
Planning applications, approvals, starts and completions, side by side.
A high approval rate does not show planning is no constraint.
Housing support in Universal Credit has been frozen while rents rose.
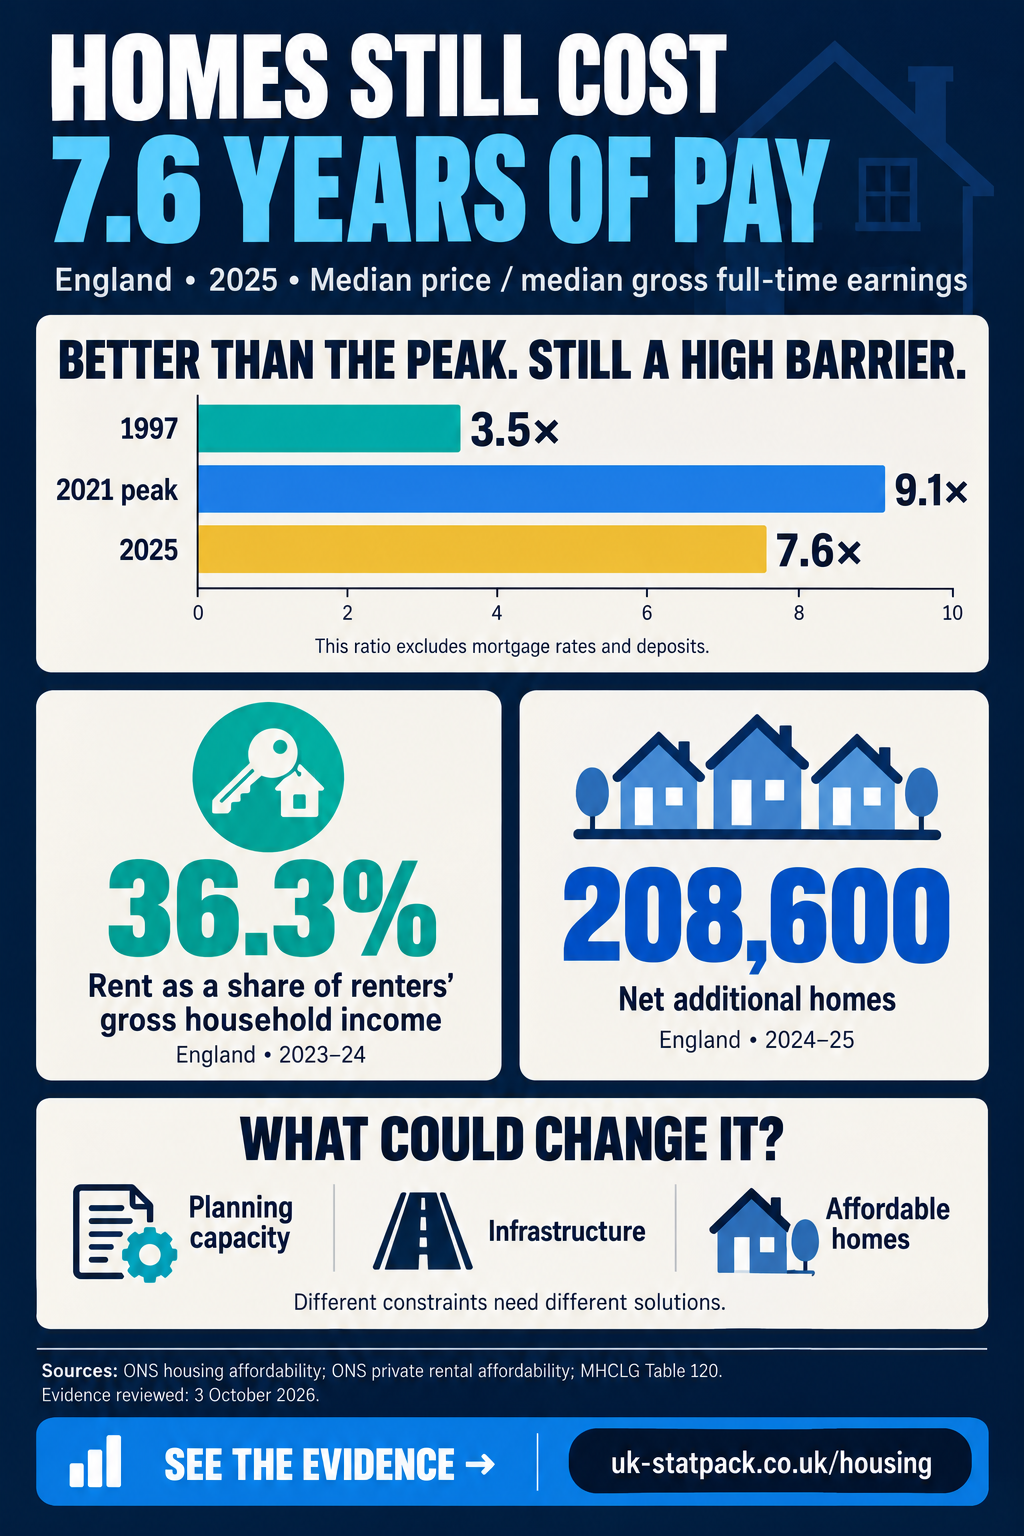
04 · Social housing
Lower rents need homes people can actually access
Social rent offers a different route to a settled home. Increasing that supply matters alongside helping buyers.
Council rents: lower costs, limited access
Councils and housing associations both provide social housing. “Council” describes the landlord; Social Rent and Affordable Rent describe how the rent is set. Access depends on eligibility, allocation and homes becoming available.
Council rent: source and definition
Pages 11 and 14; England general-needs Social Rent, excluding service charges. 2024 derived from £107.88 less published £8.13 change. Stock revisions were not applied to earlier rents. These stock-wide net rents differ from the new-letting geometric means below; they are not a matched-home comparison.
Regulator of Social Housing · 2024–25 stock and rentsCouncil Social Rent · England
£107.88 / week
Average general-needs net rent
31 March 2025 · service charges extra
£99.75 in 2024 → £107.88
Social-rent additions remain below the 1990s
12,267 added in 2024–25. These are gross additions: sales and demolitions also affect the stock.
Sources, definitions and data
Live Table 1000, revised 25 June 2026. Social Rent excludes Affordable Rent and shared ownership. Some London grant reporting cannot separate social rent from London Affordable Rent; see source notes. Financial years are plotted at their starting year.
MHCLG · Live Table 1000Two rent labels, different costs
England · average weekly rent for new social-sector lettings, 2024–25
Social Rent£113 / week
Affordable Rent£160 / week
“Affordable Rent” is a policy category, not a promise that every household can afford it. These rents describe new lettings, not every existing tenancy.
Sources, definitions and data
MHCLG CORE lettings statistics, geometric means across new lets (general needs and supported housing), section 7.2. Differences also reflect where homes are and their size; this is not a matched-property comparison.
Social housing lettings · rents