Innovation · United Kingdom · R&D 2024 · equity finance 2025

£79bn on research. Spending is only the beginning.

R&D performed in the UK cost £79.4bn in 2024, 2.71% of GDP. Spending is an input, not a measured return. Follow the evidence from research to spin-outs, business investment and adoption; those outcomes cannot all be attributed to R&D spending.

Priority: Help more research and existing technology reach wider use, where a specific barrier can be shown and fixed. What would change it →

Evidence last reviewed 3 October 2026

Overview

The short version

Three key measures

Who feels this most?

Research is concentrated in a few places, and new technology reaches big firms first. Both shape who gains from innovation.

The evidence

From research spending to wider adoption and productive use

Research inputs

How does UK research spending compare?

UK R&D spending is slightly above the OECD average on the comparable measure

Gross domestic expenditure on research and development (GERD) as a percentage of GDP, 2023: the UK, the OECD total, the EU and ten other economies.

Selected OECD and partner economies · 2023
2023OECD total 2.70%
  • South Korea4.94%
  • Sweden3.64%
  • Japan3.44%
  • United States3.42%
  • Germany3.13%
  • United Kingdom2.75%
  • OECD total2.70%
  • China2.58%
  • France2.18%
  • European Union (27)2.15%
  • Canada1.94%
  • Italy1.37%
The UK spent 2.75% of GDP on R&D in 2023 on OECD’s measure, against an OECD total of 2.70% — close to the norm, well below the leaders (South Korea 4.9%, the US 3.4%) and well above Italy and Canada. The comparison only became this favourable after ONS improved its business survey in 2022; it reflects better measurement, not a sudden jump in spending. Spending is an input: it says nothing on its own about whether research becomes products or productivity.

Selected OECD and partner economies · 2023 · Official estimates; the latest year is provisional for several countries, including the UK; the US value is flagged by OECD as using a different definition

Sources, definitions and data — UK R&D spending is slightly above the OECD average on the comparable measure
Geography:
Selected OECD and partner economies — All R&D performed in each country: business, higher education, government and non-profit
Measure:
% of GDP
Period:
2023
Status:
Official estimates; the latest year is provisional for several countries, including the UK; the US value is flagged by OECD as using a different definition
Calculation:
As published by OECD. The OECD total and EU are OECD aggregates, not averages of the countries shown.
Compare with:
OECD total 2.70%
Not included / breaks:
UK figures from 2018 onwards reflect ONS’s 2022 survey redevelopment, which raised measured business R&D sharply. Older UK headlines of about 1.7% of GDP were on the previous basis and are not comparable with this chart. This is whole-economy GERD, not business R&D (BERD) or government R&D budgets.

Source: OECD, Main Science and Technology Indicators (March 2026 edition), GERD as a percentage of GDP (released March 2026). Chart INNOV-01.

View the data as a table
Economy2023, % of GDP
South Korea4.94
Sweden3.64
Japan3.44
United States3.42
Germany3.13
United Kingdom2.75
OECD total2.70
China2.58
France2.18
European Union (27)2.15
Canada1.94
Italy1.37

Of the £79.4bn of R&D performed in the UK in 2024, businesses did £55.6bn, universities £17.9bn, government £4.7bn and non-profits £1.2bn. Until 2022 the official figure was about 1.7% of GDP; ONS then rebuilt its business survey and found far more business R&D than it had been counting. Any target or comparison still built on the old figure — including “doubling to the OECD average” — no longer applies.

Is business R&D growing?

After inflation, business R&D is no higher than in 2021

Business enterprise R&D expenditure performed in the UK, £bn at constant 2024 prices (ONS R&D deflator), 2018–2024.

United Kingdom · 2018 to 2024

1996–2026 displayed window · observations only. Shading marks years outside the displayed record.

£bn, 2024 pricesNo observations shown£0bn£20bn£40bn£60bn£80bn200020102020£55.6bn
In cash terms business R&D has risen every year, but once rising costs are taken out it has been flat since 2021: £55.6bn in 2024 against £55.8bn then. A cash headline alone overstates how much more research is being done. Growth before 2021 rests on back-cast estimates that ONS does not accredit.

United Kingdom · 2018 to 2024 · ONS accredits only the 2022–2024 estimates; earlier years are back-cast after the survey redevelopment

Sources, definitions and data — After inflation, business R&D is no higher than in 2021
Geography:
United Kingdom — R&D performed by businesses
Measure:
£bn, constant 2024 prices
Period:
2018 to 2024
Status:
ONS accredits only the 2022–2024 estimates; earlier years are back-cast after the survey redevelopment
Calculation:
As published by ONS in constant prices; shown in £bn.
Compare with:
2021 peak, £55.8bn
Not included / breaks:
Constant-price figures use a new R&D-specific deflator and are not comparable with constant-price BERD published before it. In current prices, business R&D rose every year, from £41.0bn in 2018 to £55.6bn in 2024.

Source: ONS, Business enterprise research and development, UK: 2024, berd2024 accredited official statistics workbook. Chart INNOV-02.

View the data as a table
Year£bn, 2024 prices
201849.8
201950.7
202052.7
202155.8
202254.4
202354.4
202455.6

What happens after the research?

There is no single measure of whether research turns into growth, and no data that follow the same ideas from laboratory to product to profit. Instead, each step has its own evidence, with its own population and year. Read the panels as a sequence of questions, not a funnel: the numbers cannot be chained into conversion rates.

INNOV-05 · What happens after the research?

Four steps, four different measures

  1. 1. Do universities create companies? (September 2025)

    1,695

    Active university spin-outs, out of 2,307 on the first national register. They raised £2.9bn of venture capital in 2024. Survival and turnover are not yet published on a consistent basis.

    UKRI / Research England, Building on the UK’s first spin-out register
  2. 2. Can growing firms raise money? (2025)

    £12.3bn

    Equity raised by UK smaller businesses in 2,002 deals, 4% less than in 2024. £5.4bn — 44% — went to AI companies. Commercial deal data analysed by the British Business Bank.

    British Business Bank, Small Business Equity Tracker 2026
  3. 3. Do new firms survive? (born 2019)

    38.4%

    Of UK businesses born in 2019, 38.4% were still trading five years later. All new businesses, not only innovative ones. 317,000 were born and 280,000 closed in 2024.

    ONS, Business demography, UK: 2024
  4. 4. Do firms grow fast? (2024)

    14,330

    High-growth businesses — employment growing over 20% a year for three years — 4.9% of firms with ten or more employees, the highest share since 2018.

    ONS, Business demography, UK: 2024

Each step has a story worth knowing — spin-outs are increasingly counted, growth equity is concentrated in AI, and most new firms close within five years — but none of these measures is a measure of value created. Patents, spin-outs, investment, valuations, turnover and output are different things; this page does not add or convert between them.

Where does growth finance come from? Scale-up finance and ownership.

Skills, energy and regulation

Research-intensive firms share the constraints of every investor, often more sharply. They need specialist staff — skills and apprenticeships cover the training pipeline in England. Manufacturing and computing need power at a competitive price and a connection date — industrial electricity prices are well above Germany’s and France’s. And new products need consent from regulators, and new sites from planners.

There is little comparable evidence on how much each of these holds back innovation specifically. This page does not rank them; the growth page shows how they bind together.

Who feels this most?

Regional clusters

Where does business research happen?

Three regions perform 59% of UK business R&D

Business enterprise R&D expenditure by region and nation of the UK, £bn, 2024.

UK nations and English regions (ITL1) · 2024
2024
  • London£13.3bn
  • East of England£10.3bn
  • South East£9.2bn
  • West Midlands£4.9bn
  • North West£4.7bn
  • South West£4.1bn
  • Scotland£2.8bn
  • East Midlands£2.2bn
  • Yorkshire and the Humber£1.8bn
  • Wales£0.9bn
  • Northern Ireland£0.8bn
  • North East£0.7bn
London, the East of England (which includes Cambridge) and the South East (which includes Oxford) together account for about 59% of business R&D. The North East, Northern Ireland and Wales each perform under £1bn. Concentration is not itself a problem — research clusters gain from being close together — but it means most regions see little direct benefit from research spending unless ideas spread to firms elsewhere.

UK nations and English regions (ITL1) · 2024 · Official statistics

Sources, definitions and data — Three regions perform 59% of UK business R&D
Geography:
UK nations and English regions (ITL1) — R&D performed by businesses, by location of the research
Measure:
£bn, current prices
Period:
2024
Status:
Official statistics
Calculation:
As published by ONS (Table 4a), shown in £bn. Total R&D (GERD) is suppressed for four areas, so business R&D is used for all twelve.
Compare with:
Other regions and nations
Not included / breaks:
Totals, not per head or as a share of regional output — ONS does not publish those, and larger regions spend more partly because they are larger. Shares are of the sum of the twelve areas shown.

Source: ONS, Gross domestic expenditure on research and development, UK: 2024, gerd2024.xlsx, Tables 2a, 4a and 5 (released 7 August 2026). Chart INNOV-03.

View the data as a table
Area£m
London13,325
East of England10,301
South East9,228
West Midlands4,862
North West4,678
South West4,060
Scotland2,837
East Midlands2,183
Yorkshire and the Humber1,761
Wales884
Northern Ireland758
North East738

The twelve areas sum to £55.6bn, the UK business R&D total.

What successful diffusion would look like

Most of the productivity gain from innovation comes not from inventing but from ordinary firms adopting what already works. Success would show up as smaller firms catching up with large ones in technology use, and — over years — as faster growth in output per hour. Reported AI use is rising fast (11.9% to 34.9% of firms with ten or more staff since September 2023), but use is not the same as productive use, and the main government adoption programme evaluated so far found no clear productivity effect. What happened to productivity and pay?

Are businesses adopting new technology?

About half of large firms use AI; just over a quarter of the smallest do

Percentage of UK trading businesses using at least one AI technology, by number of employees, June 2026.

United Kingdom · June 2026
June 2026
  • 0–9 employees28.2%
  • 10–49 employees33.1%
  • 50–99 employees42.7%
  • 100–249 employees45.1%
  • 250 or more employees48.6%
Reported AI use among businesses with ten or more employees rose from 11.9% in September 2023 to 34.9% in June 2026. Larger firms are well ahead. Diffusion — existing firms taking up proven technology — is where most productivity gains from innovation are usually found, and it is the stage the UK measures least well.

United Kingdom · June 2026 · Official statistics in development; self-reported survey

Sources, definitions and data — About half of large firms use AI; just over a quarter of the smallest do
Geography:
United Kingdom — Trading businesses responding to the Business Insights and Conditions Survey
Measure:
% of businesses
Period:
June 2026
Status:
Official statistics in development; self-reported survey
Calculation:
UK Facts calculation from the ONS wave 159 dataset: 100% minus businesses answering “does not use” or “not sure”. This reproduces the figures ONS publishes (34.9% for 10+ employees; 28% for 0–9; 49% for 250+).
Compare with:
11.9% of businesses with 10+ employees in September 2023
Not included / breaks:
Self-reported use, which may range from a chatbot trial to production systems. Use is not the same as productive use, and the survey cannot show whether AI raised output.

Source: ONS, Artificial intelligence in UK businesses: 2023 to 2026, Business Insights and Conditions Survey, wave 159 (15–28 June 2026) (released 20 July 2026). Chart INNOV-04.

View the data as a table
Business size% using AI
0–9 employees28.2
10–49 employees33.1
50–99 employees42.7
100–249 employees45.1
250 or more employees48.6
Shareable visual summary

Visual summary

Image current

Every figure printed in the image matches today’s record, and its primary sources have been checked.

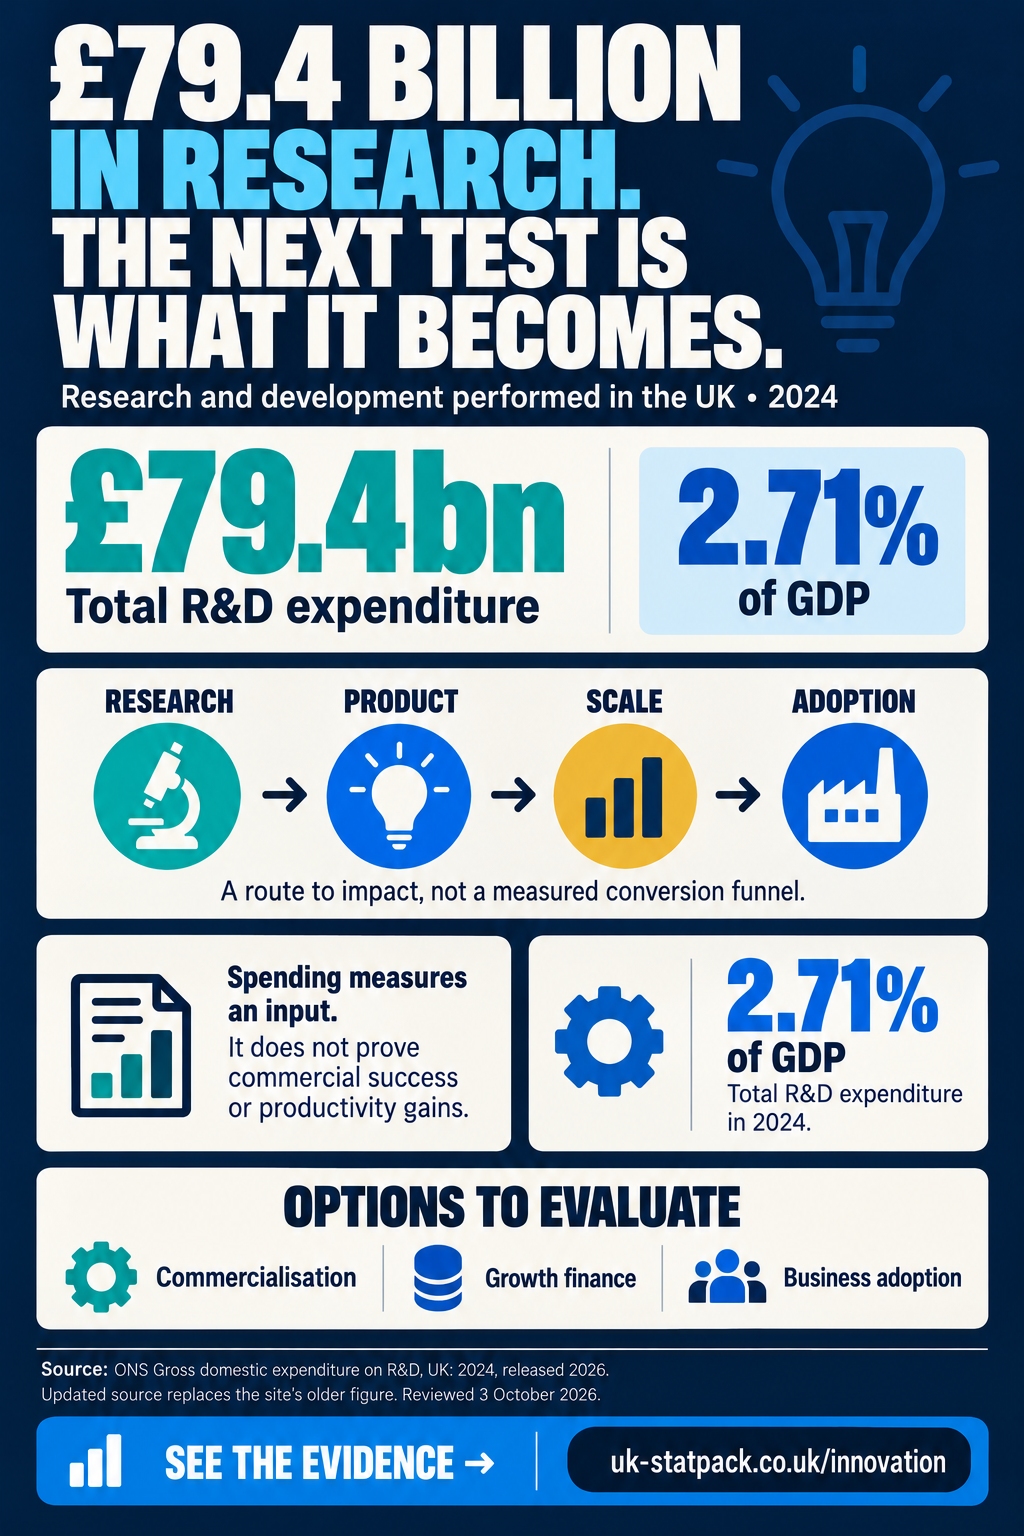
£79bn on research. Spending is only the beginning.

R&D performed in the UK cost £79.4bn in 2024, 2.71% of GDP. Spending is an input, not a measured return. Follow the evidence from research to spin-outs, business investment and adoption; those outcomes cannot all be attributed to R&D spending. R&D is an input: total R&D performed in the UK, not government spending alone, and not a measure of return.

  • £79.4bnR&D performed in the UK, 2024
  • 2.71%of GDP

Research to adoption (conceptual, not a measured funnel)

  1. Step 1ResearchIdeas and discoveries
  2. Step 2ProductTurned into something usable
  3. Step 3ScaleFirms grow in the UK
  4. Step 4AdoptionUsed across the economy
UK, 2024. Source: ONS, Gross domestic expenditure on research and development.
Download image (PNG, 1024 by 1536 pixels)

£79bn on research. Spending is only the beginning.

Innovation infographic: UK R&D expenditure was £79.4bn in 2024, 2.71% of GDP.
Text and data version

£79bn on research. Spending is only the beginning. R&D performed in the UK cost £79.4bn in 2024, 2.71% of GDP. Spending is an input, not a measured return. Follow the evidence from research to spin-outs, business investment and adoption; those outcomes cannot all be attributed to R&D spending. R&D is an input: total R&D performed in the UK, not government spending alone, and not a measure of return.

Records behind this visual summary
MeasureValuePeriodGeographyTypeSource
UK gross domestic expenditure on R&D£79.4bn2024United Kingdomsurvey estimateONS, Gross domestic expenditure on R&D, UK: 2024
R&D as a share of GDP2.71%2024United Kingdomderived calculationONS, Gross domestic expenditure on R&D, UK: 2024

Image description: Innovation infographic: UK R&D expenditure was £79.4bn in 2024, 2.71% of GDP.

All visual summaries, their source records and their publication state are listed on Shareable visuals.

Go deeper

Evidence → choices → outcomes

What could improve it?

More useful research adopted in products, firms and public services — judged by adoption and outcomes, not R&D spending alone.

These options link to their national assessment, including funding, delivery constraints and remaining uncertainties.

  • Assessed option · provisional

    Turn research into products and adoption

    7/10 criteria scored

    Coverage of the appraisal, not an impact score.

    Delivery: Amber

    Whole-life costs incomplete

    Evidence and delivery constraints

    The artifact offers weak support for its spinout/procurement package. Smart Grants evaluation is relevant to a different instrument and cannot validate the whole bundle.

    Separate spinout terms, procurement trials, grants and firm adoption; define market failure, beneficiaries and comparator.

This domain in the UK SWOT →UK National Action Plan →

How we assessed these options

What would it take to improve this?

What would move the needle?

The outcome we want: More useful research adopted in products, firms and public services — judged by adoption and outcomes, not R&D spending alone.

The main constraint: Research is plentiful, but turning it into adopted products depends on deal terms, follow-on finance and a first customer — constraints held by universities, investors and public buyers, and measured poorly because spending and spin-out counts say little about returns.

Constraint type: market structure, coordination, evidence.

The options on the table

What is funded now, and the changes assessed against it — the current baseline and the alternatives, before the position today and the actions.

Provisional single-reviewer assessments from the 6 October 2026 review; not approved business cases, and not government policy.

  • Turn research into products and adoptionDelivery RAG: Amber

    Funded now
    Not yet stated in the record.
    The change assessed
    Not yet defined.

    Range if completed: 11.0–20.0 out of 30 (equal weights; not yet assessed: increment beyond baseline (Ad), expected incremental benefit (Bn), incremental affordability (Co))

  • Existing-firm management and technology adoptionDelivery RAG: Amber

    Funded now
    Funded baseline: Help to Grow: Management (participants pay £750) continues; Made Smarter Adoption runs in all nine English regions (£16m in 2025–26); the Business Growth Service is the national brand. A comparison-based test of diagnostic and adoption support with a productivity outcome is a UK Facts proposal, not government policy.
    The change assessed
    Test targeted diagnostic advice and adoption support for existing firms, with a comparator and a defined productivity outcome.

    Range if completed: 15.0–21.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))

Alternatives already on record: 23 options listed under the points in the position today (14 without an action record), and 4 earlier options under other options compared. They have not been scored in the review.

The position today

  • What we can build on (2)
  • What is holding us back (3)Spending and spin-out counts do not show economic or social returns: the flagship technology-adoption scheme found no statistically significant productivity effect, and the spin-out review offers recommendations rather than measured outcomes.
  • What could improve things (1)Standard deal terms and proof-of-concept money for spin-outs, plus public bodies acting as tested first customers, could move more research into use.
  • What could make it worse (1)

Which quadrant a point sits in is our analytical judgement, not a statistical category. Each point says whether it is a measured fact, our synthesis or a risk.

What we can build on Strengths

What is holding us back Weaknesses

What could improve things Opportunities

What could make it worse Threats

The actions worth examining

Our shortlist for this page. Research quality, policy status, cost and funding are judged separately; none of these is government policy unless its status says so.Our shortlist. None is government policy unless its status says so.

  1. Make university spin-out deals clearer and quicker — programme funding exists; project allocation unconfirmed
  2. Use public buying to test useful innovations — not yet costed / funding not identified
  3. Test management and adoption support for existing firms against a comparison — not yet costed / funding not identified
  • Action 1A41Policy status: announced proposal

    Make university spin-out deals clearer and quicker

    Standard, market-norm deal terms and proof-of-concept funding shorten negotiations and make spin-outs easier to finance.

    Assessment (draft, 6 October review)

    • A broad priority including this action (GRP-02): Turn research into products and adoption

      Delivery RAG: AmberGate: pending

      Range if completed: 11.0–20.0 out of 30 (equal weights; not yet assessed: increment beyond baseline (Ad), expected incremental benefit (Bn), incremental affordability (Co))

      National plan: Growth and prosperity list

    Who decides:
    Universities, DSIT and Research England/UKRI, with founders and investors (UK)
    Evidence:
    Expert or audit recommendation. An independent review’s recommendations, not causal evidence that faster deals produce more successful firms.
    Expected effect:
    Direction plausible; size not established.
    Cost and funding

    £20m in total, Announced November 2023; delivery years not stated in the response., price basis not stated by the source; 1 further cost line, some not yet costed

    Funding: Programme funding exists; project allocation unconfirmed

    Why it is shortlisted here: University research is a core strength; slow, inconsistent deal terms are a specific, fixable step between research and firms.

    What it takes
    The problem

    Founders and investors report that slow, inconsistent deal terms delay spin-out formation and fundraising.

    Who is affected, and where

    University researchers, founders and investors; users of resulting products. Territory: UK. Research funding is UK-wide through UKRI, but higher-education funding (including knowledge-exchange funds) is devolved; the £280m HEIF figure is for England.

    Policy status

    Announced by government, not yet in place. The Sunak government accepted all the 2023 review’s recommendations in November 2023, with a £20m proof-of-concept research programme and work on deal-terms guidance; no restatement by the Starmer or Burnham governments was checked for this review. How far universities have adopted the terms was not checked here; UK Facts proposes baselining deal time and following firms over years.

    The evidence
    What the research found:
    The review recommended market-norm terms (for example 10–25% university equity in life sciences, lower in software), more proof-of-concept funding and better data. The government accepted all recommendations and committed £20m to proof of concept.
    Evaluated on:
    UK university spin-outs and their founders (review engagement and founder survey); United Kingdom, 2023
    Our recommendation (separate from the research):
    Publish deal time and terms by university, and follow spin-outs’ finance, survival and adoption over several years.
    Strongest counter-evidence:
    More, faster spin-outs may not mean better ones; universities’ income from equity funds research; the reviewers are a vice-chancellor and an investor.
    Cost and funding

    Cost completeness: Partly costed. Funding: Programme funding exists; project allocation unconfirmed.

    • Cross-disciplinary proof-of-concept research programme (announced) (recurring spending; paid by central government): £20m in total, Announced November 2023; delivery years not stated in the response., price basis not stated by the source. A programme allocation, not awards to particular projects; whether it has been fully spent was not checked.
    • Technology-transfer capacity, legal work and data on deal terms (administration; paid by central government, private investors): Not yet costed. Recyclable investment, expected losses and grant spending must be separated; private co-investment is conditional.
    • £20m proof-of-concept research programme: £20m — not committed (programme envelope, not a project award). Does not cover technology-transfer process changes (C-A41-PROCESS).
    Who pays:
    UKRI/DSIT (proof-of-concept funding); universities (technology-transfer staff and legal costs); investors (equity, conditional on deals).
    Financing proposed:
    The £20m proof-of-concept programme; private co-investment is conditional, not public finance.
    Gap remaining:
    Unknown: process changes and technology-transfer capacity are not costed.
    What delivery needs
    Skills:
    Technology-transfer and legal staff.
    Operational capacity:
    Data on deal timelines.
    Infrastructure:
    None.
    Permissions:
    University governance approval of new terms.
    Law:
    None.
    Public consent:
    Universities accepting lower equity stakes.
    First step and stages

    First step: Baseline deal time and failure points, and record which review recommendations each university has adopted. (owner: DSIT with Research England)

    1. Baseline deal time and terms — DSIT, Research England (proposed stage, not an official timetable)
    2. Pilot standard terms and shared technology transfer — Universities (proposed stage, not an official timetable)
    3. Follow firm outcomes over several years — UKRI; independent evaluator (proposed stage, not an official timetable)

    Depends on: Spin-out register data; Follow-on finance availability

    Trade-offs
    Who gains and who loses:
    Founders and investors gain; universities may receive smaller equity shares.
    What else the money or effort could do:
    Proof-of-concept money not spent on other research.
    Strongest counterargument:
    Commercial outcomes depend mainly on finance and markets, not deal terms.
    Risks:
    Quantity over quality; loss of university income.
    How we would judge it
    Baseline:
    1,695 active spin-outs (September 2025, UKRI register).
    Leading indicator:
    Median deal completion time.
    Outcome:
    Follow-on finance, survival, adoption and public-interest outcomes.
    Continue, adapt or stop:
    Review if deal times do not fall after standard terms are adopted.
    Sources

    Source published November 2023 (review and response); evidence reviewed 2026-10-04. Reconsider if: Government reports on university adoption of recommended terms; New spin-out register data.

  • Action 2A42Policy status: site-editorial action

    Use public buying to test useful innovations

    Run bounded, competitive trials against a defined service problem with a minimum acceptable result, an adoption route and independent evaluation — and publish failures.

    Assessment (draft, 6 October review)

    • A broad priority including this action (GRP-02): Turn research into products and adoption

      Delivery RAG: AmberGate: pending

      Range if completed: 11.0–20.0 out of 30 (equal weights; not yet assessed: increment beyond baseline (Ad), expected incremental benefit (Bn), incremental affordability (Co))

      National plan: Growth and prosperity list

    Who decides:
    A named commissioning body, with suppliers and independent evaluators (UK)
    Evidence:
    Expert or audit recommendation. A policy-design rationale backed by procurement research and evaluation guidance; each product needs its own evaluation.
    Expected effect:
    Direction plausible; size not established.
    Cost and funding

    Not yet costed

    Funding: Not yet costed / funding not identified

    Why it is shortlisted here: A first public customer can prove a product, but only with an evaluation and a route to adoption.

    What it takes
    The problem

    Public bodies rarely act as early customers, and pilots often end without a route to adoption or an honest evaluation.

    Who is affected, and where

    Public-service users; innovative suppliers, including small firms. Territory: UK. The Procurement Act 2023 does not cover most Scottish devolved bodies; pilots there need Scottish rules.

    Policy status

    UK Facts proposal. The Procurement Act 2023 (in force February 2025) allows more flexible procedures; using them for evaluated innovation trials with adoption routes is a UK Facts proposal. A national allocation now exists: on 31 August 2026 the Burnham government launched the first competitions under a £100m Sovereign AI R&D Procurement Scheme. It covers AI products only and is not an evaluated-trial programme.

    The evidence
    What the research found:
    The Institute for Government recommends outcome-led procurement that starts from the problem, not a specified solution. The Magenta Book says evaluation should be planned before rollout so that comparison groups and baselines exist.
    Evaluated on:
    UK public procurement (research); evaluation practice (guidance); United Kingdom
    Our recommendation (separate from the research):
    State the service problem and minimum acceptable result before choosing technology; trial, evaluate, then adopt or stop.
    Strongest counter-evidence:
    Pilots often never scale; vendors can capture buyers; novelty can be bought without operational value.
    Cost and funding

    Cost completeness: Not yet costed. Funding: Not yet costed / funding not identified.

    • Trial, integration, staff training, security, maintenance and exit (administration; paid by central government, councils, NHS): Not yet costed. Not just licence fees; scaling needs a separate budget decision after evidence.
    Who pays:
    The commissioning body (trial, integration, training, security, maintenance and exit); suppliers (bid costs).
    Financing proposed:
    A named innovation or procurement allocation for the trial; scaling needs a separate budget decision after evidence.
    Gap remaining:
    Unknown.
    What delivery needs
    Skills:
    Commercial staff able to write outcome specifications; evaluators.
    Operational capacity:
    Service teams to host trials.
    Infrastructure:
    Integration with existing systems.
    Permissions:
    Data protection and security approval.
    Law:
    Procurement Act 2023 procedures.
    Public consent:
    Service users and staff.
    First step and stages

    First step: State the service problem and minimum acceptable result before selecting any technology. (owner: The commissioning body)

    1. Define problem and success threshold — Commissioning body (proposed stage, not an official timetable)
    2. Competitive trial with independent evaluation — Commissioning body; evaluator (proposed stage, not an official timetable)
    3. Adopt or stop, and publish results — Commissioning body (proposed stage, not an official timetable)

    Depends on: A23: contract-management capacity; A44: the same evaluation discipline for AI tools

    Trade-offs
    Who gains and who loses:
    Users gain if trials succeed; small suppliers gain access; failed trials cost money.
    What else the money or effort could do:
    Staff and budget used on trials instead of proven services.
    Strongest counterargument:
    Public bodies are risk-averse for good reasons; trials can disrupt services.
    Risks:
    Pilots without buyers; vendor lock-in.
    How we would judge it
    Baseline:
    No national measure of evaluated innovation trials was found.
    Leading indicator:
    Trials with a published success threshold and evaluation plan.
    Outcome:
    Service benefit, whole-life cost and adoption after trial.
    Continue, adapt or stop:
    Stop trials that miss the stated minimum result; publish the outcome either way.
    Earlier option on this page

    This card replaces the option “Government as an early customer” (legislated). Its evidence: The Procurement Act 2023 took effect in February 2025; there is no evaluation yet of its effect on innovative suppliers. Procurement Act 2023

    Sources

    Source published September 2025 (IfG); May 2026 (Magenta Book); evidence reviewed 2026-10-04. Reconsider if: Evaluation of Procurement Act flexible procedures; A named innovation-procurement fund.

    Also on: Public procurement — one shared record, so its cost is counted once.

  • Action 3A69Policy status: external proposal

    Test management and adoption support for existing firms against a comparison

    Hands-on diagnostic advice followed by support to adopt specific management practices or technology, offered to defined firms and compared with similar firms that did not receive it, shows whether productivity rises before support is scaled.

    Assessment (draft, 6 October review)

    Who decides:
    Department for Business, Innovation, Science and Trade (formerly DBT) with mayoral strategic authorities and Growth Hubs (England)
    Evidence:
    Experimental or quasi-experimental evaluation. A randomised trial abroad found large productivity gains from intensive management consulting; UK evaluations of the national schemes found no significant productivity effect; reviews find business advice more often raises turnover than productivity.
    Expected effect:
    Direction plausible; size not established.
    Cost and funding

    Not yet costed

    Funding: Not yet costed / funding not identified

    Why it is shortlisted here: The existing-firm adoption option (related to research into adoption, NG4): national management and adoption schemes have shown no productivity effect, so the bounded change is a comparison-based test with a productivity outcome. It builds on the adoption option card, which stays.

    Builds on the option Help for existing firms to adopt technology compared below.

    What it takes
    The problem

    The UK’s flagship management and technology-adoption schemes have not shown productivity gains: Help to Grow: Management and Made Smarter Adoption found no statistically significant effect on productivity.

    Who is affected, and where

    Established small and medium-sized firms in England with 10 or more employees in sectors with low management scores, in mayoral areas running the Business Growth Service. Territory: England. Business support is devolved in Scotland, Wales and Northern Ireland; Help to Grow: Management runs UK-wide. Not assessed outside England.

    Policy status

    Proposed by researchers or others, not government policy. Funded baseline: Help to Grow: Management (participants pay £750) continues; Made Smarter Adoption runs in all nine English regions (£16m in 2025–26); the Business Growth Service is the national brand. A comparison-based test of diagnostic and adoption support with a productivity outcome is a UK Facts proposal, not government policy.

    The evidence
    What the research found:
    Free intensive consulting raised productivity by about 11% in the Indian trial; Help to Grow: Management found “no statistically significant evidence of business growth or improved firm-level productivity”; 14 of 23 business-advice evaluations found a positive effect on at least one outcome, more often turnover than productivity.
    Evaluated on:
    Large textile firms in India (trial); 9,847 SME leaders on Help to Grow: Management; 23 business-advice evaluations; India (trial); United Kingdom
    Transfer to this case:
    The trial covered large firms in one industry abroad with intensive consulting; UK schemes are lighter-touch.
    Our recommendation (separate from the research):
    Fund diagnostic and adoption support only with a comparison group and a defined productivity outcome (turnover per worker from business records), and scale only what shows a gain.
    Strongest counter-evidence:
    The UK schemes evaluated so far show no productivity effect, so a new test may also find none.
    Cost and funding

    Cost completeness: Not yet costed. Funding: Not yet costed / funding not identified.

      Who pays:
      BIST and mayoral authorities (integrated settlements from 2026–27); participating firms in part.
      Financing proposed:
      Within existing business-support budgets if redesigned; not identified.
      Gap remaining:
      Unknown: Help to Grow: Management’s annual budget, the Business Growth Service budget and Made Smarter funding from 2026–27 are not published.
      What delivery needs
      Skills:
      Experienced advisers.
      Operational capacity:
      Growth Hub delivery.
      Infrastructure:
      Access to business records for evaluation (Business Structure Database).
      Permissions:
      Data-sharing for evaluation.
      Law:
      None.
      Public consent:
      Voluntary firm participation.
      First step and stages

      First step: BIST and two mayoral authorities define the target firms, the diagnostic and adoption offer and a randomised or phased comparison, with turnover per worker as the outcome. (owner: BIST with mayoral authorities)

      1. Define offer and comparison — BIST and mayoral authorities (proposed stage, not an official timetable)
      2. Deliver to the first cohort — Growth Hubs (proposed stage, not an official timetable)
      3. Measure turnover per worker against comparison firms — BIST (evaluation) (proposed stage, not an official timetable)

      Depends on: Business record linkage for evaluation

      Trade-offs
      Who gains and who loses:
      Aimed at established firms with weak management practices, outside London where scores and productivity are lower.
      What else the money or effort could do:
      Advisory budgets could fund other business support or skills.
      Strongest counterargument:
      Light-touch programmes have not worked; intensive support may be too expensive to scale.
      Risks:
      Selecting firms that would have improved anyway; measuring turnover rather than productivity.
      How we would judge it
      Baseline:
      Mean management practices score 0.55 in 2023 (firms with 10 or more employees, ONS).
      Leading indicator:
      Firms completing diagnostic and adoption steps.
      Outcome:
      Turnover per worker against comparison firms.
      Continue, adapt or stop:
      Scale only if productivity rises relative to comparison firms.
      Sources

      Source published 11 June 2026 (Help to Grow: Management evaluation); 13 May 2024 (ONS); 2011 (Bloom et al.); evidence reviewed 2026-10-07. Reconsider if: Help to Grow: Management enrolment statistics (autumn 2026); Any new ONS management practices release.

    How the options are assessed

    One shared record per option — the same one the national plan reads. Delivery RAG, gate and list membership are separate judgements.

    • Turn research into products and adoption — Amber delivery RAG; gate pending
    • Existing-firm management and technology adoption — Amber delivery RAG; gate pending

    Provisional single-reviewer assessments from the 6 October 2026 review; not approved business cases, and not government policy.

    • GRP-02Delivery RAG: AmberGate: pending

      Turn research into products and adoption

      A broad priority grouping A41, A42; its scores are its own, never an average of its members.

      Provisional single-reviewer assessment; not an approved business case.

      Who and where
      Population not yet defined. Jurisdiction: not defined.
      Result so far
      Range if completed: 11.0–20.0 out of 30 (equal weights; not yet assessed: increment beyond baseline (Ad), expected incremental benefit (Bn), incremental affordability (Co))
      Funded now (baseline)
      Funded baseline not yet stated
      The change assessed (marginal)
      Marginal change not yet defined
      What the evidence supports—and the next decision

      Grant evaluation cannot establish the effect of a combined research, procurement and adoption package.

      Codex — AI-assisted analytical follow-up · 8 October 2026. Proposed appraisal design; the attributed scores below are unchanged. No funding or delivery agreement is implied.

      Define the change
      Separate research grants, first-customer procurement and adoption support. Define eligible firms and what they already receive.
      Test whether it works
      Additional private research and commercial sales, then productivity and survival against comparison firms; distinguish displacement from new activity.
      Establish the cost
      Public grants and administration, procurement liabilities and private contributions. Do not add turnover, wages and productivity benefits if they describe the same gain.
      Protect against harm
      Use transparent selection, conflict controls and publication of failed projects as well as successes.

      Read with the outcome evidence and sources in the full assessment. Monitoring proposals are not existing baseline measurements. A numerical benefit or cost score needs evidence for the defined increment, not just the scale of the problem.

      Full assessment of Turn research into products and adoption: ten criteria, scenarios, delivery, costs and monitoring
      The ten criteria (0–3)

      Each criterion is scored 0 to 3 by the reviewer. “Not yet assessed” means unknown: it is never counted as zero.

      1. Scale and severity (Sc)2 of 3 — Serious harm to a defined group or widespread moderate harm

        Reviewer’s reason: Provisional problem-importance judgement from linked site pages; not the scale of achievable benefit.

      2. Increment beyond baseline (Ad)Not yet assessed

        Reviewer’s reason: Separate spinout terms, procurement trials, grants and firm adoption; define market failure, beneficiaries and comparator. A missing rating requires a defined marginal change.

      3. Confidence in the proposed action (Ev)1 of 3 — Indirect, mixed, modelled or weak causal support

        Reviewer’s reason: The artifact offers weak support for its spinout/procurement package. Smart Grants evaluation is relevant to a different instrument and cannot validate the whole bundle.

      4. Expected incremental benefit (Bn)Not yet assessed

        Reviewer’s reason: Unknown unless a reasonably defined target-population benefit can be judged; no bonus merely for spanning domains.

      5. Residual harms (Hm)2 of 3 — Manageable harm with specified safeguards

        Reviewer’s reason: Deadweight subsidies; concentrated gains; failed investments.

      6. Incremental affordability (Co)Not yet assessed

        Reviewer’s reason: Administration, grants, procurement risk and private match; estimate displacement and additional private investment.

      7. Delivery capacity (Ca)2 of 3 — Stretched but plausibly obtainable

        Reviewer’s reason: Separate spinout terms, procurement trials, grants and firm adoption; define market failure, beneficiaries and comparator.

      8. Distribution (Fa)1 of 3 — Material disadvantage to vulnerable groups

        Reviewer’s reason: Provisional distribution judgement for the stated target; verify who pays, who gains and excluded groups.

      9. Meaningful first outcome (Ti)1 of 3 — More than three but less than ten years

        Reviewer’s reason: First meaningful outcome, not announcement: Additional adoption, productivity and commercial outcomes versus comparable firms.

      10. Readiness (Rd)2 of 3 — Named commissioning/allocation/coordination step

        Reviewer’s reason: Business/research departments, UKRI and public buyers; Split and appraise alternatives

      Four weightings

      Normalised as 10 × weighted sum ÷ sum of weights, on a 0–30 scale. Where a criterion is not yet assessed, the range is the lowest and highest result if it were later scored 0 or 3 — not a score, a confidence interval or a rank.

      • Equal weights: Range if completed: 11.0–20.0 out of 30. Not yet assessed: increment beyond baseline (Ad), expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
      • Evidence doubled: Range if completed: 10.9–19.1 out of 30. Not yet assessed: increment beyond baseline (Ad), expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
      • Scale doubled: Range if completed: 11.8–20.0 out of 30. Not yet assessed: increment beyond baseline (Ad), expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
      • Cost ignored (the funding gate still applies): Range if completed: 12.2–18.9 out of 30. Not yet assessed: increment beyond baseline (Ad), expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.

      Funding gate: Not passed — the cost is not yet assessed or no allocation is committed for this scope. Ignoring cost in a weighting never removes the gate.

      Delivery RAG and gate

      Delivery RAG shown: AmberReview’s claim: Amber. Best the recorded evidence allows: Amber.

      Review’s reason: Administration, grants, procurement risk and private match; estimate displacement and additional private investment.

      Why it is not Green yet

      • Scope (population, place and increment) not verified against the delivery baseline.
      • No verified owner with the powers in place.
      • Delivery capacity not verified.
      • Lifetime incremental costs not complete.
      • No credible funding (a committed allocation for the scope).
      • Safeguards not specified.
      • Monitoring lacks a metric, a data source or a baseline.

      Green needs verified scope, a verified owner with the powers, verified capacity, complete lifetime costs with credible funding, specified safeguards and monitoring with a metric, source and baseline. Amber means appraisal gaps remain; Red means a material delivery obstacle. Red does not mean unimportant.

      Gate: Pending — appraisal incomplete (review label: “Pending: incomplete appraisal”).

      Why: Scores incomplete; Funding gate not passed (cost unknown or no credible funding).

      The gate is separate from national list membership: being listed does not make an option eligible, and an eligible option need not be listed.

      Cost and funding

      Lifetime costing: Not established. Review: “Full incremental costing not established in reviewed material”.

      Still to cost: Administration, grants, procurement risk and private match; estimate displacement and additional private investment.

      Funding status: not established in review.

      Owner, powers and capacity

      Proposed owner: Business/research departments, UKRI and public buyers (proposed, unverified).

      Powers: needs a decision or allocation. Capacity: unverified.

      Powers and capacity read from the review’s Rd and Ca anchors; no proposed owner has agreed to act (the review: “Proposed owners have not agreed to act”).

      England:
      not assessed
      Scotland:
      not assessed
      Wales:
      not assessed
      Northern Ireland:
      not assessed

      Not defined in the review.

      Dependencies, safeguards and risks

      Depends on: None recorded.

      Safeguards

      None specified yet.

      Risks and residual harms: Deadweight subsidies; concentrated gains; failed investments.

      Monitoring and measured results

      Metric: Additional adoption, productivity and commercial outcomes versus comparable firms.

      Data source: Not yet named. Baseline: Not yet established.

      Measures already on the domain page

      A page measure is not necessarily the review’s metric; linking the two is an editorial decision still to be made.

      Evidence for the outcome
      Review record

      Assessment version: working-review-2026-10-06 (GRP-02@working-review-2026-10-06).

      Reviewer: Author of the review blueprint (single reviewer, not named in uk-facts-complete-plan.json). Reviewed: 6 October 2026.

      Scored in the working review of 6 October 2026 on the shared ten-criterion scale (one reviewer); not independently calibrated.

      First 90 days (review): Produce a signed scope and current-delivery baseline; Separate spinout terms, procurement trials, grants and firm adoption; define market failure, beneficiaries and comparator. Obtain incremental costs and an accountable decision before expansion.

      Decision route: Split and appraise alternatives

      An editorial screening framework by one reviewer, not a formal appraisal or business case. Proposed owners have not agreed to act.

    • A69Delivery RAG: AmberGate: pending

      Existing-firm management and technology adoption

      Existing action A69, assessed at the same scope.

      Not stated in the review record; treated as a provisional single-reviewer assessment, not an approved business case.

      Who and where
      Established small and medium-sized firms in England with 10 or more employees in sectors with low management scores, in mayoral areas running the Business Growth Service. (from the action record) Jurisdiction: England.
      Result so far
      Range if completed: 15.0–21.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))
      Funded now (baseline)
      Funded baseline: Help to Grow: Management (participants pay £750) continues; Made Smarter Adoption runs in all nine English regions (£16m in 2025–26); the Business Growth Service is the national brand. A comparison-based test of diagnostic and adoption support with a productivity outcome is a UK Facts proposal, not government policy. (from the action record)
      The change assessed (marginal)
      Test targeted diagnostic advice and adoption support for existing firms, with a comparator and a defined productivity outcome. (from the 6 October review)
      What the evidence supports—and the next decision

      Business advice evidence is mixed and foreign management trials do not provide a UK-wide productivity forecast.

      Codex — AI-assisted analytical follow-up · 8 October 2026. Proposed appraisal design; the attributed scores below are unchanged. No funding or delivery agreement is implied.

      Define the change
      Test targeted diagnostics and adoption support for a defined firm group against the existing support offer.
      Test whether it works
      Additional productivity, survival and adoption with comparison firms; separate turnover growth from productivity and examine spillovers.
      Establish the cost
      Advisers, grants, firm time, technology and evaluation, net of fees; test whether firms would have invested anyway.
      Protect against harm
      Use transparent eligibility and publish failures; avoid subsidising adoption already planned.

      Read with the outcome evidence and sources in the full assessment. Monitoring proposals are not existing baseline measurements. A numerical benefit or cost score needs evidence for the defined increment, not just the scale of the problem.

      Full assessment of Existing-firm management and technology adoption: ten criteria, scenarios, delivery, costs and monitoring
      The ten criteria (0–3)

      Each criterion is scored 0 to 3 by the reviewer. “Not yet assessed” means unknown: it is never counted as zero.

      1. Scale and severity (Sc)2 of 3 — Serious harm to a defined group or widespread moderate harm

      2. Increment beyond baseline (Ad)2 of 3 — Specific material change to existing delivery

      3. Confidence in the proposed action (Ev)1 of 3 — Indirect, mixed, modelled or weak causal support

      4. Expected incremental benefit (Bn)Not yet assessed

      5. Residual harms (Hm)2 of 3 — Manageable harm with specified safeguards

      6. Incremental affordability (Co)Not yet assessed

      7. Delivery capacity (Ca)2 of 3 — Stretched but plausibly obtainable

      8. Distribution (Fa)2 of 3 — Mixed or broadly neutral with safeguards

      9. Meaningful first outcome (Ti)2 of 3 — More than one and up to three years

      10. Readiness (Rd)2 of 3 — Named commissioning/allocation/coordination step

      Four weightings

      Normalised as 10 × weighted sum ÷ sum of weights, on a 0–30 scale. Where a criterion is not yet assessed, the range is the lowest and highest result if it were later scored 0 or 3 — not a score, a confidence interval or a rank.

      • Equal weights: Range if completed: 15.0–21.0 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
      • Evidence doubled: Range if completed: 14.5–20.0 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
      • Scale doubled: Range if completed: 15.5–20.9 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
      • Cost ignored (the funding gate still applies): Range if completed: 16.7–20.0 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.

      Funding gate: Not passed — the cost is not yet assessed or no allocation is committed for this scope. Ignoring cost in a weighting never removes the gate.

      Delivery RAG and gate

      Delivery RAG shown: AmberReview’s claim: Amber. Best the recorded evidence allows: Amber.

      Review’s reason: Define firm eligibility and existing offer; cost advisers, adoption support and evaluation, including firm contributions. Measure additional productivity, survival and displacement. Proposed owners: business department, local business-support bodies and delivery partners.

      Why it is not Green yet

      • Scope (population, place and increment) not verified against the delivery baseline.
      • No verified owner with the powers in place.
      • Delivery capacity not verified.
      • Lifetime incremental costs not complete.
      • No credible funding (a committed allocation for the scope).
      • Safeguards not specified.
      • Monitoring lacks a metric, a data source or a baseline.

      Green needs verified scope, a verified owner with the powers, verified capacity, complete lifetime costs with credible funding, specified safeguards and monitoring with a metric, source and baseline. Amber means appraisal gaps remain; Red means a material delivery obstacle. Red does not mean unimportant.

      Gate: Pending — appraisal incomplete (review label: “Pending baseline verification, incremental costing and funding; not a rollout approval”).

      Why: Scores incomplete; Funding gate not passed (cost unknown or no credible funding).

      The gate is separate from national list membership: being listed does not make an option eligible, and an eligible option need not be listed.

      Cost and funding

      Lifetime costing: Not established. Review: “Not fully costed in this review”.

      Still to cost: Define firm eligibility and existing offer; cost advisers, adoption support and evaluation, including firm contributions. Measure additional productivity, survival and displacement. Proposed owners: business department, local business-support bodies and delivery partners.

      Funding status: not identified.

      Owner, powers and capacity

      Proposed owner: business department, local business-support bodies and delivery partners (proposed, unverified).

      Powers: needs a decision or allocation. Capacity: unverified.

      Powers and capacity read from the review’s Rd and Ca anchors; no proposed owner has agreed to act (the review: “Proposed owners have not agreed to act”).

      England:
      Department for Business, Innovation, Science and Trade (formerly DBT) with mayoral strategic authorities and Growth Hubs (action record)
      Scotland:
      not assessed
      Wales:
      not assessed
      Northern Ireland:
      not assessed

      Business support is devolved in Scotland, Wales and Northern Ireland; Help to Grow: Management runs UK-wide. Not assessed outside England.

      Dependencies, safeguards and risks

      Depends on: None recorded.

      Safeguards

      None specified yet.

      Monitoring and measured results

      Metric: Define and baseline the outcome described in delivery requirements before approval.

      Data source: Not yet named. Baseline: Not yet established.

      Measures already on the domain page

      A page measure is not necessarily the review’s metric; linking the two is an editorial decision still to be made.

      Evidence for the outcome
      Review record

      Assessment version: working-review-2026-10-06 (A69@working-review-2026-10-06).

      Reviewer: Author of the review blueprint (single reviewer, not named in uk-facts-complete-plan.json). Reviewed: 6 October 2026.

      Scored in the working review of 6 October 2026 on the shared ten-criterion scale (one reviewer); not independently calibrated.

      An editorial screening framework by one reviewer, not a formal appraisal or business case. Proposed owners have not agreed to act.

    Decision brief

    • Award proof-of-concept money by scored competition, and follow every applicant to see what it changes

    The leading option set out as a decision someone could take: who decides, who benefits, the best evidence, cost and funding, and the main trade-off. The full research record is one click away.

    Decision briefExisting programmeReviewed 2026-10-04

    Award proof-of-concept money by scored competition, and follow every applicant to see what it changes

    Decision required
    DSIT and Research England allocate the announced £20m proof-of-concept programme by a scored, ranked competition, publish the ranking rules, and track funded and narrowly unfunded projects for spin-out formation, follow-on finance, survival and adoption — with stage-gates to stop projects that miss their milestones.
    Who and where
    University researchers and prospective founders across the UK. Applies in: UK.
    Accountable body
    Department for Science, Innovation and Technology (with Research England)
    Intervention
    Fund early proof-of-concept work by scored competition with staged milestones.
    Best evidence, and where it applies
    In the US, small competitive proof-of-concept awards (SBIR Phase I) roughly doubled the chance that firms near the funding cut-off raised venture capital; larger follow-on awards showed no consistent extra effect.Studied in: 7,436 small high-tech firms applying to two DOE offices (working-paper sample) (Awards 1983–2013).How closely the comparison transfers to this decision: United States (Department of Energy) — partial.
    Extra cost of this change
    Capital: none identified in the brief.Recurring: Technology-transfer capacity, legal work and deal-term data — Not yet costed; Long-run outcome tracking and evaluation — not yet established.One-off or mixed: Proof-of-concept research programme (announced) — £20m in total, Announced November 2023; delivery years not stated in the response., price basis not stated by the source.
    Funding
    Not funded yet: a possible funding route exists, but nothing is allocated to this change.Committed to this change: none.Possible source, not an award: £20m proof-of-concept research programme (£20m).Unfunded: Allocations to universities were not checked; process changes and evaluation are not costed.
    Savings and wider benefits
    Not yet specified: no cashable saving or avoided cost has been costed for this change. Expected outcomes are listed one by one in the research appendix and are never added together or counted as money available.
    First 90-day step
    DSIT publishes the scoring rules, the ranked outcome of the next allocation round and the outcome measures to be trackedThe proposed first milestone; a 90-day date is not yet specified. Owner: DSIT with Research England. Proposed by UK Facts, not an official deadline.
    Twelve-month milestone
    Not yet specified.Time to a first useful result: Deal formation and first finance within two to three years; survival and adoption after five or more.
    Outcome, and when to scale or stop
    Measure: Projects passing their stage-gates; median deal completion time.Scale if: Funded projects raise follow-on finance or reach adoption more often than near-miss applicants.Stop if: Individual projects that miss stage-gate milestones stop; the programme is reconsidered if funded and near-miss applicants show no difference after five years.
    Main trade-off
    A scored competition with a tracked comparison group delays nothing but means telling some good applicants no, and results take years to appear.

    An editorial proposal by UK Facts for discussion, not government policy. Records: A41 · costs C-A41-POC, C-A41-PROCESS

    Research appendix: study design, effect sizes and limits, alternatives, full costing, international comparisons and how we would know

    1.The change, in plain words

    Award proof-of-concept money by scored competition, and follow every applicant to see what it changes

    2.The decision requested

    Decision
    Run the £20m proof-of-concept programme as a ranked competition with published scoring, staged milestones and a follow-up of funded and near-miss applicants; publish deal-time data for resulting spin-outs.
    Accountable institution
    Department for Science, Innovation and Technology (with Research England)
    Geography
    UK
    Powers
    Existing DSIT and UKRI grant-making powers; no legislation.
    Delivery partners
    Research England / UKRI; Universities and technology-transfer offices; Investors (follow-on finance, conditional); Independent evaluator

    3.Who it is for, and what changes beyond today

    Target population
    University researchers and prospective founders across the UK.
    Eligibility
    Applicants to the cross-disciplinary proof-of-concept programme announced in the government response to the spin-out review.
    Scale
    The £20m programme as announced; how it has been allocated was not checked in this review.
    Baseline
    1,695 active spin-outs on the UKRI register (September 2025). The 2023 spin-out review recommended market-norm deal terms, more proof-of-concept funding and better data; the government accepted all recommendations and committed £20m to proof of concept.

    Source: UKRI / Research England, Building on the UK’s first spin-out register (Register summary); DSIT and HM Treasury, Government response: Independent review of university spin-outs (Executive summary (PDF p.5))

    Change beyond existing law or funding
    The money is announced. The change is in how it is allocated and followed up: a published ranking that creates a natural comparison, stage-gates with stop rules, and outcome tracking beyond the grant period.

    4.How it would work

    Do: Fund early proof-of-concept work by scored competition with staged milestones Changing: so that promising research reaches the evidence investors need, and weak projects stop early

    • More funded projects raise follow-on finance than near-miss applicants

      Hypothesis to test

      US evidence suggests early awards change finance at the margin; no UK estimate exists.

    • Spin-outs survive and their products are adopted (including by public services)

      Hypothesis to test

      Attribution to the programme is weak beyond the first stages; reported separately from finance outcomes.

    Outcomes are kept separate and never added into one impact figure.

    5.Best evidence

    • Financing Innovation: Evidence from R&D Grants (American Economic Review 107(4): 1136–64)

      Author or institution:
      Sabrina T. Howell (economist; study of US Department of Energy data)
      Published:
      April 2017
      Evaluation period:
      Awards 1983–2013
      Design:
      Regression discontinuity around the award ranking cut-off
      Sample or population:
      7,436 small high-tech firms applying to two DOE offices (working-paper sample)
      Effect and uncertainty:
      A Phase I (proof-of-concept) award approximately doubles the probability of later venture capital, with large positive effects on patents and revenue; Phase II awards show no consistent extra effect on venture capital.
      Limits:
      US energy technology firms, not university researchers; effects apply near the cut-off; read in abstract.

      Where: Abstract. Affiliation is provenance, not proof of quality.

    • Independent review of university spin-out companies (with government response and Annex D founder survey)

      Author or institution:
      Independent review (a vice-chancellor and an investor) for the government
      Published:
      November 2023
      Evaluation period:
      Not an evaluation
      Design:
      Expert review with founder survey
      Sample or population:
      UK university spin-outs
      Effect and uncertainty:
      Recommends market-norm deal terms, more proof-of-concept funding and better data.
      Limits:
      Expert recommendations; the reviewers have interests on both sides of deal negotiations.

      Where: Review PDF pp.6–7. Affiliation is provenance, not proof of quality.

    6.Alternatives, counter-evidence and who loses

    Closest feasible alternative
    Allocate proof-of-concept money through universities’ own internal processes, as most institutional funds do.
    Strongest counter-evidence
    More and faster spin-outs may not mean better ones; universities’ equity income funds research; the UK’s own SBRI evaluation found headcount gains but no significant effect on turnover or productivity.

    Source: UK Research and Innovation (by Steer), An Evaluation of the Small Business Research Initiative (SBRI) (Executive summary); Irene Tracey / Andrew Williamson, published by DSIT and HM Treasury, Independent review of university spin-out companies (with government response and Annex D founder survey) (Review PDF pp.6–7)

    Distributional effects
    Researchers in institutions with strong technology-transfer offices gain most; regions with less investor presence may gain less unless scoring accounts for it.
    Main downside
    Outcomes that matter (survival, adoption, productivity) take five to ten years to observe.

    The options compared, including current policy

    • The proposal

      Scored, ranked proof-of-concept competition with stage-gates and near-miss tracking

      Who is reached
      University researchers and founders
      Evidence
      US SBIR regression-discontinuity study; UK spin-out review
      Likely outcome and timing
      Finance effects in two to three years; adoption later
      Cost and funding
      Within the £20m programme; evaluation not costed
      Main trade-off
      Slow evidence; good applicants refused
    • Current policy

      Current policy: £20m programme announced; allocation and outcomes not reported here

      Who is reached
      Successful applicants
      Evidence
      Government response, November 2023
      Likely outcome and timing
      Unknown
      Cost and funding
      £20m programme envelope
      Main trade-off
      No way to tell what the money changed
    • Alternative

      Public buyer route: fund trials against a named service problem

      Who is reached
      Firms with near-ready products; public services
      Evidence
      UK SBRI evaluation (headcount gains, no turnover effect)
      Likely outcome and timing
      Faster adoption if a buyer is committed
      Cost and funding
      Commissioning body’s budget
      Main trade-off
      Few public buyers commit to adoption

    7.What other countries or the devolved nations show

    Country lesson · United States (Department of Energy), Awards 1983–2013; study published 2017

    Small proof-of-concept grants in the US SBIR programme

    Evidence: Experimental or quasi-experimental evaluationPartial match: some conditions differ

    What was changed
    Competitive Small Business Innovation Research Phase I awards (small proof-of-concept grants), followed by larger Phase II awards for successful firms.
    Study design and population
    Regression discontinuity around the ranking cut-off for awards Small high-tech firms applying to two DOE offices (7,436 firms in the working-paper sample)
    Measured outcome there
    A Phase I award approximately doubled the probability of later venture capital and had large positive effects on patents and revenue; Phase II had no consistently positive effect on venture capital.
    Cost status
    Over $884m (2012 dollars) of awards in the sample; cost per additional financed firm not estimated.
    What failed or remains uncertain
    Effects are for firms near the cut-off in energy technologies; larger awards showed no extra finance effect; selection by programme managers matters.
    Why the UK differs
    UK proof-of-concept money is mostly for university research before a company exists; UK venture markets are smaller; SBIR has a set-aside of agency R&D budgets that the UK does not have.
    First change required here
    Allocate the proof-of-concept programme by scored competition and record the ranking, so firms just above and below the cut-off can be compared later.

    Not a UK forecast: the effect above was measured in that place and population. Source: American Economic Association, Financing Innovation: Evidence from R&D Grants (American Economic Review 107(4): 1136–64) (Abstract). Reviewed 2026-10-04.

    8.What delivery needs first

    • data — Applicant scores and outcomes linked to Companies House and investment data. (Requirement; owner: DSIT and UKRI)
    • staff — Technology-transfer and legal staff in universities to complete deals quickly. (Scarce resource shared with other priorities; owner: Universities)
    • dependency — Private investors willing to follow on; public funding cannot guarantee it. (Requirement; owner: Investors)

    9.What it would cost

    How the cost is built up: Grants (the £20m programme) + competition administration + technology-transfer capacity + outcome tracking. Recyclable investment, expected losses and grant spending are kept separate; private co-investment is not public money.

    • Proof-of-concept research programme (announced)

      UK universities and prospective founders

      £20m in total, Announced November 2023; delivery years not stated in the response., price basis not stated by the source (ledger C-A41-POC)

      one-off revenue; price year not stated; As announced in 2023; Historic cost

    • Technology-transfer capacity, legal work and deal-term data

      UK universities

      Not yet costed (ledger C-A41-PROCESS)

      recurring; price year not stated; Ongoing; Not yet established

    • Long-run outcome tracking and evaluation

      Funded and near-miss applicants

      Not yet established one evaluation

      recurring; price year not stated; Five years from award; Not yet established

    10.Who pays, and what is missing

    Programme envelope (a possible route, not an award)
    £20m proof-of-concept research programme: £20m
    Allocation committed to this change
    None
    Remaining gap
    Allocations to universities were not checked; process changes and evaluation are not costed.
    Proposed financing
    The announced £20m proof-of-concept programme for the grants; evaluation and tracking from DSIT/UKRI administration budgets.
    Responsible payer
    central government
    Budget displaced
    Other UKRI research and innovation spending.

    11.First milestone and time to a useful result

    DSIT publishes the scoring rules, the ranked outcome of the next allocation round and the outcome measures to be tracked (Owner: DSIT with Research England. Proposed by UK Facts, not an official deadline.)

    Time to first useful result: Deal formation and first finance within two to three years; survival and adoption after five or more.

    What could delay it: The programme has already been fully allocated without ranking data Investment markets weaken

    12.How we would know

    Baseline
    1,695 active spin-outs (September 2025); deal times not yet measured nationally.
    Comparison
    Applicants just above and just below the funding cut-off.
    Leading indicator
    Projects passing their stage-gates; median deal completion time.
    Follow-up
    Follow-on finance at two and five years; survival; adoption and public-service use.
    Continue if
    Funded projects raise follow-on finance or reach adoption more often than near-miss applicants.
    Adapt if
    Finance rises but adoption does not: add a public-buyer route (the A42 brief on /public-procurement).
    Stop if
    Individual projects that miss stage-gate milestones stop; the programme is reconsidered if funded and near-miss applicants show no difference after five years.
    Thresholds
    Not yet set: Stage-gate milestones are set per project; programme thresholds need a power calculation from the number of applicants.

    What is not yet known, and how to find out

    • Cost of technology-transfer process changes and evaluation (cost)Next step: Research England to survey universities’ technology-transfer costs and price an evaluation.Scope: UK universities; five-year evaluation · Data or quotes needed: Staff and legal costs per deal; evaluator quotes · Who can estimate it: Research England (UKRI)
    • Whether UK proof-of-concept awards change follow-on finance (effect)Next step: Compare funded and near-miss applicants using the published ranking.Defensible route: evaluation of existing delivery
    • How the £20m has been allocated so far (data)Next step: Check DSIT and UKRI award records before the next round.

    Sources last checked 4 October 2026 · Owner: Evidence editor (James Harris) · Next check: ONS business enterprise research and development, UK: 2025 (27 November 2026, provisional) or the first trigger: Proof-of-concept programme competition results or rules.

    More decision briefs on other pages

    What it would take

    The order things have to happen in, who pays, and the effects and appraisals on record.

    The order things have to happen in

    1. First, the prerequisite

      Baseline spin-out deal time and terms by university

      Owner: DSIT with Research England

      No date: the timing depends on the steps before it.

    2. Then, the decision

      Name a public-service problem, success threshold and buyer for an innovation trial

      Owner: A commissioning body

      No date: the timing depends on the steps before it.

    3. Then, delivery

      Standard terms and shared technology transfer piloted; trial run and evaluated

      Owner: Universities; commissioning body; evaluator

      No date: the timing depends on the steps before it.

    4. Finally, the measured outcome

      Follow-on finance, survival and adoption tracked over several years

      Owner: UKRI; British Business Bank; evaluators

      No date: the timing depends on the steps before it.

    5. Then, delivery

      Run diagnostic and adoption support with a randomised or phased comparison

      Owner: BIST with mayoral authorities

      No date: the timing depends on the steps before it.

    Who pays, and what is still missing

    Cost, committed funding and the remaining gap for the same scope and years. A programme envelope is not an award to a project; a proposal is not committed money. No total is shown because these costs are on different bases or periods and cannot be added.

    Cost and funding ledger

    • Cross-disciplinary proof-of-concept research programme (announced)

      A41 · recurring spending · published programme envelope

      Amount
      £20m in total, Announced November 2023; delivery years not stated in the response., price basis not stated by the source
      Who pays
      central government
      Committed
      None identified
      Proposed, not committed
      £20m (£20m proof-of-concept research programme)
      Gap
      Not established
    • Technology-transfer capacity, legal work and data on deal terms

      A41 · administration · not costed

      Amount
      Not yet costed
      Who pays
      central government, private investors
      Committed
      None identified
      Proposed, not committed
      —
      Gap
      Not established
    • Trial, integration, staff training, security, maintenance and exit

      A42 · administration · not costed

      Amount
      Not yet costed
      Who pays
      central government, councils, NHS
      Committed
      None identified
      Proposed, not committed
      —
      Gap
      Not established

    “Not yet costed” means no defensible cost has been found — not that the action is free. Lifetime benefits, benefit-cost ratios and forecast savings are never shown here as money available to spend.

    What the evidence says each action changes

    No effect has been established for these actions yet: direction plausible; size not established.

    How we would know

    Gross domestic expenditure on R&D; Active university spin-outs; Equity finance raised by smaller businesses; and 1 more.

    The outcome measures to watch. A baseline is where we start, not a target; where there is no official target we say so.

    Measured results

    What each option would be judged on, and the latest value of the measures already on this page. A measure moving is not proof that an option caused it.

    Where the ideas come from

    Research, counter-evidence and methods (12 sources; 1 claim held back)
    • Gross domestic expenditure on research and development, UK: 2024 — Office for National Statistics, 7 August 2026.Official statistics; United Kingdom. Relevant passages checked, 2026-10-04.
    • Building on the UK’s first spin-out register — UKRI / Research England, 30 January 2026.Official data digest; United Kingdom. Relevant passages checked, 2026-10-04.
    • Made Smarter Adoption: impact and process evaluation (Ipsos) — Department for Business and Trade, 2026-07-30.Programme evaluation; England (pilot regions). Summary or abstract only, 2026-10-04. Limits: Finding as recorded on the innovation page; the full evaluation was not re-read in this review.
    • Independent review of university spin-out companies (with government response and Annex D founder survey) — Irene Tracey / Andrew Williamson, published by DSIT and HM Treasury (Professor Irene Tracey, Dr Andrew Williamson), 2023-11-21.Independent review with stakeholder engagement and a founder survey; United Kingdom. Relevant passages checked, 2026-10-04. Limits: Recommendations, not causal evidence; the reviewers are a vice-chancellor and an investor. How far universities have adopted the recommended terms has not been checked here.
    • Small Business Equity Tracker 2026 — British Business Bank, 2 July 2026.Research report; United Kingdom. Summary or abstract only (live page returned HTTP 403 to automated checks; figures are the innovation page’s stored record), 2026-10-04.
    • Management practices in the UK: 2016 to 2023 — Office for National Statistics, 2024-05-13.Official statistics in development; Great Britain (firms with 10 or more employees). Relevant passages checked, 2026-10-07. Limits: Correlation with productivity only (a 1% higher labour productivity goes with a 0.02 higher score); 27% response rate in 2023.
    • Help to Grow: Management phase 1 final evaluation report (process and impact) — Department for Business and Trade (Ipsos and IES); now BIST, 2026-06-11.Pipeline comparison (early against later completers) and propensity-score matching of completers against dropouts using the Business Structure Database (to FY2022/23).; United Kingdom. Relevant passages checked, 2026-10-07. Limits: Unobserved differences between completers and dropouts; outcomes only to FY2022/23; small matching sample (657 against 222); the survival result is labelled significant at 5% with p = 0.052.
    • Government response: Independent review of university spin-outs — DSIT and HM Treasury, 2023-11-22.Government response; United Kingdom. Relevant passages checked, 2026-10-04.
    • The role of procurement in delivering mission-led government — Institute for Government (Ben Paxton, Nick Davies), 2025-09-23.Interview-based analysis with recommendations; United Kingdom (mainly central government). Relevant passages checked, 2026-10-04. Limits: Qualitative: no estimate of savings or service effects. It does not contain a £461bn figure — the site’s £461.3bn whole-public-sector total comes from PESA 2026 (P-HMT-PESA-2026).
    • The Magenta Book: Central Government guidance on evaluation — HM Treasury / Evaluation Task Force, 2026-05-14.Official evaluation guidance; UK central government. Relevant passages checked, 2026-10-04. Limits: Guidance; supplies no policy result.
    • Does management matter? Evidence from India — NBER Working Paper 16658 (2011); Quarterly Journal of Economics (2013) (Bloom N, Eifert B, Mahajan A, McKenzie D, Roberts J), 2011.Randomised field experiment; India (large textile firms). Relevant passages checked, 2026-10-07. Limits: Large firms in one industry abroad; the published QJE figures were not re-read.
    • Evidence review: business advice — What Works Centre for Local Economic Growth, 2016-06.Systematic evidence review; UK and OECD. Relevant passages checked, 2026-10-07. Limits: Little evidence on cost-effectiveness; no studies of women-led or ethnic-minority-led firms.

    Counter-evidence and criticism

    • Make university spin-out deals clearer and quicker: More, faster spin-outs may not mean better ones; universities’ income from equity funds research; the reviewers are a vice-chancellor and an investor. (Irene Tracey / Andrew Williamson, published by DSIT and HM Treasury)
    • Use public buying to test useful innovations: Pilots often never scale; vendors can capture buyers; novelty can be bought without operational value. (Institute for Government)
    • Test management and adoption support for existing firms against a comparison: The UK schemes evaluated so far show no productivity effect, so a new test may also find none. (Department for Business and Trade)

    Claims held back

    • Universities have adopted the spin-out review’s recommended deal terms — Implementation reporting was not checked in this review. Needed: Government or Research England reporting on adoption of the recommended policies.

    “Full text checked” means we read the report itself; “relevant passages” means the sections behind each figure; “summary or abstract only” means we could not read the full study, so no number from it is published here without another source.

    Other options compared — not on the shortlist (4)

    Other options compared

    Options from earlier work on this page that are not on the shortlist. They remain valid choices; their evidence is shown as before.

    • capacityStatus: operating

      Grants for business-led innovation projects

      Aims to:
      More research-based products reaching market, especially from smaller firms.
      How:
      Competitive grants (such as Innovate UK Smart Grants) part-fund firms’ development projects that are too risky for private finance alone.
      Who decides:
      BIST and UKRI / Innovate UK.
      Main constraint:
      Grants select projects firms were partly willing to do anyway; success rates are low, so applying is costly for small firms.
      Evidence:
      Moderate evidence — evaluated, with limits on scope or transfer
      See the trade-offs and evidence
      What the evidence shows
      The final impact evaluation of Smart Grants estimated £820m of additional gross value added by the end of 2024–25 from £403m of funding — about £2.18 per £1 of public spending — projected to rise to £4.47 per £1 by 2032–33. These are modelled estimates from a comparison-group evaluation, with wide uncertainty about the later years.
      Resources
      Grant budgets; assessors; firms’ matched funding.
      Consent and decisions needed
      Set in UKRI budget allocations at Spending Reviews.
      Time
      Projects run one to three years; the evaluation finds most estimated value arrives years after the grant.
      Cost and yield
      Programme-specific; the Smart Grants cohort evaluated cost £403m of public funding.
      Trade-offs and who pays
      Money for grants competes with basic research funding; picking projects risks favouring firms good at applying.
      How we would know it worked
      Leading indicator: Grant-funded products reaching market within three years. Outcome: Turnover and productivity of funded firms against a comparison group. It would not be working if: Funded firms perform no better than similar unfunded applicants.
    • structuralStatus: operating

      Patient finance for firms that are scaling up

      Aims to:
      Growing firms able to raise large later-stage rounds in the UK rather than selling early or moving abroad.
      How:
      Public investment vehicles (the British Business Bank and its British Growth Partnership) and pension capital invest alongside private funds in later-stage rounds.
      Who decides:
      HM Treasury; the British Business Bank; pension trustees and fund managers.
      Main constraint:
      Pension trustees’ duties to members; the number of firms genuinely ready to scale.
      Evidence:
      Limited evidence — plausible mechanism, little direct evaluation
      See the trade-offs and evidence
      What the evidence shows
      There is good evidence that equity finance for smaller firms is cyclical — £12.3bn in 2025, down on 2024 — but little evaluation of whether public co-investment adds money rather than displacing private investors at the scale-up stage.
      Resources
      Public capital on the Bank’s balance sheet; pension allocations; experienced fund managers.
      Consent and decisions needed
      Treasury capital allocations; voluntary pension commitments.
      Time
      Fund cycles of ten years or more.
      Cost and yield
      Public capital is an investment that may return money; losses fall on the taxpayer or savers.
      Trade-offs and who pays
      Risk to public money and savers; possible displacement of private investors.
      How we would know it worked
      Leading indicator: Number and size of UK later-stage funding rounds. Outcome: Firms reaching scale while keeping headquarters and R&D in the UK. It would not be working if: Public money rises but total later-stage investment does not.
    • preventionStatus: operating

      Help for existing firms to adopt technology

      Aims to:
      Higher productivity in ordinary firms, especially smaller manufacturers and services, from proven technology.
      How:
      Advice, matched funding and training (such as Made Smarter Adoption) lower the cost and risk of a small firm’s first digital or automation project.
      Who decides:
      BIST; local and regional delivery partners; industry bodies.
      Main constraint:
      Management capability and staff skills inside the firm; small firms’ time.
      Evidence:
      Limited evidence — plausible mechanism, little direct evaluation
      See the trade-offs and evidence
      What the evidence shows
      The Made Smarter Adoption impact evaluation found no evidence of a step-change in productivity: the average yearly effect on gross value added was not statistically different from zero, and later-year gains were judged implausibly large by the evaluators. Adoption support is plausible, but this flagship scheme has not shown it works.
      Resources
      Advisers, matched grants, management training.
      Consent and decisions needed
      Low political cost; budgets are small.
      Time
      Several years before productivity effects can be measured.
      Cost and yield
      Programme-specific; no general cost per productivity gain.
      Trade-offs and who pays
      Support may go to firms that would have adopted anyway.
      How we would know it worked
      Leading indicator: Technology use by firm size (ONS survey). Outcome: Output per hour in supported firms against comparable firms. It would not be working if: Adoption rises but productivity does not differ from comparison firms.
    • capacityStatus: operating

      Specialist skills and research infrastructure

      Aims to:
      Researchers and firms able to recruit specialist staff and use advanced computing.
      How:
      Visa routes for highly skilled people, doctoral training and access to public compute (the AI Research Resource) remove specific bottlenecks for research-intensive firms.
      Who decides:
      Home Office (visas); UKRI (training, compute); BIST (AI Research Resource).
      Main constraint:
      Immigration policy; electricity and grid capacity for compute; global competition for staff.
      Evidence:
      Not evaluated — a mechanism to test, not an evidenced fix
      See the trade-offs and evidence
      What the evidence shows
      Public AI compute is open to UK small firms and researchers through Rapid Access and Gateway routes, but there is no published evaluation of what it has enabled. Visa route effects on innovation have not been officially evaluated.
      Resources
      Training places; compute capacity; visa processing.
      Consent and decisions needed
      Skilled migration is politically contested.
      Time
      Visas act within months; doctoral training takes four years.
      Cost and yield
      No combined costing.
      Trade-offs and who pays
      Migration targets; compute budgets compete with other research spending.
      How we would know it worked
      Leading indicator: Specialist vacancies filled; compute hours allocated to firms. Outcome: R&D-intensive firms’ growth. It would not be working if: Vacancies persist despite more routes and capacity.
    The options side by side
    OptionResourcesTimeEvidenceOutcome to watch
    Grants for business-led innovation projectsGrant budgets; assessors; firms’ matched funding.Projects run one to three years; the evaluation finds most estimated value arrives years after the grant.moderateTurnover and productivity of funded firms against a comparison group.
    Patient finance for firms that are scaling upPublic capital on the Bank’s balance sheet; pension allocations; experienced fund managers.Fund cycles of ten years or more.limitedFirms reaching scale while keeping headquarters and R&D in the UK.
    Help for existing firms to adopt technologyAdvisers, matched grants, management training.Several years before productivity effects can be measured.limitedOutput per hour in supported firms against comparable firms.
    Specialist skills and research infrastructureTraining places; compute capacity; visa processing.Visas act within months; doctoral training takes four years.not evaluatedR&D-intensive firms’ growth.

    Plan reviewed 2026-10-07. How we judge evidence.

    How this connects

    Sources and methods (9)

    Method notes

    • GERD is all R&D performed in a country, whoever funds it. BERD is the business-performed part. Government R&D budgets are a third, different measure.
    • ONS redeveloped its business R&D survey with effect from 2022, raising measured UK R&D from about 1.7% to about 2.7% of GDP. Only 2022–2024 are accredited official statistics; comparisons with older UK headlines are invalid.
    • Equity investment is from the British Business Bank’s analysis of commercial deal data, not an official statistic. Spin-out counts are from Research England’s register.