Energy & bills · Great Britain · Oct–Dec 2026

The same energy use now costs 76% more than in 2021, before inflation.

At Ofgem’s typical usage (2,500 kWh of electricity and 9,500 kWh of gas a year), the Great Britain direct-debit price cap comes to £1,723 a year for October–December 2026, against £979 for April–September 2021 on Ofgem’s like-for-like recalculation. Allowing for general inflation, the rise is roughly a third (UK Facts calculation). The cap limits unit rates and standing charges, not anyone’s total bill.

Priority: Reduce household and business exposure to high energy costs through appraised supply, grid, demand and pricing options. What would change it →

Evidence last reviewed 3 October 2026

Overview

The short version

Three key measures

Who feels this most?

The same rates land very differently. Standing charges of £308 a year are a bigger share of a small bill, and a poorly insulated home needs more kWh for the same warmth. In England, 9.4% of households — 2.36 million — were estimated to be fuel poor in 2025, with an average gap of £379 between their energy costs and what would take them out of fuel poverty.

The evidence

From the bill at home to the costs of the energy system

What households pay now

The cap sets a maximum price for each kilowatt-hour and a maximum daily standing charge on default tariffs. Ofgem’s headline £1,723 is those rates applied to 2,500 kWh of electricity and 9,500 kWh of gas — Ofgem’s typical use since July 2026. In Ofgem’s words, the cap sets “maximum prices, not maximum bills”. Change the usage below and the bill moves while the rates do not.

What would a year of energy cost at the capped rates?

The cap limits rates, not your total bill

Annual cost = standing charges × 365 days + unit rate × kWh used, at Ofgem’s direct-debit cap rates for the chosen period. Starts at Ofgem’s typical consumption: 2,500 kWh of electricity and 9,500 kWh of gas a year.

Great Britain average (England, Scotland, Wales); not Northern Ireland · Jan–Mar 2019 to Oct–Dec 2026
Typical: 2,500 kWh · 26.32p per kWh
Typical: 9,500 kWh · 7.97p per kWh

Annual cost at these rates

£1,723 a year

The arithmetic

Electricity: 2,500 kWh × 26.32p = £658

Gas: 9,500 kWh × 7.97p = £757

Standing charges: (54.83p + 29.68p) × 365 days = £308

Total: £1,723 a year (rounded to the nearest pound, including VAT)

Double the electricity you use and the unit-rate part of the bill doubles, though the capped rate has not changed. The standing charges — £308 a year for a dual-fuel home on direct debit — are paid however little you use. That is why the cap’s headline figure describes no particular household: it is the cap’s rates applied to one assumed level of use. The main limit is geography: these are GB averages, and the rates in your region differ.

Great Britain average (England, Scotland, Wales); not Northern Ireland · Jan–Mar 2019 to Oct–Dec 2026 · Official cap rates; the annual cost is an illustration, not a supplier quote

Sources, definitions and data — The cap limits rates, not your total bill
Geography:
Great Britain average (England, Scotland, Wales); not Northern Ireland — Default (standard variable) tariffs, paid by direct debit, single-rate electricity meter
Measure:
£ a year, including VAT; rates in pence per kWh and pence per day
Period:
Jan–Mar 2019 to Oct–Dec 2026
Status:
Official cap rates; the annual cost is an illustration, not a supplier quote
Calculation:
Unit rates and standing charges are derived exactly from Ofgem’s published nil- and typical-consumption cap levels (level = standing charge × 365 + unit rate × kWh); they reproduce Ofgem’s quoted rates to the penny. The annual cost is that formula applied to the usage you enter.
Compare with:
The same rates at Ofgem’s typical consumption: £1,723 a year for Oct–Dec 2026
Not included / breaks:
Regional rates differ from the GB average, and prepayment and standard-credit caps are set at different levels; neither is held here yet. Fixed tariffs and Economy 7 meters are outside this cap. From October 2022 to June 2023 households were charged lower Energy Price Guarantee rates, and the £400 Energy Bills Support Scheme discount is not deducted.

Source: Ofgem, Energy price cap (default tariff) levels — Annex 9, levelised cap levels, sheet 1c 'Consumption adjusted levels', Other Payment Method (direct debit) (released 26 August 2026). Chart ENERGY-01.

View the data as a table
Cap periodElectricity p/kWhElectricity p/dayGas p/kWhGas p/dayAt 2,500/9,500 kWh, £/yr
Jan–Mar 201916.5222.773.7325.82945
Apr–Sep 201918.5623.424.1426.521039
Oct 2019–Mar 202017.8523.513.6826.71979
Apr–Sep 202017.8124.383.5027.35967
Oct 2020–Mar 202117.1924.383.0026.07899
Apr–Sep 202118.9524.893.3426.60979
Oct 2021–Mar 202220.8024.884.0726.121093
Apr–Sep 202228.3445.347.3727.221673
Oct–Dec 2022 (EPG applied)51.8946.3614.7628.482972
Jan–Mar 2023 (EPG applied)67.4746.3617.0828.483582
Apr–Jun 2023 (EPG applied)50.6052.9712.6129.112762
Jul–Sep 202330.1152.977.5129.111766
Oct–Dec 202327.3553.376.8929.621641
Jan–Mar 202428.6253.357.4229.601723
Apr–Jun 202424.5060.106.0431.431520
Jul–Sep 202422.3660.125.4831.411414
Oct–Dec 202424.5060.996.2431.661543
Jan–Mar 202524.8660.976.3431.651561
Apr–Jun 202527.0353.806.9932.671655
Jul–Sep 202525.7351.376.3329.821541
Oct–Dec 202526.3553.686.2934.031576
Jan–Mar 202627.6954.755.9335.091584
Apr–Jun 202624.6757.215.7429.091477
Jul–Sep 202626.1157.197.3329.041663
Oct–Dec 202626.3254.837.9729.681723

Scroll the table sideways to see every column.

Has the energy shock passed?

The energy shock eased, but the comparable bill remains above its earlier level

Ofgem’s cap for a dual-fuel direct-debit household, restated by Ofgem for every period at one consumption (2,500 kWh electricity, 9,500 kWh gas), £ a year in cash terms. Each step is one cap period.

Great Britain average · Jan–Mar 2019 to Oct–Dec 2026

1996–2026 displayed window · observations only. Shading marks years outside the displayed record.

£ a year, cash, at typical useNo observations shownPrice guarantee£0£1,000£2,000£3,000£4,000200020102020£1,723
On a like-for-like basis the cap rose from £979 in Apr–Sep 2021 to a peak of £3,582 in Jan–Mar 2023, then fell back. It has not returned: at £1,723 it is 76% above the 2021 level in cash terms. During the peak, the government’s price guarantee held what households were actually charged well below the cap. The figures are cash amounts; after inflation the rise is smaller but still about 31%.

Great Britain average · Jan–Mar 2019 to Oct–Dec 2026 · Official statistics; latest period provisional

Sources, definitions and data — The energy shock eased, but the comparable bill remains above its earlier level
Geography:
Great Britain average — Default tariffs, direct debit
Measure:
£ a year, cash (nominal), including VAT
Period:
Jan–Mar 2019 to Oct–Dec 2026
Status:
Official statistics; latest period provisional
Calculation:
As published by Ofgem on its latest consumption basis; drawn as steps because the cap is fixed within each period (six-monthly to September 2022, quarterly since).
Compare with:
Apr–Sep 2021, before wholesale gas prices surged: £979
Not included / breaks:
Cash terms — see the real-terms chart on the bill history page. The shaded period is when the Energy Price Guarantee set lower prices than the cap, so households did not pay the cap. The £400 Energy Bills Support Scheme discount (October 2022–March 2023) is not deducted. These comparable figures differ from the ones Ofgem announced at the time, which used older, higher consumption assumptions (both are in the table).

Source: Ofgem, Energy price cap (default tariff) levels — Annex 9, levelised cap levels, sheet 1c 'Consumption adjusted levels', Other Payment Method (direct debit) (released 26 August 2026). Chart ENERGY-02.

View the data as a table
Cap periodComparable basis, £/yrAs announced at the time, £/yr
Jan–Mar 20199451137
Apr–Sep 201910391254
Oct 2019–Mar 20209791179
Apr–Sep 20209671126
Oct 2020–Mar 20218991042
Apr–Sep 20219791138
Oct 2021–Mar 202210931277
Apr–Sep 202216731971
Oct–Dec 202229723549
Jan–Mar 202335824279
Apr–Jun 202327623280
Jul–Sep 202317662074
Oct–Dec 202316411834
Jan–Mar 202417231928
Apr–Jun 202415201690
Jul–Sep 202414141568
Oct–Dec 202415431717
Jan–Mar 202515611738
Apr–Jun 202516551849
Jul–Sep 202515411720
Oct–Dec 202515761755
Jan–Mar 202615841758
Apr–Jun 202614771641
Jul–Sep 202616631663
Oct–Dec 202617231723

Where a bill goes

Where does a capped bill go?

Wholesale energy is 45% of the typical capped bill; networks 24%

The cost allowances Ofgem uses to build the cap for Oct–Dec 2026, dual fuel at typical consumption, direct debit, £ a year.

Great Britain average · Oct–Dec 2026
  • Wholesale energy£774 (45%)
  • Networks£417 (24%)
  • Supplier operating costs£204 (12%)
  • Policy costs£96 (6%)
  • Bad debt£52 (3%)
  • Supplier profit allowance£46 (3%)
  • VAT£41 (2%)
  • Capacity Market£38 (2%)
  • Industry charges£35 (2%)
  • Headroom£18 (1%)
  • Levelisation£8 (0%)
  • Smart meter roll-out (net)−£7 (a saving, not drawn)
Two parts dominate: buying the energy, and the networks that carry it. Wholesale energy is the part that moved most in the crisis and still moves with international gas prices. Network costs are set by Ofgem’s price controls for the wires and pipes and change more slowly; on this basis they have roughly doubled since 2019. Policy costs fell in April 2026 when the government moved most Renewables Obligation costs to taxation and ended the Energy Company Obligation. Read these as allowances, not as audited spending.

Great Britain average · Oct–Dec 2026 · Official allowances, not audited costs

Sources, definitions and data — Wholesale energy is 45% of the typical capped bill; networks 24%
Geography:
Great Britain average — Default tariffs, direct debit, typical consumption
Measure:
£ a year, cash; components excluding VAT, with VAT shown separately
Period:
Oct–Dec 2026
Status:
Official allowances, not audited costs
Calculation:
As published by Ofgem (each component line of sheet 1c). Components sum to £1,723 against the published total of £1,723; any difference is rounding in Ofgem’s tables.
Compare with:
Total cap at typical use, £1,723
Not included / breaks:
These are what Ofgem allows an efficient supplier to recover, not a record of where any company’s money went. VAT on electricity is 0% from 1 October 2026, so the VAT line is smaller than in earlier periods.

Source: Ofgem, Energy price cap (default tariff) levels — Annex 9, levelised cap levels, sheet 1c 'Consumption adjusted levels', Other Payment Method (direct debit) (released 26 August 2026). Chart ENERGY-03.

View the data as a table
Component£ a yearShare of totalWhat it pays for
Wholesale energy773.9844.9%Buying gas and electricity on the wholesale market, including hedging.
Networks417.3424.2%Building, running and paying a regulated return on the transmission and distribution wires and pipes.
Supplier operating costs203.9411.8%Billing, customer service, metering and other running costs.
Policy costs96.395.6%Government schemes funded through bills, such as the Renewables Obligation, feed-in tariffs and the Warm Home Discount.
Bad debt51.793.0%Allowance for unpaid bills and the cost of collecting debt.
Supplier profit allowance45.722.7%Earnings before interest and tax that Ofgem allows an efficient supplier — an allowance, not a measured profit.
Capacity Market38.442.2%Payments to keep enough power stations and storage available for peak demand.
Industry charges35.292.0%Charges for industry bodies and systems.
Headroom18.131.1%A margin for uncertainty in Ofgem’s estimates.
Levelisation8.050.5%Redistribution that evens out standing charges between payment methods.
Smart meter roll-out (net)-6.93-0.4%Net change in supplier costs from the smart meter roll-out; can be negative.
VAT41.202.4%Value added tax on domestic energy.

Scroll the table sideways to see every column.

Gas, generation, networks and policy costs

Wholesale energy (£774) follows the international gas price. Gas plants made under half of the UK’s electricity in 2021 but set the wholesale power price almost all of the time, so a gas shock raises electricity prices too. Networks (£417, up from £209 in Jan–Mar 2019) pay for the wires and pipes under Ofgem’s price controls. Policy costs fell to £96 in April 2026 when most Renewables Obligation costs moved to taxation. How each part has changed since 2019.

Who owns which part of the system?

Part of the systemShare of the typical billHow it is organised
Generation and wholesale energy£774Competitive market. Companies include UK-listed groups and UK subsidiaries of overseas parents; many low-carbon projects sell power under government-backed contracts.
Networks (wires and pipes)£417Regional monopolies owned by private investors; Ofgem sets what they may earn in multi-year price controls.
System operationwithin networks and industry chargesThe National Energy System Operator, publicly owned since 1 October 2024.
Supply (your energy company)£250Competitive retail market; the cap allows an efficient supplier its operating costs and a profit allowance of £46.

Supply share = operating costs plus profit allowance; bad debt, headroom and other lines are excluded. Every company, checked against the Companies House register.

Who feels this most?

Who is most likely to be in fuel poverty?

Prepayment customers, homes off the gas grid and private renters are about twice as likely as average to be fuel poor

Share of households in each group that are in fuel poverty (low income and a home rated band D or worse), England, 2025. Three separate breakdowns of the same households: by how they pay for electricity, gas connection, and tenure.

England only (fuel poverty is measured differently in Scotland, Wales and Northern Ireland) · 2025 (projection from 2024 final estimates)
2025England 9.4%
  • Pays electricity by prepayment meter17.9%
  • Off the gas grid17.7%
  • Private renters17.2%
  • Pays electricity by standard credit (on receipt of bill)12.7%
  • Social renters12.0%
  • Pays electricity by direct debit8.1%
  • On the gas grid8.0%
  • Owner occupiers who own outright6.6%
  • Owner occupiers with a mortgage6.5%
Fuel poverty depends on three things together: income, how efficient the home is, and the price of energy. The groups most exposed are those where low incomes meet less efficient homes — private renters, households off the gas grid (who heat with oil or electricity) and those on prepayment meters, whose median income is the lowest. These are associations within one survey, not separate causes. Overall 9.4% of households, 2.36 million, were estimated to be fuel poor.

England only (fuel poverty is measured differently in Scotland, Wales and Northern Ireland) · 2025 (projection from 2024 final estimates) · Accredited official statistics; 2025 figures are projections

Sources, definitions and data — Prepayment customers, homes off the gas grid and private renters are about twice as likely as average to be fuel poor
Geography:
England only (fuel poverty is measured differently in Scotland, Wales and Northern Ireland) — All households
Measure:
% of households in the group
Period:
2025 (projection from 2024 final estimates)
Status:
Accredited official statistics; 2025 figures are projections
Calculation:
As published by DESNZ (Low Income Low Energy Efficiency measure). Each breakdown covers all households, so rows from different breakdowns overlap and do not add up.
Compare with:
All households in England, 9.4%
Not included / breaks:
The measure counts a household as fuel poor only if its home is rated band D or below, so a low-income household in an efficient home is not counted however high its bills. DESNZ notes the higher rate among prepayment users reflects their lower incomes, not the tariff itself.

Source: DESNZ, Annual Fuel Poverty Statistics in England, 2026 (2025 data), report pp. 1, 36, 37 and 49 (Figures 3.13, 3.14, 3.26) (released 26 March 2026; corrected 7 August 2026). Chart ENERGY-05.

View the data as a table
GroupFuel poverty rate, %
Pays electricity by prepayment meter17.9
Off the gas grid17.7
Private renters17.2
Pays electricity by standard credit (on receipt of bill)12.7
Social renters12.0
Pays electricity by direct debit8.1
On the gas grid8.0
Owner occupiers who own outright6.6
Owner occupiers with a mortgage6.5
All households in England9.4
Shareable visual summary

Visual summary

Image current

Every figure printed in the image matches today’s record, and its primary sources have been checked.

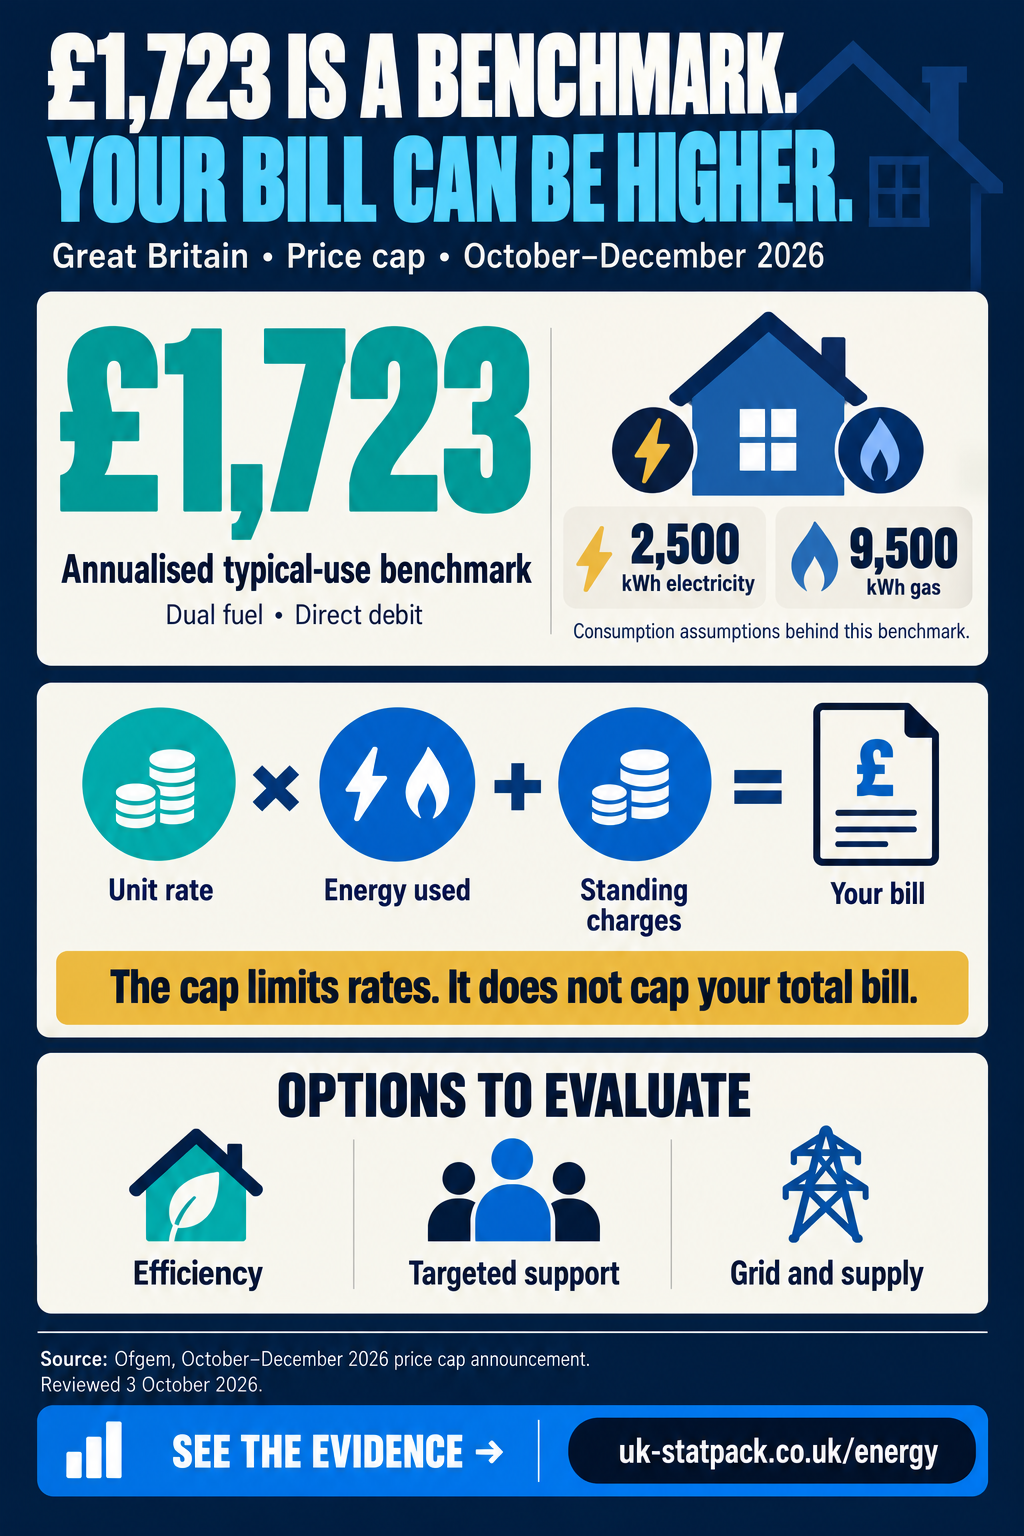
The same energy use now costs 76% more than in 2021, before inflation.

At the same typical use (2,500 kWh electricity, 9,500 kWh gas a year), Ofgem’s Great Britain dual-fuel direct-debit cap comes to £1,723 a year for October–December 2026, against £979 in April–September 2021: 76% more in cash, not adjusted for inflation. A benchmark, not a maximum bill: the cap limits unit rates and standing charges; use more and you pay more.

  • £979Apr–September 2021, same typical use
  • £1,723Oct–December 2026, same typical use
  • 76%more in cash terms

Your bill = your usage × capped unit rates + capped daily standing charges.

Great Britain, dual fuel, direct debit. Source: Ofgem, Energy price cap.
Download image (PNG, 1024 by 1536 pixels)

The same energy use now costs 76% more than in 2021, before inflation.

Energy infographic: £1,723 is Ofgem’s typical-use annual benchmark for October–December 2026 in Great Britain; it is not a maximum bill.
Text and data version

The same energy use now costs 76% more than in 2021, before inflation. At the same typical use (2,500 kWh electricity, 9,500 kWh gas a year), Ofgem’s Great Britain dual-fuel direct-debit cap comes to £1,723 a year for October–December 2026, against £979 in April–September 2021: 76% more in cash, not adjusted for inflation. A benchmark, not a maximum bill: the cap limits unit rates and standing charges; use more and you pay more.

Records behind this visual summary
MeasureValuePeriodGeographyTypeSource
Ofgem price cap, typical dual-fuel direct-debit annual billCalculation: (elec standing charge + elec unit rate × TDCV_electricity) + (gas standing charge + gas unit rate × TDCV_gas), with TDCV set to the value Ofgem used for that cap period£1,723Oct–Dec 2026Great Britainpolicy target (provisional)Ofgem, Default tariff cap
Ofgem price cap at matched typical use, April–September 2021£979Apr–Sep 2021Great Britainpolicy targetOfgem, Default tariff cap
Ofgem price cap at matched typical use, latest period£1,723Oct–Dec 2026Great Britainpolicy target (provisional)Ofgem, Default tariff cap
Cash rise in the typical-use cap since April–September 2021 (same consumption)Calculation: (latest ÷ April–September 2021 − 1) × 100, same typical consumption, cash terms76%Oct–Dec 2026Great Britainderived calculation (provisional)Ofgem, Default tariff cap

Image description: Energy infographic: £1,723 is Ofgem’s typical-use annual benchmark for October–December 2026 in Great Britain; it is not a maximum bill.

Social card

A landscape card for sharing this finding. Post it with the page link — an uploaded image does not link back by itself.

The £1,723 energy-cap figure is a typical-use annualised benchmark for Great Britain, October–December 2026. It limits rates, not your total bill. Understand the assumptions and what your usage changes.
Download image (PNG, 1536 by 1024 pixels)

The same energy use now costs 76% more than in 2021, before inflation.

Energy social card. Ofgem’s annualised typical dual-fuel direct-debit cap benchmark was £1,723 in Great Britain for October–December 2026. It is not a maximum bill.

All visual summaries, their source records and their publication state are listed on Shareable visuals.

Go deeper

  • Is energy still dearer than before the crisis?
    +93.6%Jan 2015–Aug 2026United Kingdom · index (2015=100)
    No observationsshown015030019962026
    100.2 → 194Jan 2015–Aug 2026
    Electricity price index, not a typical household bill. The price cap itself begins in 2019.
    Sources and data

    Covers all domestic electricity tariffs (default, fixed and prepayment) in the UK, including Northern Ireland, so it is not the Ofgem cap, which is Great Britain default tariffs only. ONS classifies the £400 Energy Bills Support Scheme (October 2022 to March 2023) as a transfer to households, not a price reduction, so it does not lower this index. The Energy Price Guarantee (October 2022 to June 2023) was a subsidy that cut the prices households were charged, so it does.

    Source dataset →
    Periodindex (2015=100)Status
    Jan 2015100.2Outturn
    Feb 2015100.2Outturn
    Mar 2015100.2Outturn
    Apr 2015100Outturn
    May 2015100Outturn
    Jun 201599.9Outturn
    Jul 201599.9Outturn
    Aug 201599.9Outturn
    Sep 201599.9Outturn
    Oct 201599.9Outturn
    Nov 201599.9Outturn
    Dec 201599.9Outturn
    Jan 201699.9Outturn
    Feb 201699.9Outturn
    Mar 201699.9Outturn
    Apr 201699.7Outturn
    May 201699.7Outturn
    Jun 201699.7Outturn
    Jul 201699.7Outturn
    Aug 201699.7Outturn
    Sep 201699.7Outturn
    Oct 201699.7Outturn
    Nov 201699.7Outturn
    Dec 201699.7Outturn
    Jan 201799.7Outturn
    Feb 201799.7Outturn
    Mar 2017100.7Outturn
    Apr 2017103.2Outturn
    May 2017107.4Outturn
    Jun 2017107.4Outturn
    Jul 2017108.7Outturn
    Aug 2017108.7Outturn
    Sep 2017108.7Outturn
    Oct 2017111.1Outturn
    Nov 2017111.1Outturn
    Dec 2017111.1Outturn
    Jan 2018111.1Outturn
    Feb 2018111.1Outturn
    Mar 2018111.1Outturn
    Apr 2018112.1Outturn
    May 2018112.2Outturn
    Jun 2018114.7Outturn
    Jul 2018116.7Outturn
    Aug 2018116.7Outturn
    Sep 2018118.8Outturn
    Oct 2018121.2Outturn
    Nov 2018121.2Outturn
    Dec 2018121.2Outturn
    Jan 2019115.3Outturn
    Feb 2019115.4Outturn
    Mar 2019115.4Outturn
    Apr 2019127.9Outturn
    May 2019127.9Outturn
    Jun 2019127.9Outturn
    Jul 2019127.9Outturn
    Aug 2019127.9Outturn
    Sep 2019127.9Outturn
    Oct 2019125.2Outturn
    Nov 2019125.2Outturn
    Dec 2019125.2Outturn
    Jan 2020125.2Outturn
    Feb 2020125.2Outturn
    Mar 2020125.2Outturn
    Apr 2020125.4Outturn
    May 2020125.4Outturn
    Jun 2020125.4Outturn
    Jul 2020125.3Outturn
    Aug 2020125.3Outturn
    Sep 2020125.3Outturn
    Oct 2020121.2Outturn
    Nov 2020121.2Outturn
    Dec 2020121.2Outturn
    Jan 2021121.2Outturn
    Feb 2021121.2Outturn
    Mar 2021121.2Outturn
    Apr 2021132.3Outturn
    May 2021132.3Outturn
    Jun 2021132.3Outturn
    Jul 2021132.5Outturn
    Aug 2021132.5Outturn
    Sep 2021132.5Outturn
    Oct 2021144Outturn
    Nov 2021144Outturn
    Dec 2021144Outturn
    Jan 2022144.5Outturn
    Feb 2022144.5Outturn
    Mar 2022144.5Outturn
    Apr 2022203.2Outturn
    May 2022203.2Outturn
    Jun 2022203.2Outturn
    Jul 2022204.1Outturn
    Aug 2022204.1Outturn
    Sep 2022204.1Outturn
    Oct 2022238.6Outturn
    Nov 2022238.1Outturn
    Dec 2022238.1Outturn
    Jan 2023240.9Outturn
    Feb 2023240.9Outturn
    Mar 2023240.9Outturn
    Apr 2023238.3Outturn
    May 2023238.3Outturn
    Jun 2023238.3Outturn
    Jul 2023217.7Outturn
    Aug 2023217.7Outturn
    Sep 2023217.7Outturn
    Oct 2023201.4Outturn
    Nov 2023201.4Outturn
    Dec 2023201.4Outturn
    Jan 2024209.6Outturn
    Feb 2024209.6Outturn
    Mar 2024209.6Outturn
    Apr 2024188.1Outturn
    May 2024188.1Outturn
    Jun 2024188.1Outturn
    Jul 2024175.3Outturn
    Aug 2024175.3Outturn
    Sep 2024175.3Outturn
    Oct 2024188.8Outturn
    Nov 2024188.8Outturn
    Dec 2024189Outturn
    Jan 2025191.2Outturn
    Feb 2025191.2Outturn
    Mar 2025191.1Outturn
    Apr 2025196.8Outturn
    May 2025196.7Outturn
    Jun 2025196.7Outturn
    Jul 2025189.3Outturn
    Aug 2025189.3Outturn
    Sep 2025189.4Outturn
    Oct 2025193.9Outturn
    Nov 2025194.1Outturn
    Dec 2025194.2Outturn
    Jan 2026201.3Outturn
    Feb 2026201.3Outturn
    Mar 2026201.9Outturn
    Apr 2026184.9Outturn
    May 2026185.7Outturn
    Jun 2026186.5Outturn
    Jul 2026193.2Outturn
    Aug 2026194Outturn
    Cash and real terms, the price guarantee, and why Ofgem’s headline figures changed basis.Read the chapter → Is energy still dearer than before the crisis?
  • Why do industrial power costs matter?
    +645.0%2004 Q1–2026 Q2United Kingdom · pence per kWh
    0204019962026
    3.3 → 24.62004 Q1–2026 Q2
    Medium-band industrial electricity prices. Household tariffs use a different measure.
    Sources and data

    "Medium" non-domestic consumer band: 2,000–19,999 MWh/yr for electricity, 2,778–27,777 MWh/yr for gas. Excludes the Climate Change Levy and VAT. DESNZ notes an ongoing revision to the 'Very Small' electricity band from Q4 2024 — does not affect the Medium band used here.

    Source dataset →
    Periodpence per kWhStatus
    2004 Q13.303Outturn
    2004 Q23.304Outturn
    2004 Q33.386Outturn
    2004 Q43.97Outturn
    2005 Q14.274Outturn
    2005 Q24.251Outturn
    2005 Q34.363Outturn
    2005 Q45.525Outturn
    2006 Q15.984Outturn
    2006 Q25.908Outturn
    2006 Q35.85Outturn
    2006 Q46.972Outturn
    2007 Q17.002Outturn
    2007 Q26.227Outturn
    2007 Q36.258Outturn
    2007 Q46.318Outturn
    2008 Q16.366Outturn
    2008 Q26.728Outturn
    2008 Q37.175Outturn
    2008 Q49.227Outturn
    2009 Q18.237Outturn
    2009 Q28.359Outturn
    2009 Q37.984Outturn
    2009 Q47.396Outturn
    2010 Q17.297Outturn
    2010 Q27.115Outturn
    2010 Q37.163Outturn
    2010 Q47.269Outturn
    2011 Q17.456Outturn
    2011 Q27.402Outturn
    2011 Q37.46Outturn
    2011 Q47.989Outturn
    2012 Q18.113Outturn
    2012 Q28.176Outturn
    2012 Q38.275Outturn
    2012 Q48.456Outturn
    2013 Q18.621Outturn
    2013 Q28.823Outturn
    2013 Q38.824Outturn
    2013 Q49.338Outturn
    2014 Q19.456Outturn
    2014 Q29.298Outturn
    2014 Q39.121Outturn
    2014 Q49.521Outturn
    2015 Q19.814Outturn
    2015 Q29.717Outturn
    2015 Q39.748Outturn
    2015 Q49.699Outturn
    2016 Q19.627Outturn
    2016 Q29.267Outturn
    2016 Q39.438Outturn
    2016 Q49.921Outturn
    2017 Q110.062Outturn
    2017 Q29.901Outturn
    2017 Q39.961Outturn
    2017 Q410.395Outturn
    2018 Q110.719Outturn
    2018 Q210.888Outturn
    2018 Q311.034Outturn
    2018 Q411.908Outturn
    2019 Q112.118Outturn
    2019 Q211.248Outturn
    2019 Q311.459Outturn
    2019 Q412.749Outturn
    2020 Q113.094Outturn
    2020 Q212.182Outturn
    2020 Q311.852Outturn
    2020 Q413.017Outturn
    2021 Q113.123Outturn
    2021 Q212.009Outturn
    2021 Q312.35Outturn
    2021 Q416.514Outturn
    2022 Q117.385Outturn
    2022 Q217.746Outturn
    2022 Q320.226Outturn
    2022 Q423.361Outturn
    2023 Q125.296Outturn
    2023 Q228.704Outturn
    2023 Q330.408Outturn
    2023 Q430.094Outturn
    2024 Q130.231Outturn
    2024 Q228.297Outturn
    2024 Q327.568Outturn
    2024 Q426.226Outturn
    2025 Q126.723Outturn
    2025 Q225.264Outturn
    2025 Q324.267Outturn
    2025 Q424.803Outturn
    2026 Q124.458Outturn
    2026 Q224.607Outturn
    Industrial prices, generation and what they mean for growth.Read the chapter → Why do industrial power costs matter?

Evidence → choices → outcomes

What could improve it?

Affordable, reliable energy for households in Great Britain, with less exposure to volatile gas prices.

These options link to their national assessment, including funding, delivery constraints and remaining uncertainties.

  • Assessed option · provisional

    Connect the power Britain needs

    8/10 criteria scored

    Coverage of the appraisal, not an impact score.

    Delivery: Red

    Whole-life costs incomplete

    Evidence and delivery constraints

    Engineering need and queue evidence exist; the marginal effects of queue reform and industrial bill relief are different questions.

    Separate queue management, network reinforcement and industrial levies; identify projects, kit, engineers and regulator decisions.

  • Assessed option · provisional

    Warm homes, inspected before payment

    Health-linked selection, independent inspection before payment and an evaluation inside the Warm Homes grants.

    9/10 criteria scored

    Coverage of the appraisal, not an impact score.

    Delivery: Amber

    Whole-life costs incomplete

    Evidence and delivery constraints

    Energy-saving evidence does not evaluate inspection-before-payment or prove health outcomes for this package.

    Target poor-quality homes; survey suitability/ventilation; use qualified installers and independent inspection; establish redress.

  • Assessed option · provisional

    Utilities: stop overpaying for finance, make failure cost shareholders

    7/10 criteria scored

    Coverage of the appraisal, not an impact score.

    Delivery: Red

    Whole-life costs incomplete

    Evidence and delivery constraints

    Site scenarios are not demonstrated savings. Price controls, insolvency, refinancing and asset ownership have different counterfactuals.

    Separate sectors and instruments; assess legal/regulatory powers, financing, compensation, investment and service quality.

This domain in the UK SWOT →UK National Action Plan →

How we assessed these options

What would it take to improve this?

What would move the needle?

The outcome we want: Affordable, reliable energy for households in Great Britain, with less exposure to volatile gas prices.

The main constraint: Bills are mostly wholesale and network costs that no single reform removes; lowering them for good needs insulated homes and electric heating, which depend on skilled installers, quality checks and a pricing decision by DESNZ and the Treasury about who pays.

Constraint type: workforce, market structure, money, public consent.

The options on the table

What is funded now, and the changes assessed against it — the current baseline and the alternatives, before the position today and the actions.

Provisional single-reviewer assessments from the 6 October 2026 review; not approved business cases, and not government policy.

  • Grid connections and industrial powerDelivery RAG: Red

    Funded now
    Baseline: Ofgem approved the connections reform (Gate 2 firm queue) on 15 April 2025; NESO and the networks are issuing offers (Phase 1 deadline extended to 31 October 2026); Great British Grid was announced on 29 September 2026; industrial price relief (BICS) opens from April 2027. Enforcing the timetable and publishing time to connect as a regular measure is a UK Facts proposal, not government policy.
    The change assessed
    Not yet defined.

    Range if completed: 13.0–19.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))

  • Warm homes, inspected before paymentDelivery RAG: Amber

    Funded now
    The Warm Homes Plan allocates £4,422m of low-income home grants for 2025–26 to 2029–30. The proposal here is targeting by need plus quality assurance, within that programme.
    The change assessed
    Health-linked selection, independent inspection before payment and an evaluation inside the Warm Homes grants.

    Range if completed: 17.0–20.0 out of 30 (equal weights; not yet assessed: incremental affordability (Co))

  • Utilities: stop overpaying for finance, make failure cost shareholdersDelivery RAG: Red

    Funded now
    Not yet stated in the record.
    The change assessed
    Not yet defined.

    Range if completed: 9.0–18.0 out of 30 (equal weights; not yet assessed: increment beyond baseline (Ad), expected incremental benefit (Bn), incremental affordability (Co))

Alternatives already on record: 33 options listed under the points in the position today (23 without an action record), and 4 earlier options under other options compared. They have not been scored in the review.

The position today

  • What we can build on (3)
  • What is holding us back (4)The price cap at typical use is £1,723 a year, against £979 before the 2021 gas surge. (Oct–Dec 2026 (Apr–Sep 2021 comparison) · Great Britain)
  • What could improve things (1)Quality-assured upgrades for the least efficient homes, and electricity prices that reward clean heating, could lower bills and gas exposure together.
  • What could make it worse (2)

Which quadrant a point sits in is our analytical judgement, not a statistical category. Each point says whether it is a measured fact, our synthesis or a risk.

What we can build on Strengths

  • The Warm Homes Plan allocates £4.4bn of grants for low-income homes over five years, within £15bn of public investment.

    Measured factConfidence: High· 2025–26 to 2029–30· England

    Source: Department for Energy Security and Net Zero, Warm Homes Plan (updated 18 March 2026) (Funding allocations table; Chapter 3)

    Options assessed against this point: Warm homes, inspected before payment (Amber delivery RAG)

    What government has committed to

    Funding: The Warm Homes Plan commits £15bn of public investment to upgrade up to 5 million homes by 2030, including £4,422m of low-income homes grants over 2025-26 to 2029-30, and aims to lift up to a million households out of fuel poverty by 2030.

    Who and when:
    Starmer government (to July 2026), 21 January 2026.
    Since 20 July 2026:
    Kept by the Burnham government. Re-stated under Burnham: DESNZ on 27 August 2026 said 'the Warm Homes Plan will help roll out clean technology to millions'; Energy Secretary Fahnbulleh's 1 October 2026 release says 'Our Warm Homes Plan will also lower bills for millions of households and help lift households out of fuel poverty'. No change to the funding table found. Source: HM Treasury, Energy bill tax cut starts today to give families breathing space (Body ('This week the Prime Minister committed to reduce energy costs so that they are in line with other countries in Europe within ten years'; Fahnbulleh quote on £150 removed earlier this year; Warm Homes Plan)).
    Source:
    Department for Energy Security and Net Zero, Warm Homes Plan (updated 18 March 2026) (Executive summary; 'Warm Homes Plan funding allocations (£ millions)' table (low-income homes grants 4,422); 'Support for low-income households'; 'Improving quality and consumer protection'; 'Making electricity cheaper')

    Checked 4 October 2026. A commitment is not delivery.

    Options (3)
    • ShortlistedFix cold and inefficient homes with quality-assured work

      Target the £4.4bn of low-income grants by need and building suitability, with property assessment and post-installation checks.

      Who: DESNZ, councils, housing associations and accredited installers · Evidence: Observational analysis · Status: Funded programme

      Source: Department for Energy Security and Net Zero, Warm Homes Plan (updated 18 March 2026) (Executive summary; 'Warm Homes Plan funding allocations (£ millions)' table (low-income homes grants 4,422); 'Support for low-income households'; 'Improving quality and consumer protection'; 'Making electricity cheaper')

    • Move low-income grants to a single area-based scheme from 2027-28

      Integrating WH:SHF and WH:LG into one area-based programme, coordinated with network operators, aims to reach more fuel-poor homes per pound.

      Who: DESNZ with local authorities and DNOs · Evidence: Untested proposal · Status: Announced proposal

      Source: Department for Energy Security and Net Zero, Warm Homes Plan (updated 18 March 2026) (Executive summary; 'Warm Homes Plan funding allocations (£ millions)' table (low-income homes grants 4,422); 'Support for low-income households'; 'Improving quality and consumer protection'; 'Making electricity cheaper')

    • Evaluate delivery against comparison homes

      Measure gas savings and fuel-poverty exits against similar homes, as the SHDF Wave 1 evaluation did (1,079.9 kWh a year saved; about £97 a year).

      Who: DESNZ (evaluation) · Evidence: Experimental or quasi-experimental evaluation · Status: Site-editorial action

      Source: Department for Energy Security and Net Zero, Social Housing Decarbonisation Fund Wave 1: impact evaluation - report (Executive summary, 'Energy, bill and carbon savings' (1,079.9 kWh gas saved vs comparison homes; £97 a year; only 33% of residents reported lower bills) and 'Resident outcomes')

  • Most policy costs have already moved off bills onto taxation: since April 2026 they are about a tenth of a typical bill.

    Measured factConfidence: High· From April 2026· Great Britain

    Source: UK Energy Research Centre, The Cost of Electricity in the UK: Drivers, Challenges and Opportunities for Reform (UKERC Briefing Paper) (“Bills post-Budget” (p.15))

    What government has committed to

    Funding: From April 2026, 75% of the domestic Renewables Obligation is funded by the Exchequer for 2026-27 to 2028-29 and the Energy Company Obligation ended on 31 March 2026, taking about £150 off a typical bill; the Fuel Poverty Strategy puts the RO shift at £7bn over three years.

    Who and when:
    Starmer government (to July 2026), 26 November 2025.
    Since 20 July 2026:
    Kept by the Burnham government. Acted on and re-stated under Burnham: the RO to Exchequer scheme reported £520.7m of spending for April-June 2026 (10 Sep 2026); Fahnbulleh (1 Oct 2026) cited 'the £150 of costs we removed from bills earlier this year'. Source: Department for Energy Security and Net Zero, The Renewables Obligation to Exchequer Scheme Expenditure: 1 April to 30 June 2026 (Opening paragraphs (scheme in effect 1 Apr 2026, runs 3 years, removes 75% of RO costs); expenditure table (£520,709,288.19 in Q1)).
    Source:
    Department for Energy Security and Net Zero, What does the Autumn Budget mean for your energy bills? ('Where is the saving coming from?' (ECO ends 31 Mar 2026; 75% of RO from general taxation from 1 Apr 2026); 'How did we calculate the £150 cost saving?')

    Checked 4 October 2026. A commitment is not delivery.

    Options (3)
  • Electricity is far cleaner than it was: low-carbon sources generated 64% of UK electricity in 2025, against 25% in 2000; none came from coal in 2025; and each kilowatt-hour supplied carried 147g of CO2 in 2025, against 476g in 2000.

    Measured factConfidence: High· 2000 to 2025· United Kingdom

    Source: Ember, Yearly electricity data (generation by source) (Generation (TWh): Clean; Total generation — United Kingdom); Department for Energy Security and Net Zero, Digest of UK Energy Statistics (DUKES) 2026: Chapter 5 — Electricity (Table 5.6 (coal) and Table 5.14 (carbon intensity))

    What government has committed to

    Target: The Clean Power 2030 Action Plan sets a pathway to a clean power system by 2030.

    Who and when:
    Starmer government (to July 2026), 13 December 2024.
    Since 20 July 2026:
    Not confirmed either way since the change of Prime Minister on 20 July 2026. Burnham-government releases refer to a “transition to clean power” and announced a Great British Grid on 29 September 2026, but none restates 2030 as a dated target; the Prime Minister said in September 2026 that he is determined to reach net zero by 2050 (press reports).

    Checked 4 October 2026. A commitment is not delivery.

    Options (2)
    • Connect built and consented low-carbon generation to the grid faster

      More of the clean power already built reaches customers; the page’s grid-connections option covers the reforms.

      Who: NESO, Ofgem and DESNZ · Evidence: Untested proposal · Status: External proposal

    • More fixed-price contracts, storage and interconnection so gas sets the price less often

      Passes more of the lower running cost of clean power through to bills.

      Who: DESNZ and Ofgem · Evidence: Untested proposal · Status: External proposal

What is holding us back Weaknesses

What could improve things Opportunities

What could make it worse Threats

The actions worth examining

Our shortlist for this page. Research quality, policy status, cost and funding are judged separately; none of these is government policy unless its status says so.Our shortlist. None is government policy unless its status says so.

  1. Fix cold and inefficient homes with quality-assured work — programme funding exists; project allocation unconfirmed
  2. Make electricity pricing support cheaper clean heating — not yet costed / funding not identified
  3. Hold network companies to the reformed connection timetable and publish time to connect — not yet costed / funding not identified
  • Action 1A18Policy status: funded programme

    Fix cold and inefficient homes with quality-assured work

    Target insulation, heating and ventilation at households in greatest need, with a property survey before work and checks after it.

    The thread: issue, evidence, action

    1. Issue Weakness: 9.4% of households in England — about 2.36 million — were in fuel poverty. Also: threat, opportunity, strength
    2. Evidence Households in fuel poverty
    3. Action A18, this action

    Assessment (draft, 6 October review)

    Who decides:
    DESNZ and MHCLG, with councils, landlords and accredited installers (England)
    Evidence:
    Observational analysis. Official before-and-after comparisons show energy savings; the health evidence is an older review with uncertain effects.
    Expected effect:
    −17% median gas use: gas use in homes after solid wall insulation (England and Wales). Observational comparison, mostly from government schemes; savings for cavity and loft insulation are smaller.
    Cost and funding

    £4.42bn in total, 2025–26 to 2029–30, price basis not stated by the source; 1 further cost line, some not yet costed

    Funding: Programme funding exists; project allocation unconfirmed

    Why it is shortlisted here: Lowers the energy a home needs, with funding already allocated; quality assurance is the missing piece.

    What it takes
    The problem

    Cold, inefficient homes push up bills and can harm health, and poor installations can make homes worse.

    Who is affected, and where

    Low-income and fuel-poor households in inefficient homes, in England. Territory: England. Warm Homes Plan grants are England-focused; devolved arrangements were to be set out separately; Scotland and Wales run their own schemes.

    Policy status

    A funded programme already exists. The Warm Homes Plan allocates £4,422m of low-income home grants for 2025–26 to 2029–30. The proposal here is targeting by need plus quality assurance, within that programme.

    The evidence
    What the research found:
    Solid wall insulation cut median gas use by 17% in 2024 for measures installed in 2023 (indicative). The Cochrane review found health improvements “are possible”, clearest where homes were inadequately warm.
    Evaluated on:
    Homes with measures installed under government schemes (energy); people in improved homes in 39 studies (health); England and Wales, 2023–24 (energy); several countries to 2012 (health)
    Our recommendation (separate from the research):
    Select homes by need and suitability, fund surveys and post-installation checks, and measure weather-adjusted use and indoor conditions.
    Strongest counter-evidence:
    Savings vary year to year and include households choosing to heat more; health effects are uncertain and the review is old.
    Effects on record
    • Gas use in homes after solid wall insulation: −17% median gas use (similar homes without measures; 2024 savings for measures installed in 2023; indicative; varies year to year and includes households choosing to heat more). evaluated, moderate confidence; England and Wales. Observational comparison, mostly from government schemes; savings for cavity and loft insulation are smaller.
    • General, respiratory and mental health of residents: Direction plausible; size not established. evaluated, limited confidence; Studies in several countries, searched to 2012. The review says improvements “are possible”, clearest where warmth was inadequate; no current UK estimate and no cashable NHS saving.
    • Low-income households counted as fuel poor: Direction plausible; size not established. plausible spillover, limited confidence; England. The fall in the headline count partly follows from the definition. Whether hardship actually falls depends on real bills, heating behaviour and prices, which the count does not measure.
    • Damp and mould after poorly specified or installed insulation: A cost or harm; size not established. plausible spillover, limited confidence; England. This is why A18 pairs grants with a survey before work and checks after it. No national rate of defects is published in the sources we checked.
    Cost and funding

    Cost completeness: Published programme envelope; project costs still needed. Funding: Programme funding exists; project allocation unconfirmed.

    • Warm Homes Plan: low-income home grants (capital; paid by central government): £4.42bn in total, 2025–26 to 2029–30, price basis not stated by the source. Grant line only; the plan’s loans and financial transactions are different kinds of money and are not included. No price basis stated.
    • Property surveys, installation quality checks, remediation and monitoring (recurring spending; paid by central government, landlords, households): Not yet costed. Use surveyed property-level costs; no invented national average.
    • Warm Homes Plan low-income grant allocations: £4.42bn, 2025–26 to 2029–30 — not committed (programme envelope, not a project award). Programme allocation; an individual home or council scheme is funded only once its award is confirmed.
    Who pays:
    Central government grants; landlords under minimum standards; some households’ own contributions.
    Financing proposed:
    Warm Homes Plan low-income grants; landlord duties.
    Gap remaining:
    Unknown for any scheme until surveyed costs, quality assurance and remediation are priced.
    What delivery needs
    Skills:
    Accredited installers and assessors.
    Operational capacity:
    Council delivery teams.
    Infrastructure:
    None beyond the homes.
    Permissions:
    Landlord and occupant agreement.
    Law:
    Private-rented minimum standards via regulations.
    Public consent:
    Disruption to occupants.
    First step and stages

    First step: Select homes by need and building suitability, then secure the award and installer capacity. (owner: Councils with DESNZ)

    1. Survey — Assessors (proposed stage, not an official timetable)
    2. Install and inspect — Accredited installers; councils (proposed stage, not an official timetable)
    3. Monitor over heating seasons — DESNZ and councils (proposed stage, not an official timetable)

    Depends on: Installer workforce; Quality-assurance regime

    Trade-offs
    Who gains and who loses:
    Gains for low-income households in the least efficient homes; landlords bear costs and may pass some on in rents.
    What else the money or effort could do:
    Grant spent here is not available for other energy or housing programmes.
    Strongest counterargument:
    Savings can be smaller than modelled and poor work can cause damp.
    Risks:
    Poor ventilation, workmanship, rent increases and installer scarcity.
    How we would judge it
    Baseline:
    Fuel poverty rate in England (DESNZ).
    Leading indicator:
    Measures installed, defects found and fixed.
    Outcome:
    Weather-adjusted energy use, indoor conditions, bills and appropriate health outcomes.
    Continue, adapt or stop:
    Scale where measured savings hold after inspection; stop measures that cause defects.
    Earlier option on this page

    This card replaces the option “Insulate and upgrade homes, starting with the least efficient” (funded: Warm Homes Plan: £15bn of public investment over 2025–2030 for up to 5 million homes, including £4.4bn of capital grants for low-income homes. Private rented homes to reach EPC band C by October 2030.). Its evidence: DESNZ’s NEED analysis compares gas use before and after measures with similar homes that had none: for measures installed in 2023, solid wall insulation cut median gas use by 17% in 2024, with smaller savings for cavity wall and loft insulation. DESNZ calls these indicative, mainly from government schemes, and affected by households choosing to heat more once heating is cheaper. DESNZ, National Energy Efficiency Data-Framework (NEED): summary of analysis 2026 (11 June 2026) · DESNZ, Warm Homes Plan (updated 18 March 2026)

    Sources

    Source published March 2026 (Warm Homes Plan); June 2026 (NEED); February 2013 (Cochrane); evidence reviewed 2026-10-04. Reconsider if: Devolved and all-tenure allocations are published; A new UK evaluation of health effects; A new NEED release.

    Also on: Inequality, Hampshire — one shared record, so its cost is counted once.

  • Action 2A17Policy status: external proposal

    Make electricity pricing support cheaper clean heating

    Move remaining levies off electricity onto gas or general taxation, with protection for households who cannot switch, so heat pumps become cheaper to run.

    Assessment (draft, 6 October review)

    Not assessed in the 6 October review; this action stays in the topic plan with its own evidence.

    Who decides:
    DESNZ and HM Treasury, with Ofgem (Great Britain)
    Evidence:
    Modelled scenario. Distributional modelling on 2025 assumptions; outcomes depend on prices, usage and design.
    Expected effect:
    Direction plausible; size not established.
    Cost and funding

    Not yet costed

    Funding: Not yet costed / funding not identified

    Why it is shortlisted here: Decides whether electric heating is cheaper to run than gas — and who pays for the switch.

    Builds on the option Move policy costs and VAT off bills compared below.

    What it takes
    The problem

    Policy costs recovered mainly through electricity bills make electric heating expensive to run relative to gas.

    Who is affected, and where

    Households in Great Britain, especially those heating with electricity or considering a heat pump. Territory: Great Britain. Northern Ireland has a separate electricity market; not assessed.

    Policy status

    Proposed by researchers or others, not government policy. Partly done: since April 2026, 75% of the domestic Renewables Obligation is funded from taxation for 2026–27 to 2028–29. Further rebalancing onto gas is a Nesta proposal, not government policy.

    The evidence
    What the research found:
    Moving Renewables Obligation and Feed-in Tariff levies to gas: about 8 million households pay less, about 19 million gas households pay about £20 a year more, and a typical switcher to a heat pump saves about £400 a year (all before compensation, on 2025 assumptions).
    Evaluated on:
    Ofgem household archetypes; Great Britain, 2025 prices
    Our recommendation (separate from the research):
    Re-run the distributional modelling on the post-April 2026 baseline by heating type and income before choosing a design.
    Strongest counter-evidence:
    After Budget 2025 policy costs are about a tenth of a typical bill, so further rebalancing has less to move; networks are about a third.
    Effects on record
    • Running cost of switching from a gas boiler to a heat pump: Direction plausible; size not established. modelled, limited confidence; Great Britain. Nesta modelled a saving of about £400 a year for a typical switcher, on 2025 prices before 75% of the Renewables Obligation moved to taxation; not re-run on today’s baseline, so no size is shown.
    • Bills of households that stay on gas: A cost or harm; size not established. modelled, limited confidence; Great Britain. Nesta put the rise at about £76 a year for gas households not eligible for support (about £20 for some 19 million households only if other levies also move to taxation, at about £1.1bn a year), modelled on the April 2025 price cap; households that cannot switch — many tenants — bear it. Corrected 4 Oct 2026 (was “about £20 before compensation”).
    Cost and funding

    Cost completeness: Not yet costed. Funding: Not yet costed / funding not identified.

    • Further levy rebalancing from electricity to gas or taxation (bill transfer; paid by bill-payers, central government): Not yet costed. A transfer between bill-payers (or to taxpayers), not a saving. Must be re-costed on the post-April 2026 baseline, after 75% of the Renewables Obligation moved to taxation.
    • Protection for households who cannot switch from gas (bill transfer; paid by bill-payers): Not yet costed. Nesta’s illustrative design: about £126m a year more for the Warm Home Discount core budget (£514m to £640m) and about £310m a year for a unit-rate discount, both levy-funded, at 2025 assumptions. Not re-modelled on the current baseline, so not shown as a cost.
    Who pays:
    Gas bill-payers or taxpayers, depending on the design; compensation from other bill-payers or a budget.
    Financing proposed:
    A transfer between bill-payers or to taxation — not a saving.
    Gap remaining:
    Not costed on the current baseline.
    What delivery needs
    Skills:
    Heat-pump installers for households to respond.
    Operational capacity:
    Supplier billing changes.
    Infrastructure:
    Network capacity for electrified heat.
    Permissions:
    Ofgem licence changes.
    Law:
    Possibly secondary legislation for levy schemes.
    Public consent:
    Gas households facing higher bills.
    First step and stages

    First step: Rerun distributional modelling for different heating types and incomes under current tariffs. (owner: DESNZ with Ofgem)

    1. Model and consult — DESNZ (proposed stage, not an official timetable)
    2. Legislate where needed — Parliament (proposed stage, not an official timetable)
    3. Phase in with compensation — Ofgem and suppliers (proposed stage, not an official timetable)

    Depends on: Installer capacity (A18); Compensation design

    Trade-offs
    Who gains and who loses:
    Gains for electric-heated and switching households; costs for gas households, many of whom — tenants especially — cannot switch.
    What else the money or effort could do:
    If funded from taxation, it competes with other spending.
    Strongest counterargument:
    Raising gas prices hits households who cannot change their heating.
    Risks:
    Unfair cost-shifting and already-enacted changes double-counted in the baseline.
    How we would judge it
    Baseline:
    Electricity-to-gas unit price ratio in the Ofgem cap.
    Leading indicator:
    Heat-pump installations.
    Outcome:
    Bills at matched consumption by heating type, fuel poverty and clean-heat uptake.
    Continue, adapt or stop:
    Continue if uptake rises without higher fuel poverty among gas households; adapt compensation otherwise.
    Sources

    Source published 5 June 2025 (Nesta); 28 July 2026 (UKERC); evidence reviewed 2026-10-04. Reconsider if: The Renewables Obligation arrangement after 2028–29; A new Ofgem cap methodology; Government response on levy rebalancing.

    Also on: Inflation — one shared record, so its cost is counted once.

  • Action 3A56Policy status: external proposal

    Hold network companies to the reformed connection timetable and publish time to connect

    Enforcing the reformed queue’s offer and connection dates, and publishing time to connect, gets ready projects connected sooner; industrial price relief is a separate measure with its own costs.

    Assessment (draft, 6 October review)

    Who decides:
    Ofgem (approves and enforces), the National Energy System Operator and network companies, with DESNZ (Great Britain)
    Evidence:
    Modelled scenario. Only Ofgem’s ex-ante impact assessment exists; no evaluation of the reform’s effect on connection dates or bills has been published.
    Expected effect:
    Direction plausible; size not established.
    Cost and funding

    Not yet costed

    Funding: Not yet costed / funding not identified

    Why it is shortlisted here: The national grid option (Growth list and resilience queue): reform cut the queue, but offers are late and time to connect is not published; enforcing the timetable and reporting it is the bounded change. Industrial price relief is a separate measure, listed with the finding.

    Builds on the option Connect projects to the grid faster compared below.

    What it takes
    The problem

    Connection offers stretched into the 2040s before reform; after it, only 58% of the projects needed for 2030 had offers by June 2026, and Ofgem has twice extended the deadline for the rest, while UK industrial electricity costs far more than in Germany or France.

    Who is affected, and where

    Generation, storage and demand projects in the reformed (Gate 2) connection queue in Great Britain, and the households and firms that pay network costs. Territory: Great Britain. The connections reform covers Great Britain (including Scottish transmission owners); Northern Ireland has its own system operator. The British Industrial Competitiveness Scheme covers Great Britain, with an equivalent scheme funded for Northern Ireland.

    Policy status

    Proposed by researchers or others, not government policy. Baseline: Ofgem approved the connections reform (Gate 2 firm queue) on 15 April 2025; NESO and the networks are issuing offers (Phase 1 deadline extended to 31 October 2026); Great British Grid was announced on 29 September 2026; industrial price relief (BICS) opens from April 2027. Enforcing the timetable and publishing time to connect as a regular measure is a UK Facts proposal, not government policy.

    The evidence
    What the research found:
    Ofgem estimated direct implementation costs under £50m, wasted network works of £220–960m (about £3–£12 per consumer, one-off) and about £5bn of network costs avoided. About 8GW a year connected in the six years to April 2025.
    Evaluated on:
    The pre-reform connection queue; Great Britain, 2025
    Our recommendation (separate from the research):
    Publish offers issued against deadlines and median time to connect each quarter, and use Ofgem’s enforcement powers where network companies miss them.
    Strongest counter-evidence:
    Deadlines have already slipped twice; network reinforcement, not the queue order, may be the binding constraint.
    Cost and funding

    Cost completeness: Not yet costed. Funding: Not yet costed / funding not identified.

      Who pays:
      Electricity bill-payers through network charges; taxpayers for industrial relief (BICS about £600m a year).
      Financing proposed:
      Network allowances set by Ofgem; BICS from energy-system changes and Exchequer money to be scored at the 2026 Budget.
      Gap remaining:
      Unknown: reinforcement capital, its bill impact and Great British Grid’s budget (left to a future spending review).
      What delivery needs
      Skills:
      Network engineers and planners.
      Operational capacity:
      Transmission and distribution construction.
      Infrastructure:
      Network reinforcement.
      Permissions:
      Planning consent for lines and substations (devolved in Scotland and Wales).
      Law:
      None new for enforcement.
      Public consent:
      Local acceptance of new lines.
      First step and stages

      First step: Ofgem requires NESO and network companies to publish offers issued against deadlines and median time to connect for Gate 2 projects each quarter, starting with the 31 October 2026 deadline. (owner: Ofgem with NESO)

      1. Publish offers against deadlines and time to connect — NESO and network companies (proposed stage, not an official timetable)
      2. Enforce missed dates — Ofgem (proposed stage, not an official timetable)
      3. Report capacity connected each year — NESO (proposed stage, not an official timetable)

      Depends on: Network reinforcement; Great British Grid set-up

      Trade-offs
      Who gains and who loses:
      Faster connections help generators, storage and industrial users; network costs are spread across all bill-payers.
      What else the money or effort could do:
      Regulatory attention and network capital diverted from other priorities.
      Strongest counterargument:
      Deadlines without reinforcement may only move delay later.
      Risks:
      Gaming of readiness criteria; bill increases from wasted works.
      How we would judge it
      Baseline:
      June 2026: 713 of 1,223 pre-2030 projects (58%, 37GW) had offers; about 8GW a year connected in the six years to April 2025.
      Leading indicator:
      Offers issued against the 31 October 2026 and 31 January 2027 deadlines.
      Outcome:
      Capacity connected each year and median time to connect.
      Continue, adapt or stop:
      Tighten enforcement where deadlines slip without a network constraint.
      Sources

      Source published 15 April 2025 (Ofgem); 10 June 2026 (NESO); 2 October 2026 (Ofgem); evidence reviewed 2026-10-07. Reconsider if: The Gate 2 Phase 1 deadline (31 October 2026); Great British Grid’s establishment; The Budget on 28 October 2026.

    How the options are assessed

    One shared record per option — the same one the national plan reads. Delivery RAG, gate and list membership are separate judgements.

    • Grid connections and industrial power — Red delivery RAG; gate pending
    • Warm homes, inspected before payment — Amber delivery RAG; gate pending
    • Utilities: stop overpaying for finance, make failure cost shareholders — Red delivery RAG; gate pending

    Provisional single-reviewer assessments from the 6 October 2026 review; not approved business cases, and not government policy.

    • A56Delivery RAG: RedGate: pending

      Grid connections and industrial power

      Existing action A56, assessed at the same scope.

      Provisional single-reviewer assessment; not an approved business case.

      Who and where
      Generation, storage and demand projects in the reformed (Gate 2) connection queue in Great Britain, and the households and firms that pay network costs. (from the action record) Jurisdiction: Great Britain.
      Result so far
      Range if completed: 13.0–19.0 out of 30 (equal weights; not yet assessed: expected incremental benefit (Bn), incremental affordability (Co))
      Funded now (baseline)
      Baseline: Ofgem approved the connections reform (Gate 2 firm queue) on 15 April 2025; NESO and the networks are issuing offers (Phase 1 deadline extended to 31 October 2026); Great British Grid was announced on 29 September 2026; industrial price relief (BICS) opens from April 2027. Enforcing the timetable and publishing time to connect as a regular measure is a UK Facts proposal, not government policy. (from the action record)
      The change assessed (marginal)
      Marginal change not yet defined
      What the evidence supports—and the next decision

      Connection reform, new network assets and industrial bill relief operate through different mechanisms and timescales.

      Codex — AI-assisted analytical follow-up · 8 October 2026. Proposed appraisal design; the attributed scores below are unchanged. No funding or delivery agreement is implied.

      Define the change
      Separate a connection bottleneck from an industrial-price support scheme. For each, name eligible users, the existing settlement and the additional change.
      Test whether it works
      Energised capacity and usable connection dates for networks; additional viable production and energy efficiency for relief. Queue removals alone are not delivered capacity.
      Establish the cost
      Network capital, operations and financing plus any time-limited subsidy. Show incidence on taxpayers and other bill-payers and test expiry of support.
      Protect against harm
      Avoid subsidy commitments that depend on speculative future receipts or crowd out essential connections.

      Read with the outcome evidence and sources in the full assessment. Monitoring proposals are not existing baseline measurements. A numerical benefit or cost score needs evidence for the defined increment, not just the scale of the problem.

      Full assessment of Grid connections and industrial power: ten criteria, scenarios, delivery, costs and monitoring
      The ten criteria (0–3)

      Each criterion is scored 0 to 3 by the reviewer. “Not yet assessed” means unknown: it is never counted as zero.

      1. Scale and severity (Sc)3 of 3 — Severe harm across a broad population

        Reviewer’s reason: Provisional problem-importance judgement from linked site pages; not the scale of achievable benefit.

      2. Increment beyond baseline (Ad)2 of 3 — Specific material change to existing delivery

        Reviewer’s reason: Separate queue management, network reinforcement and industrial levies; identify projects, kit, engineers and regulator decisions. A missing rating requires a defined marginal change.

      3. Confidence in the proposed action (Ev)1 of 3 — Indirect, mixed, modelled or weak causal support

        Reviewer’s reason: Engineering need and queue evidence exist; the marginal effects of queue reform and industrial bill relief are different questions.

      4. Expected incremental benefit (Bn)Not yet assessed

        Reviewer’s reason: Unknown unless a reasonably defined target-population benefit can be judged; no bonus merely for spanning domains.

      5. Residual harms (Hm)1 of 3 — Material harm/unresolved mitigation

        Reviewer’s reason: Binding specialist/kit constraints; moving charges to households; stranded assets.

      6. Incremental affordability (Co)Not yet assessed

        Reviewer’s reason: Capital and operating network costs, financing, bill incidence, relief duration and funding.

      7. Delivery capacity (Ca)1 of 3 — Binding scarce resource

        Reviewer’s reason: Separate queue management, network reinforcement and industrial levies; identify projects, kit, engineers and regulator decisions.

      8. Distribution (Fa)2 of 3 — Mixed or broadly neutral with safeguards

        Reviewer’s reason: Provisional distribution judgement for the stated target; verify who pays, who gains and excluded groups.

      9. Meaningful first outcome (Ti)1 of 3 — More than three but less than ten years

        Reviewer’s reason: First meaningful outcome, not announcement: Time to energisation, reliability and industrial costs; household bill impacts.

      10. Readiness (Rd)2 of 3 — Named commissioning/allocation/coordination step

        Reviewer’s reason: Energy departments, system/network operators and regulators; Split infrastructure and bill-policy appraisal

      Four weightings

      Normalised as 10 × weighted sum ÷ sum of weights, on a 0–30 scale. Where a criterion is not yet assessed, the range is the lowest and highest result if it were later scored 0 or 3 — not a score, a confidence interval or a rank.

      • Equal weights: Range if completed: 13.0–19.0 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
      • Evidence doubled: Range if completed: 12.7–18.2 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
      • Scale doubled: Range if completed: 14.5–20.0 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
      • Cost ignored (the funding gate still applies): Range if completed: 14.4–17.8 out of 30. Not yet assessed: expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.

      Funding gate: Not passed — the cost is not yet assessed or no allocation is committed for this scope. Ignoring cost in a weighting never removes the gate.

      Delivery RAG and gate

      Delivery RAG shown: RedReview’s claim: Red. Best the recorded evidence allows: Red.

      Review’s reason: Binding specialist/kit constraints; moving charges to households; stranded assets.

      Why it is not Green yet

      • Delivery obstacle: Binding specialist/kit constraints; moving charges to households; stranded assets..
      • Scope (population, place and increment) not verified against the delivery baseline.
      • No verified owner with the powers in place.
      • Delivery capacity not verified.
      • Lifetime incremental costs not complete.
      • No credible funding (a committed allocation for the scope).
      • Safeguards not specified.
      • Monitoring lacks a metric, a data source or a baseline.

      Green needs verified scope, a verified owner with the powers, verified capacity, complete lifetime costs with credible funding, specified safeguards and monitoring with a metric, source and baseline. Amber means appraisal gaps remain; Red means a material delivery obstacle. Red does not mean unimportant.

      Gate: Pending — appraisal incomplete (review label: “Pending: incomplete appraisal”).

      Why: Scores incomplete; Funding gate not passed (cost unknown or no credible funding).

      The gate is separate from national list membership: being listed does not make an option eligible, and an eligible option need not be listed.

      Cost and funding

      Lifetime costing: Not established. Review: “Full incremental costing not established in reviewed material”.

      Still to cost: Capital and operating network costs, financing, bill incidence, relief duration and funding.

      Funding status: not identified.

      Owner, powers and capacity

      Proposed owner: Energy departments, system/network operators and regulators (proposed, unverified).

      Powers: needs a decision or allocation. Capacity: binding constraint.

      Powers and capacity read from the review’s Rd and Ca anchors; no proposed owner has agreed to act (the review: “Proposed owners have not agreed to act”).

      England:
      Ofgem (approves and enforces), the National Energy System Operator and network companies, with DESNZ (action record)
      Scotland:
      Ofgem (approves and enforces), the National Energy System Operator and network companies, with DESNZ (action record)
      Wales:
      Ofgem (approves and enforces), the National Energy System Operator and network companies, with DESNZ (action record)
      Northern Ireland:
      not assessed

      The connections reform covers Great Britain (including Scottish transmission owners); Northern Ireland has its own system operator. The British Industrial Competitiveness Scheme covers Great Britain, with an equivalent scheme funded for Northern Ireland.

      Dependencies, safeguards and risks

      Depends on: None recorded.

      Safeguards

      None specified yet.

      Risks and residual harms: Binding specialist/kit constraints; moving charges to households; stranded assets.

      Monitoring and measured results

      Metric: Time to energisation, reliability and industrial costs; household bill impacts.

      Data source: Not yet named. Baseline: Not yet established.

      Measures already on the domain page

      A page measure is not necessarily the review’s metric; linking the two is an editorial decision still to be made.

      Evidence for the outcome

      Outcome: Time to energisation, reliability and industrial costs; household bill impacts.

      Engineering need and queue evidence exist; the marginal effects of queue reform and industrial bill relief are different questions.

      Review record

      Assessment version: working-review-2026-10-06 (A56@working-review-2026-10-06).

      Reviewer: Author of the review blueprint (single reviewer, not named in uk-facts-complete-plan.json). Reviewed: 6 October 2026.

      Scored in the working review of 6 October 2026 on the shared ten-criterion scale (one reviewer); not independently calibrated.

      First 90 days (review): Produce a signed scope and current-delivery baseline; Separate queue management, network reinforcement and industrial levies; identify projects, kit, engineers and regulator decisions. Obtain incremental costs and an accountable decision before expansion.

      Decision route: Split infrastructure and bill-policy appraisal

      An editorial screening framework by one reviewer, not a formal appraisal or business case. Proposed owners have not agreed to act.

    • A18Delivery RAG: AmberGate: pending

      Warm homes, inspected before payment

      Existing action A18, assessed at the same scope.

      Provisional single-reviewer assessment; not an approved business case.

      Who and where
      Low-income and fuel-poor households in inefficient homes, in England. (from the action record) Jurisdiction: England.
      Result so far
      Range if completed: 17.0–20.0 out of 30 (equal weights; not yet assessed: incremental affordability (Co))
      Funded now (baseline)
      The Warm Homes Plan allocates £4,422m of low-income home grants for 2025–26 to 2029–30. The proposal here is targeting by need plus quality assurance, within that programme. (from the action record)
      The change assessed (marginal)
      Health-linked selection, independent inspection before payment and an evaluation inside the Warm Homes grants. (from the superseded 4 October selection table)
      What the evidence supports—and the next decision

      Insulation can reduce energy need, but poor installation can cause damp and costly remediation. Quality control is part of the intervention.

      Codex — AI-assisted analytical follow-up · 8 October 2026. Proposed appraisal design; the attributed scores below are unchanged. No funding or delivery agreement is implied.

      Define the change
      Select homes using health and building-condition criteria; compare independently inspected upgrades with the funded baseline.
      Test whether it works
      Weather-adjusted energy use, comfort, damp, health and defects; measure rebound and follow homes beyond installation.
      Establish the cost
      Assessment, works, ventilation, inspection, remediation, maintenance and administration. Do not count grants as both a cost and a resource saving.
      Protect against harm
      Require whole-building suitability, tenant protection and enforceable defect repair before payment.

      Read with the outcome evidence and sources in the full assessment. Monitoring proposals are not existing baseline measurements. A numerical benefit or cost score needs evidence for the defined increment, not just the scale of the problem.

      Full assessment of Warm homes, inspected before payment: ten criteria, scenarios, delivery, costs and monitoring
      The ten criteria (0–3)

      Each criterion is scored 0 to 3 by the reviewer. “Not yet assessed” means unknown: it is never counted as zero.

      1. Scale and severity (Sc)3 of 3 — Severe harm across a broad population

        Reviewer’s reason: Provisional problem-importance judgement from linked site pages; not the scale of achievable benefit.

      2. Increment beyond baseline (Ad)2 of 3 — Specific material change to existing delivery

        Reviewer’s reason: Target poor-quality homes; survey suitability/ventilation; use qualified installers and independent inspection; establish redress. A missing rating requires a defined marginal change.

      3. Confidence in the proposed action (Ev)1 of 3 — Indirect, mixed, modelled or weak causal support

        Reviewer’s reason: Energy-saving evidence does not evaluate inspection-before-payment or prove health outcomes for this package.

      4. Expected incremental benefit (Bn)2 of 3 — Material for the target population

        Reviewer’s reason: Unknown unless a reasonably defined target-population benefit can be judged; no bonus merely for spanning domains.

        Reason and score disagree — under review

      5. Residual harms (Hm)1 of 3 — Material harm/unresolved mitigation

        Reviewer’s reason: Damp, overheating, defects and installer constraints; inspection is not a guarantee.

      6. Incremental affordability (Co)Not yet assessed

        Reviewer’s reason: Works, assessment, inspection, maintenance, remediation and administration against existing grants.

      7. Delivery capacity (Ca)1 of 3 — Binding scarce resource

        Reviewer’s reason: Target poor-quality homes; survey suitability/ventilation; use qualified installers and independent inspection; establish redress.

      8. Distribution (Fa)3 of 3 — Benefits concentrated on disadvantaged people with assessed burdens

        Reviewer’s reason: Provisional distribution judgement for the stated target; verify who pays, who gains and excluded groups.

      9. Meaningful first outcome (Ti)2 of 3 — More than one and up to three years

        Reviewer’s reason: First meaningful outcome, not announcement: Measured energy use, comfort, health and defects; household costs.

      10. Readiness (Rd)2 of 3 — Named commissioning/allocation/coordination step

        Reviewer’s reason: Energy/housing departments, councils and installers; Quality-assured targeted delivery

      Four weightings

      Normalised as 10 × weighted sum ÷ sum of weights, on a 0–30 scale. Where a criterion is not yet assessed, the range is the lowest and highest result if it were later scored 0 or 3 — not a score, a confidence interval or a rank.

      • Equal weights: Range if completed: 17.0–20.0 out of 30. Not yet assessed: incremental affordability (Co). Funding gate: not passed.
      • Evidence doubled: Range if completed: 16.4–19.1 out of 30. Not yet assessed: incremental affordability (Co). Funding gate: not passed.
      • Scale doubled: Range if completed: 18.2–20.9 out of 30. Not yet assessed: incremental affordability (Co). Funding gate: not passed.
      • Cost ignored (the funding gate still applies): Range if completed: 18.9–18.9 out of 30. Not yet assessed: incremental affordability (Co). The missing criteria carry no weight here, so the ends meet; the record is still incomplete. Funding gate: not passed.

      Funding gate: Not passed — the cost is not yet assessed or no allocation is committed for this scope. Ignoring cost in a weighting never removes the gate.

      Delivery RAG and gate

      Delivery RAG shown: AmberReview’s claim: Amber. Best the recorded evidence allows: Amber.

      Review’s reason: Works, assessment, inspection, maintenance, remediation and administration against existing grants.

      Why it is not Green yet

      • Scope (population, place and increment) not verified against the delivery baseline.
      • No verified owner with the powers in place.
      • Delivery capacity not verified.
      • Lifetime incremental costs not complete.
      • No credible funding (a committed allocation for the scope).
      • Safeguards not specified.
      • Monitoring lacks a metric, a data source or a baseline.

      Green needs verified scope, a verified owner with the powers, verified capacity, complete lifetime costs with credible funding, specified safeguards and monitoring with a metric, source and baseline. Amber means appraisal gaps remain; Red means a material delivery obstacle. Red does not mean unimportant.

      Gate: Pending — appraisal incomplete (review label: “Pending: incomplete appraisal”).

      Why: Scores incomplete; Funding gate not passed (cost unknown or no credible funding).

      The gate is separate from national list membership: being listed does not make an option eligible, and an eligible option need not be listed.

      Cost and funding

      Lifetime costing: Partial — some lines costed, no whole-life total. Review: “Full incremental costing not established in reviewed material”.

      • Warm Homes Plan: low-income home grants (published programme envelope; C-WHP-LOWINCOME)
      • Property surveys, installation quality checks, remediation and monitoring (not costed; C-A18-QUALITY)

      Still to cost: Works, assessment, inspection, maintenance, remediation and administration against existing grants.

      Funding status: programme route, not allocated.

      Owner, powers and capacity

      Proposed owner: Energy/housing departments, councils and installers (proposed, unverified).

      Powers: needs a decision or allocation. Capacity: binding constraint.

      Powers and capacity read from the review’s Rd and Ca anchors; no proposed owner has agreed to act (the review: “Proposed owners have not agreed to act”).

      England:
      DESNZ and MHCLG, with councils, landlords and accredited installers (action record)
      Scotland:
      not assessed
      Wales:
      not assessed
      Northern Ireland:
      not assessed

      Warm Homes Plan grants are England-focused; devolved arrangements were to be set out separately; Scotland and Wales run their own schemes.

      Dependencies, safeguards and risks

      Depends on: None recorded.

      Safeguards

      None specified yet.

      Risks and residual harms: Damp, overheating, defects and installer constraints; inspection is not a guarantee.

      Monitoring and measured results

      Metric: Measured energy use, comfort, health and defects; household costs.

      Data source: Not yet named. Baseline: Not yet established.

      Measures already on the domain page

      A page measure is not necessarily the review’s metric; linking the two is an editorial decision still to be made.

      Evidence for the outcome

      Outcome: Measured energy use, comfort, health and defects; household costs.

      Energy-saving evidence does not evaluate inspection-before-payment or prove health outcomes for this package.

      Effect records for this action

      • Gas use in homes after solid wall insulation: −17% median gas use (evaluated, moderate confidence; England and Wales)
      • General, respiratory and mental health of residents: size not established (evaluated, limited confidence; Studies in several countries, searched to 2012)
      • Low-income households counted as fuel poor: size not established (plausible spillover, limited confidence; England)
      • Damp and mould after poorly specified or installed insulation: size not established (plausible spillover, limited confidence; England)
      Review record

      Assessment version: working-review-2026-10-06 (A18@working-review-2026-10-06).

      Reviewer: Author of the review blueprint (single reviewer, not named in uk-facts-complete-plan.json). Reviewed: 6 October 2026.

      Scored in the working review of 6 October 2026 on the shared ten-criterion scale (one reviewer); not independently calibrated.

      First 90 days (review): Produce a signed scope and current-delivery baseline; Target poor-quality homes; survey suitability/ventilation; use qualified installers and independent inspection; establish redress. Obtain incremental costs and an accountable decision before expansion.

      Decision route: Quality-assured targeted delivery

      An earlier assessment exists on the 4 October 2026 selection table (nine H/M/L bands; superseded 7 October 2026). Its bands are kept, not converted into these scores.

      An editorial screening framework by one reviewer, not a formal appraisal or business case. Proposed owners have not agreed to act.

    • A64Delivery RAG: RedGate: pending

      Utilities: stop overpaying for finance, make failure cost shareholders

      Proposed new action A64; sourced research home and appraisal design; scope and funding remain provisional.

      Provisional single-reviewer assessment; not an approved business case.

      Who and where
      Population not yet defined. Jurisdiction: not defined.
      Result so far
      Range if completed: 9.0–18.0 out of 30 (equal weights; not yet assessed: increment beyond baseline (Ad), expected incremental benefit (Bn), incremental affordability (Co))
      Funded now (baseline)
      Funded baseline not yet stated
      The change assessed (marginal)
      Marginal change not yet defined
      What the evidence supports—and the next decision

      A lower financing rate is only one part of utility value. Acquisition terms, investment needs and risk transfer can reverse the result.

      Codex — AI-assisted analytical follow-up · 8 October 2026. Proposed appraisal design; the attributed scores below are unchanged. No funding or delivery agreement is implied.

      Define the change
      Compare regulation, restructuring and acquisition for a specified network against its current settlement and service obligations.
      Test whether it works
      Reliability, investment delivery, environmental performance and total bills; stress finance costs, purchase premium and asset-condition uncertainty.
      Establish the cost
      Acquisition, debt, capital renewal, operations and contingent liabilities. Keep financing transfers distinct from real efficiency gains.
      Protect against harm
      Preserve service continuity and consumer protection; do not present one spreadsheet scenario as an observed saving.

      Read with the outcome evidence and sources in the full assessment. Monitoring proposals are not existing baseline measurements. A numerical benefit or cost score needs evidence for the defined increment, not just the scale of the problem.

      Full assessment of Utilities: stop overpaying for finance, make failure cost shareholders: ten criteria, scenarios, delivery, costs and monitoring
      The ten criteria (0–3)

      Each criterion is scored 0 to 3 by the reviewer. “Not yet assessed” means unknown: it is never counted as zero.

      1. Scale and severity (Sc)2 of 3 — Serious harm to a defined group or widespread moderate harm

        Reviewer’s reason: Provisional problem-importance judgement from linked site pages; not the scale of achievable benefit.

      2. Increment beyond baseline (Ad)Not yet assessed

        Reviewer’s reason: Separate sectors and instruments; assess legal/regulatory powers, financing, compensation, investment and service quality. A missing rating requires a defined marginal change.

      3. Confidence in the proposed action (Ev)1 of 3 — Indirect, mixed, modelled or weak causal support

        Reviewer’s reason: Site scenarios are not demonstrated savings. Price controls, insolvency, refinancing and asset ownership have different counterfactuals.

      4. Expected incremental benefit (Bn)Not yet assessed

        Reviewer’s reason: Unknown unless a reasonably defined target-population benefit can be judged; no bonus merely for spanning domains.

      5. Residual harms (Hm)1 of 3 — Material harm/unresolved mitigation

        Reviewer’s reason: Underinvestment, legal disputes and transferred taxpayer risk; no additive headline saving.

      6. Incremental affordability (Co)Not yet assessed

        Reviewer’s reason: Acquisition/compensation, debt, financing, capital maintenance, contingent liabilities and consumer bills under each option.

      7. Delivery capacity (Ca)1 of 3 — Binding scarce resource

        Reviewer’s reason: Separate sectors and instruments; assess legal/regulatory powers, financing, compensation, investment and service quality.

      8. Distribution (Fa)2 of 3 — Mixed or broadly neutral with safeguards

        Reviewer’s reason: Provisional distribution judgement for the stated target; verify who pays, who gains and excluded groups.

      9. Meaningful first outcome (Ti)1 of 3 — More than three but less than ten years

        Reviewer’s reason: First meaningful outcome, not announcement: Whole-life customer costs, reliability, investment and taxpayer exposure.

      10. Readiness (Rd)1 of 3 — Legislation/external agreement or major enabling work

        Reviewer’s reason: Sector regulators, Treasury, relevant departments and infrastructure bodies; Split regulatory and ownership options

      Four weightings

      Normalised as 10 × weighted sum ÷ sum of weights, on a 0–30 scale. Where a criterion is not yet assessed, the range is the lowest and highest result if it were later scored 0 or 3 — not a score, a confidence interval or a rank.

      • Equal weights: Range if completed: 9.0–18.0 out of 30. Not yet assessed: increment beyond baseline (Ad), expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
      • Evidence doubled: Range if completed: 9.1–17.3 out of 30. Not yet assessed: increment beyond baseline (Ad), expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
      • Scale doubled: Range if completed: 10.0–18.2 out of 30. Not yet assessed: increment beyond baseline (Ad), expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.
      • Cost ignored (the funding gate still applies): Range if completed: 10.0–16.7 out of 30. Not yet assessed: increment beyond baseline (Ad), expected incremental benefit (Bn), incremental affordability (Co). Funding gate: not passed.

      Funding gate: Not passed — the cost is not yet assessed or no allocation is committed for this scope. Ignoring cost in a weighting never removes the gate.

      Delivery RAG and gate

      Delivery RAG shown: RedReview’s claim: Red. Best the recorded evidence allows: Red.

      Review’s reason: Underinvestment, legal disputes and transferred taxpayer risk; no additive headline saving.

      Why it is not Green yet

      • Delivery obstacle: Underinvestment, legal disputes and transferred taxpayer risk; no additive headline saving..
      • Scope (population, place and increment) not verified against the delivery baseline.
      • No verified owner with the powers in place.
      • Delivery capacity not verified.
      • Lifetime incremental costs not complete.
      • No credible funding (a committed allocation for the scope).
      • Safeguards not specified.
      • Monitoring lacks a metric, a data source or a baseline.

      Green needs verified scope, a verified owner with the powers, verified capacity, complete lifetime costs with credible funding, specified safeguards and monitoring with a metric, source and baseline. Amber means appraisal gaps remain; Red means a material delivery obstacle. Red does not mean unimportant.

      Gate: Pending — appraisal incomplete (review label: “Pending: incomplete appraisal”).

      Why: Scores incomplete; Funding gate not passed (cost unknown or no credible funding).

      The gate is separate from national list membership: being listed does not make an option eligible, and an eligible option need not be listed.

      Cost and funding

      Lifetime costing: Not established. Review: “Full incremental costing not established in reviewed material”.

      Still to cost: Acquisition/compensation, debt, financing, capital maintenance, contingent liabilities and consumer bills under each option.

      Funding status: not established in review.

      Owner, powers and capacity

      Proposed owner: Sector regulators, Treasury, relevant departments and infrastructure bodies (proposed, unverified).

      Powers: needs legislation or external agreement. Capacity: binding constraint.

      Powers and capacity read from the review’s Rd and Ca anchors; no proposed owner has agreed to act (the review: “Proposed owners have not agreed to act”).

      England:
      not assessed
      Scotland:
      not assessed
      Wales:
      not assessed
      Northern Ireland:
      not assessed

      Not defined in the review.

      Dependencies, safeguards and risks

      Depends on: None recorded.

      Safeguards

      None specified yet.

      Risks and residual harms: Underinvestment, legal disputes and transferred taxpayer risk; no additive headline saving.

      Monitoring and measured results

      Metric: Whole-life customer costs, reliability, investment and taxpayer exposure.

      Data source: Not yet named. Baseline: Not yet established.

      Evidence for the outcome

      Outcome: Whole-life customer costs, reliability, investment and taxpayer exposure.

      Site scenarios are not demonstrated savings. Price controls, insolvency, refinancing and asset ownership have different counterfactuals.

      Review record

      Assessment version: working-review-2026-10-06 (A64@working-review-2026-10-06).

      Reviewer: Author of the review blueprint (single reviewer, not named in uk-facts-complete-plan.json). Reviewed: 6 October 2026.

      Scored in the working review of 6 October 2026 on the shared ten-criterion scale (one reviewer); not independently calibrated.

      First 90 days (review): Produce a signed scope and current-delivery baseline; Separate sectors and instruments; assess legal/regulatory powers, financing, compensation, investment and service quality. Obtain incremental costs and an accountable decision before expansion.

      Decision route: Split regulatory and ownership options

      An editorial screening framework by one reviewer, not a formal appraisal or business case. Proposed owners have not agreed to act.

    Decision brief

    • Fix the coldest homes first — and measure bills and health separately

    The leading option set out as a decision someone could take: who decides, who benefits, the best evidence, cost and funding, and the main trade-off. The full research record is one click away.

    Decision briefExisting programmeReviewed 2026-10-04

    Fix the coldest homes first — and measure bills and health separately

    Decision required
    Whether DESNZ adds independent inspection before final payment to the low-income grant rules, and councils with health partners agree referral routes so homes are chosen by health need as well as income.
    Who and where
    Low-income households in homes rated EPC D to G, prioritising those with health conditions made worse by cold. Applies in: England.
    Accountable body
    Department for Energy Security and Net Zero
    Intervention
    Survey, then install insulation, heating and ventilation together in the coldest homes chosen by need, and inspect before final payment.
    Best evidence, and where it applies
    Solid wall insulation cut median gas use by 17% (England and Wales); a New Zealand randomised trial found insulation halved the odds of poor self-rated health in homes with respiratory illness.Studied in: Homes in England and Wales with measures installed, mostly under government schemes (2024 savings for measures installed in 2023).How closely the comparison transfers to this decision: Seven low-income communities, New Zealand — partial.
    Extra cost of this change
    Capital: Warm Homes low-income grants — £4.42bn in total, 2025–26 to 2029–30, price basis not stated by the source; Energy performance upgrades per home (average cap) — £16,600 per home (average across a project).Recurring: Administration and ancillary costs — Up to 15% of total project spend; Surveys, independent inspection, remediation and monitoring — Not yet costed.One-off or mixed: Linked health and energy evaluation — not yet established.
    Funding
    Not funded yet: a possible funding route exists, but nothing is allocated to this change.Committed to this change: none.Possible source, not an award: Warm Homes Plan low-income grant allocations (£4.42bn).Unfunded: Inspection, remediation and evaluation costs are not established; the £4.4bn is a programme envelope, not an award to this change.
    Savings and wider benefits
    Not yet specified: no cashable saving or avoided cost has been costed for this change. Expected outcomes are listed one by one in the research appendix and are never added together or counted as money available.
    First 90-day step
    Inspection and remediation standard in scheme rules; first health-referred homes surveyed.The proposed first milestone; a 90-day date is not yet specified. Owner: DESNZ with councils. Proposed by UK Facts, not an official deadline.
    Twelve-month milestone
    Not yet specified.Time to a first useful result: Warmth and energy use after one heating season; health outcomes after two.
    Outcome, and when to scale or stop
    Measure: Inspections passed first time and defects remedied.Scale if: Measured savings and warmth hold after inspection.Stop if: A measure causes defects; stop that measure.
    Main trade-off
    Installers and grant money spent here are not available for other work, and poor installation can cause damp.

    An editorial proposal by UK Facts for discussion, not government policy. Records: A18 · effects E-A18-GAS-USE, E-A18-HEALTH, E-A18-DAMP · costs C-WHP-LOWINCOME, C-A18-QUALITY

    Research appendix: study design, effect sizes and limits, alternatives, full costing, international comparisons and how we would know

    1.The change, in plain words

    Fix the coldest homes first — and measure bills and health separately

    2.The decision requested

    Decision
    Add independent post-installation inspection, with retained final payment and a remediation route, to Warm Homes grant rules; in a first set of councils, select eligible homes through GP or respiratory-service referral and evaluate warmth, energy use, bills and health separately against a comparison.
    Accountable institution
    Department for Energy Security and Net Zero
    Geography
    England
    Powers
    Existing scheme rules and grant conditions; no new law.
    Delivery partners
    Councils and Warm Homes: Local Grant consortia; NHS primary care and respiratory services; Retrofit coordinators, TrustMark installers and independent inspectors; Landlords

    3.Who it is for, and what changes beyond today

    Target population
    Low-income households in homes rated EPC D to G, prioritising those with health conditions made worse by cold.
    Eligibility
    Warm Homes: Local Grant eligibility (for example gross household income of £36,000 or less), plus health referral for priority.
    Scale
    Set from local need, installer capacity and a costed business case; WH:LG has allocated funding to 74 projects involving 271 councils.
    Baseline
    About 9.4% of households in England were fuel poor in 2025. Under WH:LG, about 1,980 households were reported upgraded by the end of April 2026 (provisional; DESNZ says this undercounts).

    Source: Department for Energy Security and Net Zero, Annual Fuel Poverty Statistics in England, 2026 (2025 data) (Report p.1); Department for Energy Security and Net Zero, Warm Homes: Local Grant statistics – May 2026 (Key statistics)

    Change beyond existing law or funding
    Scheme rules already require PAS 2035 and TrustMark installers; the change adds health-linked selection, independent inspection before final payment, a remediation route and an evaluation that measures health separately.

    4.How it would work

    Do: Survey, then install insulation, heating and ventilation together in the coldest homes chosen by need, and inspect before final payment. Changing: Warmer, drier homes that need less energy to heat.

    • Gas use after solid wall insulation

      Measured for this interventionEffect record E-A18-GAS-USE

      Median −17% in England and Wales (observational, indicative).

    • Residents’ health

      Hypothesis to testEffect record E-A18-HEALTH

      Measured in New Zealand homes for a population chosen for respiratory illness; a hypothesis for English homes until evaluated.

    • Damp and mould after poor installation

      Hypothesis to testEffect record E-A18-DAMP

      A risk the inspection is meant to catch; no national defect rate is published.

    Outcomes are kept separate and never added into one impact figure.

    5.Best evidence

    • National Energy Efficiency Data-Framework (NEED): summary of analysis 2026

      Author or institution:
      Department for Energy Security and Net Zero
      Published:
      June 2026
      Evaluation period:
      2024 savings for measures installed in 2023
      Design:
      Observational comparison of metered gas use in homes with and without measures
      Sample or population:
      Homes in England and Wales with measures installed, mostly under government schemes
      Effect and uncertainty:
      Median gas saving 17% after solid wall insulation; indicative and varies between years
      Limits:
      Not randomised; includes households choosing to heat more

      Where: Section 3, Figure 3.1. Affiliation is provenance, not proof of quality.

    • Effect of insulating existing houses on health inequality: cluster randomised study in the community

      Author or institution:
      Howden-Chapman P et al. (University of Otago)
      Published:
      March 2007
      Evaluation period:
      Winters of 2001 and 2002
      Design:
      Cluster randomised, single-blinded
      Sample or population:
      1,350 low-income New Zealand households with a member with respiratory symptoms
      Effect and uncertainty:
      Fair/poor self-rated health OR 0.50 (0.38 to 0.68); GP visits 0.73 (0.62 to 0.87); respiratory admissions 0.53 (0.22 to 1.29), not significant
      Limits:
      Different housing stock and climate; self-reported outcomes

      Where: Abstract; Methods. Affiliation is provenance, not proof of quality.

    6.Alternatives, counter-evidence and who loses

    Closest feasible alternative
    Rebalancing electricity and gas prices to favour clean heating (A17): cheaper for government but modelled on an overtaken baseline and raises bills for households that cannot switch.
    Strongest counter-evidence
    The Cochrane review found health improvements only “possible”, clearest where warmth was inadequate; savings vary year to year.

    Source: Cochrane / Hilary Thomson and colleagues, Housing improvements for health and associated socio-economic outcomes (Cochrane Review CD008657); plain-language title 'Housing improvement as an investment to improve health' (Abstract: main results and authors’ conclusions); Department for Energy Security and Net Zero, National Energy Efficiency Data-Framework (NEED): summary of analysis 2026 (Section 3)

    Distributional effects
    Gains for low-income households in the least efficient homes; private landlords contribute after the first home and may pass costs on in rents.
    Main downside
    Scarce installers diverted from other work, and damp if work is poor — which is why inspection comes before payment.

    The options compared, including current policy

    • The proposal

      Health-linked selection, inspection before payment, separate measures

      Who is reached
      Low-income households in the coldest homes with health needs
      Evidence
      Observational energy savings; NZ RCT for health
      Likely outcome and timing
      Warmer homes and lower use in a heating season; health a hypothesis
      Cost and funding
      Within the grant; inspection and evaluation not costed
      Main trade-off
      Installer capacity; fewer homes if inspection costs more
    • Current policy

      Current policy: Warm Homes grants as run

      Who is reached
      Low-income households in EPC D–G homes
      Evidence
      PAS 2035 standards; no linked evaluation
      Likely outcome and timing
      Energy savings; health unmeasured
      Cost and funding
      £4.4bn envelope to 2029–30
      Main trade-off
      No health targeting or independent check before payment
    • Alternative

      Rebalance energy prices instead

      Who is reached
      Electricity-heated households
      Evidence
      Modelled on an overtaken baseline
      Likely outcome and timing
      Lower electricity bills
      Cost and funding
      Bill or tax transfer
      Main trade-off
      Higher gas bills for those who cannot switch

    7.What other countries or the devolved nations show

    Country lesson · Seven low-income communities, New Zealand, Winters of 2001 and 2002

    Insulating cold, damp homes in New Zealand

    Evidence: Experimental or quasi-experimental evaluationPartial match: some conditions differ

    What was changed
    A free, standard retrofit package to government specification — ceiling insulation, draught stopping round windows and doors, insulating paper under floors and a polythene moisture barrier on the ground — installed by trained community teams.
    Study design and population
    Community-based cluster randomised study, single-blinded (inspectors and interviewers did not know which homes were insulated). 1,350 uninsulated households (4,407 people) where at least one member had respiratory symptoms; two thirds in the three most deprived tenths of areas.
    Measured outcome there
    Warmer, drier homes (bedrooms +0.5°C; humidity −2.3%) while using 81% of the energy of uninsulated homes. Odds of fair or poor self-rated health halved (OR 0.50, 0.38 to 0.68); fewer children off school (0.49) and adults off work (0.62); fewer GP visits (0.73).
    Cost status
    Historic only: about £700 a house excluding taxes at 2001 prices — not a guide to current English costs.
    What failed or remains uncertain
    Respiratory hospital admissions fell but not significantly (OR 0.53, 0.22 to 1.29); most outcomes were self-reported by occupants who knew their homes were insulated; temperature gains were small and partly taken as lower energy use.
    Why the UK differs
    English stock is largely brick and solid-wall, much already has loft insulation, and the climate is colder; English schemes treat whole homes under PAS 2035 at much higher cost. The trial chose households with respiratory illness, so health gains for a general fuel-poor population are less certain.
    First change required here
    Select homes by health need as well as income and energy rating — for example through GP or respiratory-service referral — and measure warmth, energy use, bills and health separately against a comparison group.

    Not a UK forecast: the effect above was measured in that place and population. Source: BMJ, Effect of insulating existing houses on health inequality: cluster randomised study in the community (Abstract; Methods; Discussion). Reviewed 2026-10-04.

    8.What delivery needs first

    • staff — TrustMark installers, retrofit coordinators and independent inspectors. (Scarce resource shared with other priorities; owner: DESNZ, accreditation bodies and Skills England)
    • data — A health referral route and consent to link health outcomes for the evaluation. (Requirement; owner: Councils with integrated care boards)
    • dependency — Installer demand sequenced with housebuilding and infrastructure (NP5). (Scarce resource shared with other priorities; owner: NISTA with DESNZ)

    9.What it would cost

    How the cost is built up: Surveys + eligible homes × installed package (within the average caps) + ventilation and remediation + programme staff (within the 15% allowance) + independent inspection + evaluation + contingency.

    • Warm Homes low-income grants

      England

      £4.42bn in total, 2025–26 to 2029–30, price basis not stated by the source (ledger C-WHP-LOWINCOME)

      capital; price year not stated; 2025–26 to 2029–30; Current quoted cost

      The existing envelope; homes are funded only once awards are confirmed.

    • Energy performance upgrades per home (average cap)

      Per home under Warm Homes: Local Grant

      £16,600 per home (average across a project)

      capital; 2026 prices; April 2025 to March 2028; Current quoted cost

      A published maximum average grant, not a measured cost; a separate £16,600 average cap applies to low-carbon heating.

      Source: Department for Energy Security and Net Zero, Warm Homes: Local Grant – policy guidance for local authorities (updated June/July 2026) (Section 6.1, Table 8)

    • Administration and ancillary costs

      Per WH:LG project

      Not yet established share of project spend (range Up to 15% of total project spend)

      recurring; price year not stated; Project lifetime; Not yet established

      Source: Department for Energy Security and Net Zero, Warm Homes: Local Grant – policy guidance for local authorities (updated June/July 2026) (Summary table (A&A budget))

    • Surveys, independent inspection, remediation and monitoring

      Homes selected by need

      Not yet costed (ledger C-A18-QUALITY)

      recurring; price year not stated; From the first awards; Not yet established

    • Linked health and energy evaluation

      First set of councils

      Not yet established per evaluation

      one-off revenue; price year not stated; Two heating seasons; Not yet established

    10.Who pays, and what is missing

    Programme envelope (a possible route, not an award)
    Warm Homes Plan low-income grant allocations: £4.42bn, 2025–26 to 2029–30
    Allocation committed to this change
    None
    Remaining gap
    Inspection, remediation and evaluation costs are not established; the £4.4bn is a programme envelope, not an award to this change.
    Proposed financing
    Warm Homes low-income grants (including the administration allowance) for installation and inspection; a DESNZ or NIHR evaluation budget for the health study.
    Responsible payer
    central government, landlords
    Budget displaced
    Other homes the same grant could treat; installer time for other work.

    11.First milestone and time to a useful result

    Inspection and remediation standard in scheme rules; first health-referred homes surveyed. (Owner: DESNZ with councils. Proposed by UK Facts, not an official deadline.)

    Time to first useful result: Warmth and energy use after one heating season; health outcomes after two.

    What could delay it: Installer and inspector capacity is available. Health data can be linked lawfully. Delivery under the local grant speeds up (it has been slow to report).

    12.How we would know

    Baseline
    Indoor temperature, weather-adjusted energy use, bills and health of selected households before work.
    Comparison
    Eligible homes treated later (a phased or waiting-list comparison).
    Leading indicator
    Inspections passed first time and defects remedied.
    Follow-up
    Two heating seasons after installation.
    Continue if
    Measured savings and warmth hold after inspection.
    Adapt if
    Defect rates are high or savings fall well below survey estimates.
    Stop if
    A measure causes defects; stop that measure.
    Thresholds
    Not yet set: Set before launch once power, budget and baseline are known, from the business case and evaluation design.

    What is not yet known, and how to find out

    • What would independent inspection and remediation cost per home? (cost)Next step: Obtain current quotes and label the price year.Scope: Inspection, remediation and monitoring per home · Data or quotes needed: Quotes from inspectors and retrofit coordinators; defect rates from scheme data · Who can estimate it: DESNZ with councils and TrustMark
    • Do health gains appear in English homes? (effect)Next step: A phased, health-linked evaluation in the first councils.Defensible route: bounded pilot

    Sources last checked 4 October 2026 · Owner: Evidence editor (James Harris) · Next check: DESNZ Warm Homes: Local Grant statistics, October 2026 (26 November 2026) or the first trigger: DESNZ annual fuel poverty statistics for England (usually published early in the year; date not announced when reviewed).

    More decision briefs on other pages

    What it would take

    The order things have to happen in, who pays, and the effects and appraisals on record.

    The order things have to happen in

    1. First, the prerequisite

      Survey homes; rerun levy modelling on the post-April 2026 baseline

      Owner: Councils and assessors; DESNZ

      No date: the timing depends on the steps before it.

    2. Then, the decision

      Award grants to named schemes; decide the levy design and compensation

      Owner: DESNZ and HM Treasury

      No date: the timing depends on the steps before it.

    3. Then, delivery

      Install, inspect and fix defects; phase in pricing with protection

      Owner: Accredited installers; Ofgem and suppliers

      No date: the timing depends on the steps before it.

    4. Finally, the measured outcome

      Lower weather-adjusted energy use and fuel poverty

      Owner: DESNZ statistics

      No date: the timing depends on the steps before it.

    5. Then, delivery

      Issue Gate 2 connection offers (Phase 1 deadline extended to 31 October 2026)

      Owner: NESO and network companies

      31 October 2026 (Ofgem letter, 2 October 2026) — source

    Who pays, and what is still missing

    Cost, committed funding and the remaining gap for the same scope and years. A programme envelope is not an award to a project; a proposal is not committed money. No total is shown because these costs are on different bases or periods and cannot be added.

    Cost and funding ledger

    • Warm Homes Plan: low-income home grants

      A18 · capital · published programme envelope

      Amount
      £4.42bn in total, 2025–26 to 2029–30, price basis not stated by the source
      Who pays
      central government
      Committed
      None identified
      Proposed, not committed
      £4.42bn (Warm Homes Plan low-income grant allocations)
      Gap
      Not established
    • Property surveys, installation quality checks, remediation and monitoring

      A18 · recurring spending · not costed

      Amount
      Not yet costed
      Who pays
      central government, landlords, households
      Committed
      None identified
      Proposed, not committed
      —
      Gap
      Not established
    • Further levy rebalancing from electricity to gas or taxation

      A17 · bill transfer · not costed

      Amount
      Not yet costed
      Who pays
      bill-payers, central government
      Committed
      None identified
      Proposed, not committed
      —
      Gap
      Not established
    • Protection for households who cannot switch from gas

      A17 · bill transfer · partial

      Amount
      Not yet costed
      Who pays
      bill-payers
      Committed
      None identified
      Proposed, not committed
      —
      Gap
      Not established

    “Not yet costed” means no defensible cost has been found — not that the action is free. Lifetime benefits, benefit-cost ratios and forecast savings are never shown here as money available to spend.

    Effects on record, with evidence ratings (6 records)

    What the evidence says each action changes

    Effects on record — these measure different outcomes, so they are not drawn on one scale
    ActionOutcome and areaEffectCompared withEvidence
    Make electricity pricing support cheaper clean heatingRunning cost of switching from a gas boiler to a heat pump Energy and billsDirection plausible; size not established—modelled; limited confidence; Great BritainNesta modelled a saving of about £400 a year for a typical switcher, on 2025 prices before 75% of the Renewables Obligation moved to taxation; not re-run on today’s baseline, so no size is shown.
    Make electricity pricing support cheaper clean heatingBills of households that stay on gas Energy and bills · harmSize not established—modelled; limited confidence; Great BritainNesta put the rise at about £76 a year for gas households not eligible for support (about £20 for some 19 million households only if other levies also move to taxation, at about £1.1bn a year), modelled on the April 2025 price cap; households that cannot switch — many tenants — bear it. Corrected 4 Oct 2026 (was “about £20 before compensation”).
    Fix cold and inefficient homes with quality-assured workGas use in homes after solid wall insulation Energy and bills−17% median gas useindicative; varies year to year and includes households choosing to heat moresimilar homes without measures; 2024 savings for measures installed in 2023evaluated; moderate confidence; England and WalesObservational comparison, mostly from government schemes; savings for cavity and loft insulation are smaller.
    Fix cold and inefficient homes with quality-assured workGeneral, respiratory and mental health of residents Health and careDirection plausible; size not established—evaluated; limited confidence; Studies in several countries, searched to 2012The review says improvements “are possible”, clearest where warmth was inadequate; no current UK estimate and no cashable NHS saving.
    Fix cold and inefficient homes with quality-assured workLow-income households counted as fuel poor Poverty and inequalityDirection plausible; size not established—plausible spillover; limited confidence; EnglandThe fall in the headline count partly follows from the definition. Whether hardship actually falls depends on real bills, heating behaviour and prices, which the count does not measure.
    Fix cold and inefficient homes with quality-assured workDamp and mould after poorly specified or installed insulation Housing · harmSize not established—plausible spillover; limited confidence; EnglandThis is why A18 pairs grants with a survey before work and checks after it. No national rate of defects is published in the sources we checked.

    How we would know

    Households in fuel poverty; Price cap at typical use (dual fuel, direct debit); Electricity-to-gas unit price ratio in the cap; and 1 more.

    The outcome measures to watch. A baseline is where we start, not a target; where there is no official target we say so.

    Measured results

    What each option would be judged on, and the latest value of the measures already on this page. A measure moving is not proof that an option caused it.

    Where the ideas come from

    Research, counter-evidence and methods (12 sources; 2 claims held back)

    Counter-evidence and criticism

    • Fix cold and inefficient homes with quality-assured work: Savings vary year to year and include households choosing to heat more; health effects are uncertain and the review is old. (Cochrane / Hilary Thomson and colleagues)
    • Make electricity pricing support cheaper clean heating: After Budget 2025 policy costs are about a tenth of a typical bill, so further rebalancing has less to move; networks are about a third. (UK Energy Research Centre)
    • Hold network companies to the reformed connection timetable and publish time to connect: Deadlines have already slipped twice; network reinforcement, not the queue order, may be the binding constraint. (Ofgem)

    Claims held back

    • Heat-pump switchers would save about £400 a year under levy rebalancing — Modelled on 2025 prices before 75% of the Renewables Obligation moved to taxation; not re-run on the current baseline. Needed: Re-modelling on post-April 2026 tariffs.
    • The price cap is not a maximum bill (brief weakness, cited to S13) — Not located in S13. Needed: Cite Ofgem’s own explanation of the cap.

    “Full text checked” means we read the report itself; “relevant passages” means the sections behind each figure; “summary or abstract only” means we could not read the full study, so no number from it is published here without another source.

    Other options compared — not on the shortlist (4)

    Other options compared

    Options from earlier work on this page that are not on the shortlist. They remain valid choices; their evidence is shown as before.

    • immediate reliefStatus: operating

      Targeted help with bills for low-income households

      Aims to:
      Lower net bills this winter for the households least able to pay.
      How:
      The Warm Home Discount takes £150 off the electricity bill of eligible households. From winter 2025/26 it was widened to every household on means-tested benefits.
      Who decides:
      DESNZ (scheme rules); energy suppliers (payment); DWP (data matching).
      Main constraint:
      Eligibility is tied to benefits, so low-income households not claiming them miss out; £150 is fixed whatever the household’s usage.
      Evidence:
      Limited evidence — plausible mechanism, little direct evaluation
      See the trade-offs and evidence
      What the evidence shows
      The expansion added about 2.7 million households, to around 6.1 million across Great Britain. DESNZ estimates that more households receiving the discount, together with modelled efficiency upgrades, would on their own have taken about 153,000 households out of fuel poverty between 2024 and 2025 — an effect within the official measure, not an evaluation of warmth, health or arrears.
      Policy status
      Expanded for winter 2025/26 by regulations following the June 2025 government response.
      Resources
      Rebates paid by suppliers and recovered through a levy on all domestic bills; data matching between DWP and suppliers.
      Consent and decisions needed
      Set by regulations; the cost is recovered through all customers’ bills.
      Time
      Within one winter.
      Cost and yield
      Funded by a levy on bills: about £22 a year for a typical dual-fuel household before the expansion, and about £15 a year more after it (DESNZ impact assessment). Not funded from taxation.
      Trade-offs and who pays
      Paid for by everyone else’s bills, including some low-income households who are not eligible. Relief, not a fall in the cost of energy.
      How we would know it worked
      Leading indicator: Number of rebates paid each winter. Outcome: Fuel poverty rate and the average fuel poverty gap (DESNZ). It would not be working if: Rebates paid but the fuel poverty gap and arrears among eligible households do not fall.
    • immediate reliefStatus: operating

      Move policy costs and VAT off bills

      Aims to:
      Lower unit rates and standing charges for every household.
      How:
      Costs once collected through bills are paid from general taxation instead: from April 2026, 75% of the domestic Renewables Obligation and the end of the Energy Company Obligation; from October 2026, no VAT on domestic electricity.
      Who decides:
      HM Treasury and DESNZ; Ofgem (reflects the changes in the cap).
      Main constraint:
      Competes with every other call on public spending; time-limited unless renewed.
      Evidence:
      Moderate evidence — evaluated, with limits on scope or transfer
      See the trade-offs and evidence
      What the evidence shows
      The arithmetic effect on the cap is visible in Ofgem’s components: the policy-cost line fell in April 2026. The government put the saving at about £150 a year for a typical household (£88 Renewables Obligation, £59 Energy Company Obligation, £7 VAT); Ofgem put the October VAT removal at about £45. Whether it lowers what households pay in total depends on how the taxes that fund it fall.
      Policy status
      Renewables Obligation funding from the Exchequer covers 2026–27 to 2028–29; the electricity VAT change applies from 1 October 2026.
      Resources
      Exchequer funding each year in place of bill funding.
      Consent and decisions needed
      Budget decisions by the Chancellor; any extension needs a further fiscal decision.
      Time
      Immediate on the next cap period.
      Cost and yield
      Recurring public spending; see the Budget 2025 policy costings for the scored cost. Gross transfer from taxpayers to bill-payers, not a fall in the system’s cost.
      Trade-offs and who pays
      Shifts who pays from energy users (in proportion to use) to taxpayers (in proportion to income). It helps high users most in cash terms and ended a bill-funded insulation scheme.
      How we would know it worked
      Leading indicator: Policy-cost component in Ofgem’s cap. Outcome: Cap at typical use, and energy costs as a share of income for low-income households. It would not be working if: The policy line falls but the cap rises by more because of other costs — the relief is real but swamped.
    • structuralStatus: announced

      Weaken the link between gas and electricity prices

      Aims to:
      Electricity prices that depend less on the international gas price.
      How:
      More low-carbon generation on fixed-price contracts (Contracts for Difference), more storage and interconnection, and reforms to the wholesale market, so gas plants set the price less often and generators are paid more stable amounts.
      Who decides:
      DESNZ (market design, contracts); NESO (system operation); Ofgem; generators.
      Main constraint:
      Grid connections, planning consent, supply chains and the cost of capital. Electricity still carries network and policy costs that do not fall with wholesale prices.
      Evidence:
      Limited evidence — plausible mechanism, little direct evaluation
      See the trade-offs and evidence
      What the evidence shows
      Research cited by ONS found gas plants made 43% of UK electricity in 2021 but set the wholesale price 97% of the time, so gas prices pass through to electricity. How far more fixed-price generation lowers bills depends on contract prices, network and balancing costs; there is no evaluation of the whole package. The government rejected zonal pricing in July 2025 in favour of reformed national pricing.
      Policy status
      Reformed national pricing announced July 2025; Contracts for Difference allocation rounds continue.
      Resources
      Private capital for generation, backed by bill-funded contracts; transmission build; skilled engineers.
      Consent and decisions needed
      Planning decisions for each project; Contracts for Difference budgets set by DESNZ.
      Time
      Years: projects take several years from contract to operation.
      Cost and yield
      No official estimate of the net effect on household bills is cited here; contract payments are made through bills over each contract’s term.
      Trade-offs and who pays
      Fixed contracts protect against gas spikes but can cost more than the market when gas is cheap; new lines and plants affect local landscapes.
      How we would know it worked
      Leading indicator: Share of hours in which gas sets the wholesale price. Outcome: Wholesale component of the cap, adjusted for consumption, during a gas price spike. It would not be working if: A gas spike still moves the wholesale component as much as in 2022.
    • capacityStatus: operating

      Connect projects to the grid faster

      Aims to:
      Cheaper generation and storage connected sooner, rather than waiting years in a queue.
      How:
      Connections reform replaces “first come, first served” with “first ready and needed”, removing speculative projects from the queue so viable ones get earlier dates.
      Who decides:
      NESO (queue management); Ofgem (approval); transmission and distribution network operators (build).
      Main constraint:
      Physical network build, which reform does not speed up by itself; local consent for new lines.
      Evidence:
      Not evaluated — a mechanism to test, not an evidenced fix
      See the trade-offs and evidence
      What the evidence shows
      Ofgem approved NESO’s reform in April 2025; NESO says it can remove up to two-thirds of the oversubscribed queue. Faster connection dates are a delivery measure, not yet evidence of lower bills.
      Policy status
      Gated application process in force since 2025.
      Resources
      Network investment through Ofgem’s price controls, paid through bills; planning and supply-chain capacity for new lines and substations.
      Consent and decisions needed
      Ofgem code decisions; planning consent for transmission projects.
      Time
      Revised connection offers from 2025–26; physical reinforcement takes years.
      Cost and yield
      Administrative cost of reform is small; the network build it enables is paid through the networks part of every bill.
      Trade-offs and who pays
      Projects that lose their queue position bear the cost; more network spending raises the networks component of bills before any wholesale saving arrives.
      How we would know it worked
      Leading indicator: Median time from application to connection. Outcome: Wholesale and balancing costs per MWh over time. It would not be working if: Connection dates improve but network and balancing costs rise faster than any wholesale saving.
    The options side by side
    OptionResourcesTimeEvidenceOutcome to watch
    Targeted help with bills for low-income householdsRebates paid by suppliers and recovered through a levy on all domestic bills; data matching between DWP and suppliers.Within one winter.limitedFuel poverty rate and the average fuel poverty gap (DESNZ).
    Move policy costs and VAT off billsExchequer funding each year in place of bill funding.Immediate on the next cap period.moderateCap at typical use, and energy costs as a share of income for low-income households.
    Weaken the link between gas and electricity pricesPrivate capital for generation, backed by bill-funded contracts; transmission build; skilled engineers.Years: projects take several years from contract to operation.limitedWholesale component of the cap, adjusted for consumption, during a gas price spike.
    Connect projects to the grid fasterNetwork investment through Ofgem’s price controls, paid through bills; planning and supply-chain capacity for new lines and substations.Revised connection offers from 2025–26; physical reinforcement takes years.not evaluatedWholesale and balancing costs per MWh over time.

    Plan reviewed 2026-10-07. How we judge evidence.

    How this connects

    • Can power and grid capacity support new industry?

      Industrial electricity prices, generation by source and what they mean for growth.

      Household capped tariffs cannot explain industrial electricity costs; that page uses a separate industrial price series.

    • How long is the queue to connect to the grid?

      New generation and storage cannot lower costs until they are connected; the connections queue is one of the binding constraints.

    • What do private renters pay for a home?

      Private renters have the highest fuel poverty rate in England, and rent comes out of the same income as energy.

      Fuel poverty and rent burden come from different surveys.

    • Who has least room in their budget?

      Required energy costs were 14.9% of after-housing-cost income for low-income households in England in 2025, against 6.8% for all households (DESNZ), so the same price rise takes a bigger bite.

      Energy cost shares are modelled by DESNZ; income inequality uses different surveys.

    Sources and methods (10)

    Method notes

    • The cap is set for Great Britain only. Northern Ireland’s energy prices are regulated separately by the Utility Regulator and are not in these figures. CPI indices cover the whole UK; fuel poverty statistics cover England.
    • All cap figures are for default tariffs paid by direct debit, GB average, single-rate electricity. Ofgem restates past periods at its latest typical consumption (2,500 kWh electricity and 9,500 kWh gas from July 2026), so they differ from the figures announced at the time.
    • Real-terms figures deflate each cap period by CPI (all items) for its first month, expressed in Aug 2026 prices. Periods starting after the latest CPI month are left out of the real-terms chart rather than estimated.
    • Unit rates and standing charges are derived from Ofgem’s nil- and typical-consumption levels using Ofgem’s own definition of the cap; they match Ofgem’s published consumer rates to the penny.

    Rates for Oct–Dec 2026: electricity 26.32p/kWh and 54.83p/day; gas 7.97p/kWh and 29.68p/day (GB average, direct debit).